
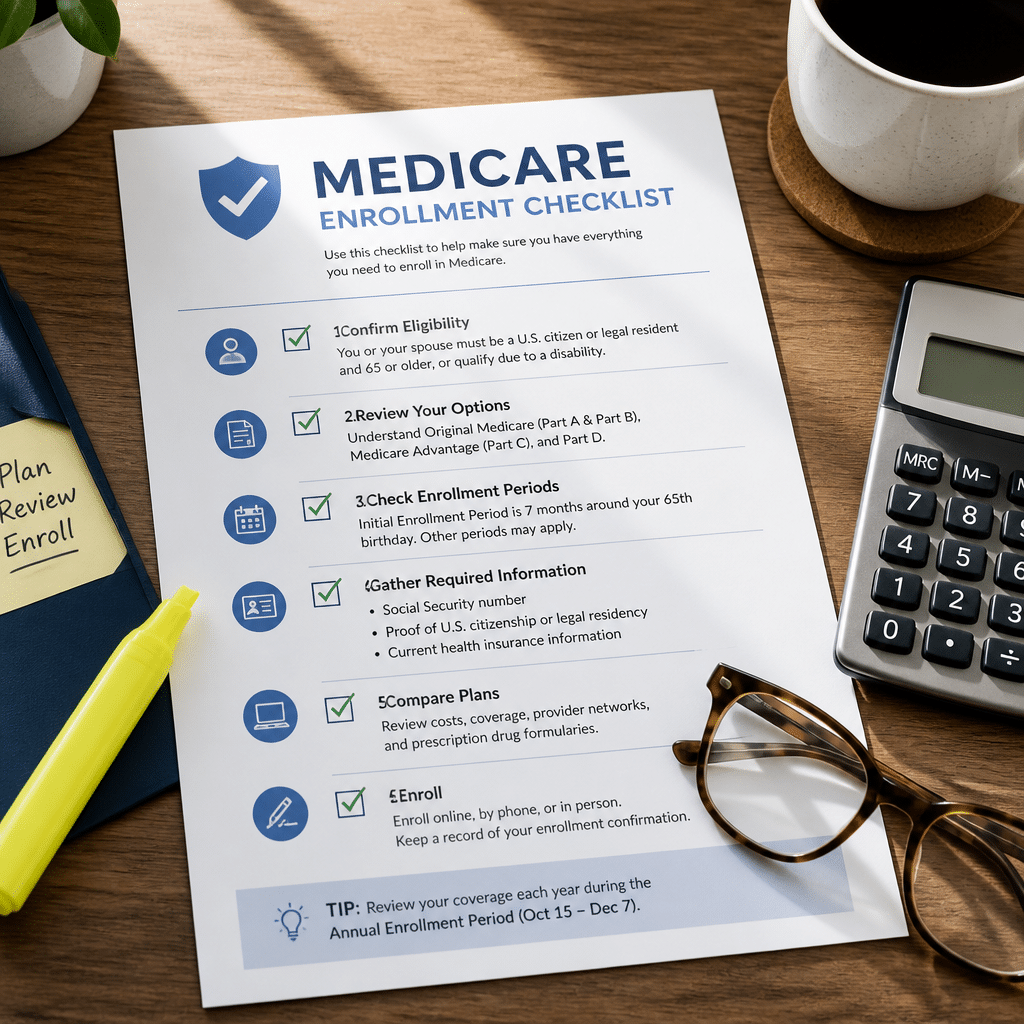
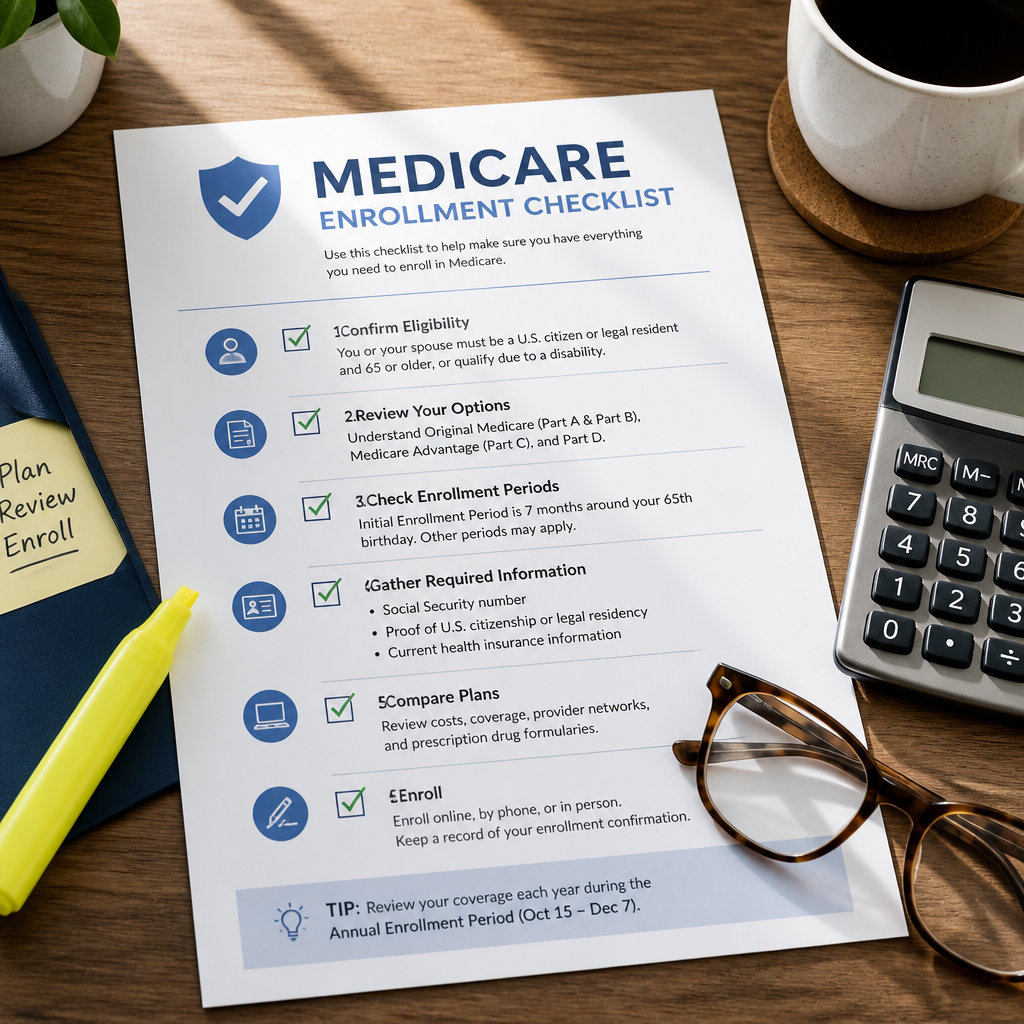
Most people turning 65 spend more time researching a new car than they do vetting the Medicare insurance agent who will guide them into a coverage decision that affects their health and finances for years. That is a costly mistake. The questions you ask your agent before signing anything determine whether you land on a plan that fits your life or one that quietly costs you thousands in out-of-pocket expenses, late enrollment penalties, or lost access to the doctors you trust. This questions to ask Medicare agent checklist gives you the exact language to use, plus the reasoning behind each question so you understand what a solid answer looks like.
Table of Contents
- Quick Takeaways
- Why Your Agent Choice Matters More Than the Plan
- Medicare Advantage vs. Medicare Supplement vs. Original Medicare: Comparison
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| State licensure is non-negotiable | An agent must be licensed in North Carolina specifically to legally sell Medicare plans here. Do not assume a national brand means local authorization. |
| More carriers means more choices for you | An independent agent representing 30+ companies can compare plans across the market. A captive agent can only show you one carrier’s options. |
| The premium is the smallest part of total cost | Deductibles, copays, coinsurance, and out-of-pocket maximums often dwarf the monthly premium. Always ask for a total annual cost estimate. |
| Late enrollment penalties are permanent | Missing your Medicare Part B or Part D enrollment window can add a lifelong surcharge to your premiums. An agent who does not raise this topic is missing a critical obligation. |
| Doctor network compatibility must be verified, not assumed | A plan can look ideal on paper until you discover your cardiologist or specialist is out-of-network. Always confirm with a specific provider list, not a verbal assurance. |
| CMS requires agents to discuss specific topics before enrollment | Federal rules require agents selling Medicare Advantage and Part D plans to cover eligibility, costs, network rules, and drug coverage before you sign. Ask if they follow this process. |
| Post-enrollment support separates good agents from order-takers | A quality agent reviews your plan annually and helps you switch during the Annual Enrollment Period if a better fit exists. Silence after enrollment is a red flag. |
Why Your Agent Choice Matters More Than the Plan
People approaching Medicare eligibility in the Charlotte area have access to a large number of plans across Medicare Advantage, Medicare Supplement (Medigap), and Prescription Drug Plans. The volume of options is not the problem. The problem is that without an experienced, independent agent walking you through a structured comparison, most people default to whichever plan they saw advertised most recently.
A good agent does not just hand you a brochure. They ask about your prescriptions, your doctors, your travel habits, and your budget before recommending anything. When choosing a Medicare insurance agent in Charlotte, the questions you ask them at the start reveal whether you are talking to a trusted advisor or a plan-pusher.
The ten questions below are a practical Medicare consultation checklist. Use them in your first conversation with any agent, including any agent from Safeguard Benefit Services, before making a single coverage decision.
Are You Licensed to Sell Medicare Plans in North Carolina?
This sounds obvious, but it trips up a surprising number of people who call national 1-800 numbers or respond to online ads placed by out-of-state agencies. An agent must hold an active insurance license in North Carolina and must be appointed by the specific carrier whose plan they are recommending. These are two separate requirements.
What a solid answer looks like
The agent should be able to state their North Carolina license number and confirm they are appointed with the carriers they are discussing. If they hesitate or pivot the conversation, end it. Verifying a license takes two minutes on the North Carolina Department of Insurance website.
Pro tip: Ask for the agent’s National Producer Number (NPN) as well. This federally-issued number lets you cross-check their credentials through the National Insurance Producer Registry, giving you an additional layer of verification beyond the state license alone.
How Many Carriers Do You Represent?
An agent who represents only one insurance company is a captive agent. They can only offer you plans from that company, which means they cannot tell you whether a competitor’s plan would save you money or better cover your medications. They are, by design, not working in your best interest when it comes to carrier selection.
Independent vs. captive agents
An independent Medicare broker represents multiple carriers and is obligated to recommend the plan that fits your needs, not the plan that pays the highest commission. Agencies like Safeguard Benefit Services work with 30 or more companies across Medicare Supplement, Medicare Advantage, and Part D plans, which means the recommendation you receive is drawn from a real market comparison rather than a single company’s product lineup.
The more carriers an agent can access, the more confident you can be that the recommendation reflects your situation rather than their sales quota.
How Are You Compensated?
This question makes some people uncomfortable, but it is one of the most important ones on this list. Medicare agents are generally compensated through commissions paid by the insurance carriers, not by you. That means a consultation with a licensed independent agent is typically free to you as the consumer.
However, the commission structure can create conflicts of interest. Some plans pay higher commissions than others. A good agent discloses this openly and explains that CMS sets maximum commission rates that carriers cannot exceed, which levels the playing field somewhat. If an agent is evasive about compensation, that is a signal worth noting.
Pro tip: Ask specifically whether the agent earns the same commission regardless of which plan you choose. Many independent brokers receive standardized compensation across carriers for plans of the same type, which reduces the incentive to steer you toward a higher-paying option.
Will My Current Doctors Accept This Plan?
Network restrictions are one of the most common sources of post-enrollment regret. A Medicare Advantage plan may have a $0 premium and comprehensive benefits, but if your primary care physician or specialist is not in its network, you face either paying out-of-network rates or switching providers. Neither is acceptable if the agent did not raise this issue before you enrolled.
How to verify provider networks properly
Do not accept a verbal assurance that “most doctors accept this plan.” Ask the agent to pull up the plan’s online provider directory and search for your specific physicians by name and location, right there during the consultation. For Medicare Supplement (Medigap) plans, this is less of a concern since they typically allow you to see any provider who accepts Medicare. For Medicare Advantage HMO and PPO plans, network verification is mandatory before signing.
Patients in the Charlotte metro area who regularly see specialists at major health systems should be especially diligent about this step, since network participation by large hospital systems can shift from one plan year to the next.
Are My Prescriptions Covered and at What Tier?
Prescription drug coverage (Medicare Part D) uses a tiered formulary system. Your medication might be covered by a plan but placed on a higher tier, meaning you pay significantly more in cost-sharing than a lower-tier alternative. Two plans with the same premium can have dramatically different costs for the exact same drug depending on formulary placement.
Bring a complete, current list of your medications, including dosage and frequency, to every Medicare consultation. A competent agent will run your drug list through the plan’s formulary tool before making any recommendation. Seniors in the Charlotte area who manage chronic conditions such as diabetes, heart disease, or arthritis often find that drug coverage costs vary more between plans than any other cost component.
What Is My Total Annual Cost, Not Just the Premium?
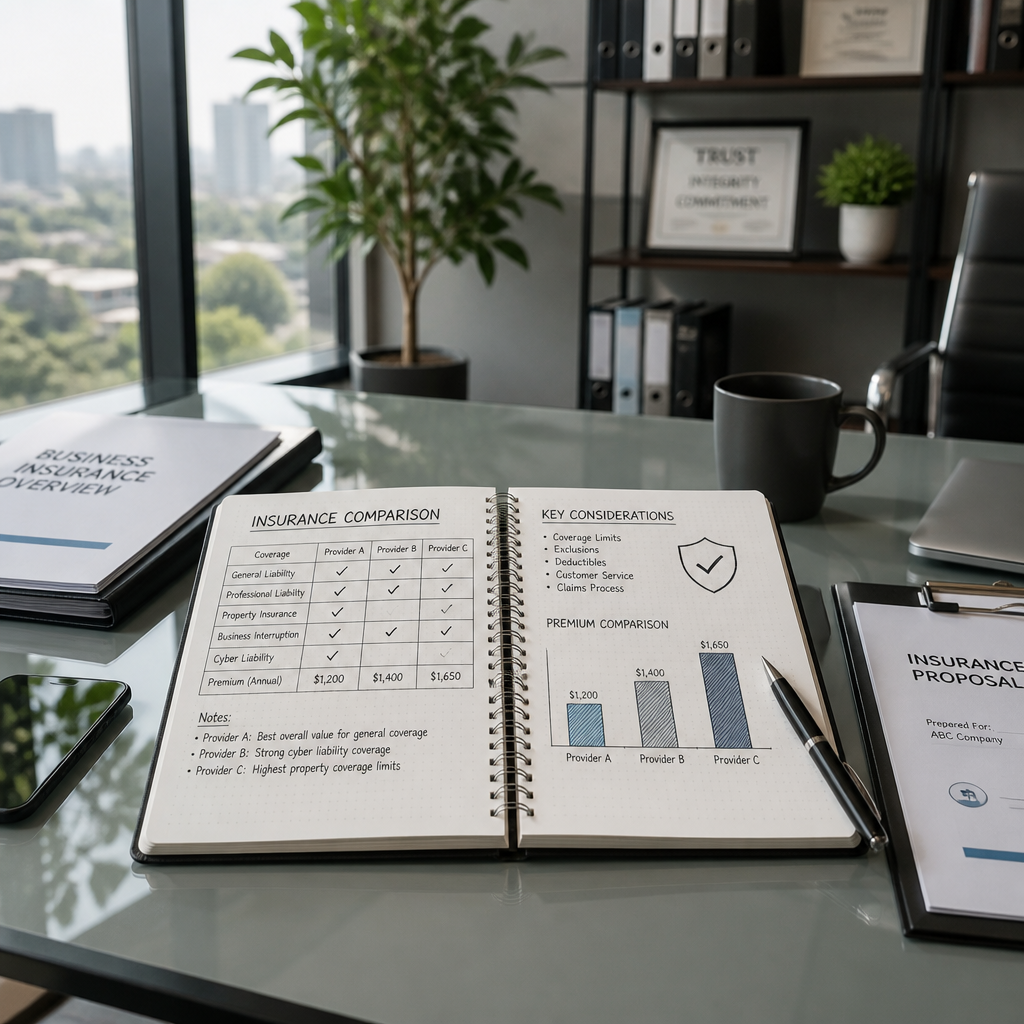
The monthly premium is what gets advertised. It is also the least informative number when comparing plans. Your true cost of coverage includes the deductible, copayments for office visits and specialist appointments, coinsurance for hospital stays, and the plan’s annual out-of-pocket maximum.
The most common mistake people make when comparing Medicare plans is treating the monthly premium as the total cost. A plan with a low premium can easily become the most expensive option once you factor in deductibles, copays, and out-of-pocket maximums.
Ask the agent to build a projected annual cost estimate based on your actual healthcare usage. If you visit your doctor four times a year, take three prescriptions, and had one specialist visit in the past year, a good agent can use that baseline to estimate what each plan would have actually cost you. That number, not the premium alone, is the right basis for comparison.
What Happens if I Miss My Enrollment Window?
This question is not hypothetical for most people turning 65. Many people assume they can sign up for Medicare at any time, the same way they can sign up for other insurance. That assumption leads directly to late enrollment penalties that follow them for life.
Understanding the Initial Enrollment Period
Your Initial Enrollment Period (IEP) opens three months before the month you turn 65, includes the month of your birthday, and closes three months after. Missing this seven-month window without qualifying coverage in place triggers penalties. The Part B late enrollment penalty adds 10% to your premium for every 12-month period you delayed enrollment, and you pay it for as long as you have Medicare Part B. That is a permanent cost increase, not a one-time fee.
Part D penalties work differently but hurt just as much
The Part D late enrollment penalty is calculated based on the number of months you went without creditable prescription drug coverage. It is added to your monthly Part D premium and also lasts for the lifetime of your coverage. An agent who does not proactively discuss your enrollment timing and whether your current employer coverage qualifies as creditable is leaving critical information on the table.
What Is the Difference Between Medicare Advantage and a Medicare Supplement?
This is the foundational coverage decision, and it deserves a clear, unscripted explanation from any agent you work with. Many people arrive at a Medicare consultation not knowing these are two entirely different approaches to covering the gaps in Original Medicare.
The core structural difference
A Medicare Supplement (Medigap) plan works alongside Original Medicare. You keep Medicare Parts A and B, and the Supplement policy pays some or all of the cost-sharing Medicare does not cover. You can generally see any provider who accepts Medicare nationwide, with no network restrictions.
A Medicare Advantage plan replaces Original Medicare with coverage provided by a private insurance company. These plans often include prescription drug coverage, and some include dental, vision, and hearing benefits that Original Medicare does not cover. The tradeoff is that most Medicare Advantage plans use networks of preferred providers, and coverage outside the network may cost significantly more or require prior authorization.
Which is better for Charlotte-area residents
Neither option is universally better. The right answer depends on your health status, your prescriptions, how often you travel, and whether your current providers participate in the plan’s network. An agent who tells you one type is always better without asking about your situation is not giving you advice. They are giving you a sales pitch. The most popular Medicare Supplement plan in North Carolina is Plan G, followed by Plan N, based on enrollment patterns in the state, but the right plan depends on your specific circumstances.
What Support Do You Provide After I Enroll?
A Medicare plan is not a set-it-and-forget-it decision. Formularies change every year. Premium rates change. Your health situation changes. Networks shift. What was the right plan in year one may not be the right plan in year three. The Annual Enrollment Period, which runs from October 15 through December 7 each year, exists specifically to let you reassess and change plans if needed.
Ask the agent directly: will they contact you each fall to review your coverage before the Annual Enrollment Period closes? Will they be accessible by phone or in person if a claim is disputed or a coverage question arises mid-year? Licensed agents at Safeguard Benefit Services in Charlotte provide year-round support rather than disappearing after the enrollment paperwork is filed. That kind of ongoing relationship is what separates a genuine advisor from someone who processed a transaction.
Can You Walk Me Through the CMS Pre-Enrollment Checklist?
The Centers for Medicare and Medicaid Services (CMS) requires agents selling Medicare Advantage and Part D plans to discuss a defined set of topics with every client before enrollment. These include Medicare eligibility rules, primary care and specialist access, prescription drug costs and coverage, plan benefits, cost-sharing details, and the effect of changing Medicare coverage.
Asking this question directly accomplishes two things. First, it signals to the agent that you are an informed consumer who expects a thorough process. Second, it gives you a clear, federal-standard framework for evaluating whether the agent is actually doing their job. A well-trained agent will welcome this question. An agent who has not covered the required topics and does not recognize the checklist reference is someone you should think carefully about trusting with your coverage decision.
The CMS Pre-Enrollment Checklist (PECL) is often included with a plan’s Summary of Benefits in the enrollment kit. A diligent agent will walk through it with you and confirm each item is addressed before asking you to sign.
Medicare Advantage vs. Medicare Supplement vs. Original Medicare: Comparison
Before your consultation, it helps to understand the structural differences between the three main coverage approaches. This table is a starting point for that conversation, not a substitute for personalized guidance from a licensed agent who knows your specific situation.
| Coverage Type | How It Works | Best For |
|---|---|---|
| Original Medicare (Parts A and B) | Federal coverage for hospital (Part A) and medical (Part B) services. No network restrictions nationally. Leaves significant cost-sharing gaps. Usually combined with Part D and a Supplement or Advantage plan. | People who want maximum provider flexibility and plan to add a Supplement policy to cover gaps. |
| Medicare Supplement (Medigap) | Private plan that wraps around Original Medicare to cover cost-sharing like deductibles and coinsurance. No network restrictions. Requires a separate Part D plan for drug coverage. Monthly premiums are generally higher. | People with frequent healthcare needs, significant travel, or who prioritize predictable out-of-pocket costs and access to any Medicare provider nationwide. |
| Medicare Advantage (Part C) | Private plan that replaces Original Medicare. Often includes Part D drug coverage. May include dental, vision, and hearing extras. Uses provider networks (HMO or PPO). Premiums can be lower but cost-sharing varies significantly by plan and usage. | People in generally good health who stay local, prefer bundled coverage, and whose doctors participate in the plan’s network. |
Frequently Asked Questions
What is the best time to schedule a Medicare consultation?
The best time is three to six months before you turn 65 or before you lose employer-sponsored coverage. This gives you enough time to understand your options without the pressure of an approaching deadline. Rushing a Medicare decision is one of the most reliable ways to end up in the wrong plan.
Is it really free to work with a Medicare insurance agent?
Yes. Independent Medicare insurance agents are compensated through commissions paid by the insurance carriers, not by you. There is no consultation fee and no cost to compare plans. The carrier pays the same commission whether you enroll through an agent or directly, so using an independent agent costs you nothing and gives you expert guidance you would not otherwise have.
Can I switch Medicare plans if I make a mistake during initial enrollment?
Yes, but the opportunities to change are limited to specific enrollment periods. The Annual Enrollment Period runs from October 15 to December 7 each year. Medicare Advantage enrollees also have a separate Medicare Advantage Open Enrollment Period from January 1 to March 31. Outside these windows, changes are only allowed under qualifying Special Enrollment Period events such as moving, losing other coverage, or qualifying for Medicaid. This is exactly why getting the initial decision right matters, and why a thorough consultation with an agent who asks the right questions upfront is worth the time.
How do I know if my employer coverage counts as creditable before I sign up for Medicare?
Creditable coverage means your current employer plan covers at least as much as Medicare Part D covers. Your employer is required to notify you in writing each year whether your coverage is creditable. If you are unsure, ask your HR department directly and keep the written confirmation. An agent who specializes in Medicare should be able to help you interpret that letter and advise you on whether delaying Part D enrollment makes sense in your situation.
Should I work with a local Medicare agent in Charlotte or is an online agent just as good?
A local agent who knows the North Carolina market, the carriers active in the Charlotte area, and the provider networks available here offers a practical advantage. Medicare Advantage networks vary significantly by county, and a local agent is more likely to know which plans have the strongest provider participation in the Charlotte metro. Online or national agents can be adequate for straightforward situations, but when plan networks and local provider relationships matter, local expertise makes a real difference.
What should I bring to my Medicare consultation?
Bring a complete list of all current medications with dosages and frequencies, the contact information for all doctors and specialists you see regularly, your current insurance card if you have employer or other coverage, and your Social Security card or Medicare card if you have already received one. The more specific information you bring, the more accurate the plan comparison your agent can build for you.
If you are approaching Medicare eligibility in the Charlotte area and want a consultation where all ten of these questions get answered clearly and without pressure, share your experience below or tell us which question you wish someone had asked you before your first enrollment.
We would love your feedback and any insights you would share with others. What perspective would you add?
References
- National Council on Aging: Top Questions to Ask Before Enrolling in a Medicare Plan
- Ritter Insurance Marketing: What CMS Requires Agents to Discuss Prior to Medicare Enrollments
- Healthpilot: Top Questions to Ask Before Choosing a Medicare Plan
- National Council on Aging: Understanding Medicare Late Enrollment Penalties








Get Connected