
If you have a Medicare Advantage or Part D plan, your insurer must send you an Annual Notice of Change showing how your premiums, drugs, and network will shift next year. Read it as soon as it arrives, compare the changes against your current coverage, and act before Open Enrollment closes on December 7. If it never showed up, call your plan or 1-800-MEDICARE right away.
TL;DR:
- Check your medications for higher tiers or removal, and confirm directly with your doctors and pharmacy that they remain in network next year.
- Only Medicare Advantage and Part D enrollees receive an ANOC; Original Medicare with Medigap does not, and the Evidence of Coverage spells out plan rules.
- Medicare.gov’s Plan Finder typically reflects next year’s prices around October 1, giving you about two weeks before Open Enrollment starts October 15.
- Current Medicare Advantage enrollees can make one additional switch from January 1 through March 31, with coverage changes effective the following month.
- If your plan exits your area, its notice should explain next steps; choose a replacement during an eligible enrollment window to avoid a coverage gap.
Table of Contents
- What the ANOC is and how it differs from the Evidence of Coverage
- Checklist: what to check in your ANOC before you decide anything
- Timing and key dates: when ANOCs arrive and the windows you can’t miss
- Step-by-step actions after you open the ANOC
- How we help you review your ANOC changes
- A few honest notes on what beneficiaries get wrong every fall
- Get a free Medicare roadmap or ANOC review from our team
- FAQ
- Sources
- Official Medicare pages and tools to verify dates and compare plans
What the ANOC is and how it differs from the Evidence of Coverage
The Annual Notice of Change is a short summary. It tells you what is changing in your plan for next year: premiums, deductibles, drug tiers, and network rules. The Evidence of Coverage, by contrast, is the full plan manual, the document that spells out every benefit, rule, and exclusion in detail.
Only people enrolled in a Medicare Advantage plan or a stand-alone Part D drug plan receive an ANOC. If you have Original Medicare paired with a Medigap policy, you will not get one, since Original Medicare’s benefits are set by federal law and do not change plan by plan.
- The ANOC flags what is different for next year.
- The EOC explains the full rules behind every benefit.
- Medicare Advantage and Part D enrollees get an ANOC; Original Medicare and Medigap holders do not.
- Your plan’s website or member portal usually has the EOC, or you can request a copy directly from the plan.
For a closer look at how these notices apply to the coming plan year, our detailed ANOC guide walks through what Charlotte-area enrollees are seeing for 2026.
Checklist: what to check in your ANOC before you decide anything
Not every line in the notice matters equally. Some changes barely touch your wallet, while others can mean a different doctor or a jump in what you pay for a daily prescription. Work through these in order.
- Premium, deductible, and out-of-pocket maximum: compare next year’s numbers line by line against this year’s.
- Copays and coinsurance: check whether your usual office visits, specialist care, or hospital stays cost more.
- Drug formulary: find each of your medications and see if it moved to a higher cost tier or dropped off the list entirely.
- Provider and pharmacy network: confirm your doctors, specialists, and pharmacy are still listed as in-network for next year.
- Supplemental benefits: look for changes to dental, vision, hearing, or over-the-counter allowances, and note any new prior authorization requirements.
Pro Tip: Start with your prescription list and your primary doctor’s network status. Those two checks catch most of the changes that actually affect your health and your wallet.
According to Medicareresources, ANOCs commonly cover premium and cost changes, formulary updates, network changes, and a side-by-side view of this year’s coverage against next year’s, which makes the notice a genuine comparison tool rather than a formality. If your plan is leaving the market or ending service in your area, the same notice should spell out your next steps, and you will need to pick a new plan during an enrollment window to avoid a gap in coverage.
Timing and key dates: when ANOCs arrive and the windows you can’t miss
Plans are required to get your ANOC to you by September 30, since it needs to reach you well ahead of enrollment season. If you have not received yours by early October, contact your plan directly or call 1-800-MEDICARE.
- ANOC delivery deadline: by September 30, covering changes effective January 1.
- Open Enrollment (AEP): October 15 through December 7, when you can switch Medicare Advantage or Part D plans, and changes take effect January 1.
- Medicare Advantage Open Enrollment (MA-OEP): January 1 through March 31, when those already in a Medicare Advantage plan get one additional switch, effective the first of the month after the plan receives the request.
- Special Enrollment Periods: separate, narrower windows tied to specific events, like losing coverage or moving, rather than the general fall calendar.
If a life event or plan termination triggers one of these exceptions, our guide to mid-year Medicare changes breaks down how Special Enrollment Periods work.
Step-by-step actions after you open the ANOC
Once you have read through the notice and marked what changed, turn that information into a decision using these steps.
- Read the summary of changes page first and circle anything that affects your costs, drugs, or doctors.
- Starting around October 1, use the Medicare.gov Plan Finder to compare total costs and drug coverage across plans, since the tool typically reflects next year’s pricing early in the month, ahead of Open Enrollment.
- Call your doctors and pharmacy to confirm they will still be in-network next year rather than relying on the ANOC alone.
- Contact your plan for clarification, request the full Evidence of Coverage if you need more detail, or call 1-800-MEDICARE for an outside opinion.
- Decide and enroll by December 7 if you are switching plans during Open Enrollment, or use the January through March window if you already have Medicare Advantage and qualify for that one change.
Keep a simple record of who you called, what they confirmed, and the date, since that paper trail matters if a dispute comes up later. Plan Finder’s early October refresh gives you roughly two weeks of preview time before Open Enrollment opens on October 15, which is enough to compare two or three options without rushing a decision in early December.
How we help you review your ANOC changes
Reading an ANOC is one thing. Knowing what a formulary tier change actually means for your monthly budget, or whether a network update will force you to switch cardiologists, is another. That is where a local review helps.
- We offer a Medicare roadmap that helps explain your current coverage and any upcoming changes.
- We provide consultations to review your specific ANOC details.
- We conduct annual plan reviews to help ensure nothing is overlooked between enrollment seasons.
This kind of help matters most when you manage a complex drug regimen, when your plan’s network has shifted, or when your plan is leaving the market altogether. Our annual plan review service explains how these reviews work in more detail, and if a benefit change affects ongoing care like physical therapy, Contemporary Rehab Services has useful guidance on what Medicare covers for therapy sessions in 2026.
A few honest notes on what beneficiaries get wrong every fall
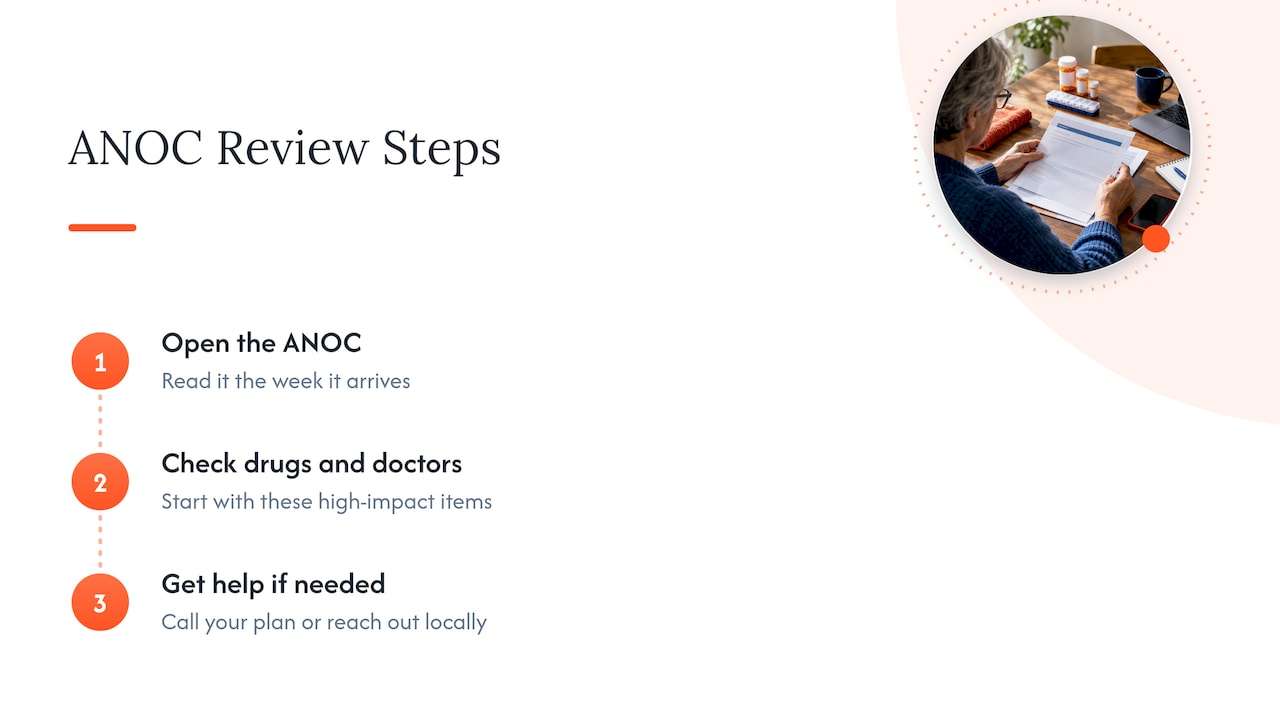
The biggest mistake we see is treating the ANOC like junk mail. It often arrives in the same stack as plan marketing, and people toss it without opening it. That single habit causes more mid-year coverage surprises than any other factor.
Read it the week it arrives. Check your drugs and your doctors first, since those two items carry the most real-world impact. If anything looks off, call your plan or reach out locally. We are glad to help you make sense of it.
— Zach
Get a free Medicare roadmap or ANOC review from our team
ANOC season moves fast, and a second set of eyes catches things a quick skim misses. We built our free Medicare roadmap to walk you through exactly what changed in your plan and what it means for your costs next year.

- Bring your current ANOC, a list of your prescriptions, and your doctors’ names to your consultation.
- We review premiums, drug tiers, and network status against what you have now.
- We help you compare Medicare Advantage, Medigap, and Part D options side by side.
Request a consultation through our Safeguard Benefit Services page, or start with our breakdown of Medicare Advantage Plans under Part C if you are weighing a switch this fall.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Why can’t you get Medicare at 62?
Medicare eligibility generally starts at the traditional retirement age, with exceptions for certain disabilities or conditions like ESRD. If you are under the usual eligibility age and researching coverage, you will typically need to wait until you qualify by age or condition to enroll unless you meet one of those exceptions.
Is there any reason to keep Medicare summary notices?
Yes, keeping your Medicare Summary Notices gives you a record of claims and payments that can help resolve billing disputes or confirm what a provider actually charged. They also help you spot errors or potential fraud on your account.
What is the most highly rated Medicare supplement plan?
Ratings vary by insurer, state, and the specific plan letter, so there is no single plan that ranks highest everywhere. Comparing Medigap options side by side with a licensed agent is the most reliable way to find the best fit for your situation.
What are Medicare rules?
Medicare rules cover who is eligible, when you can enroll, what each part covers, and how costs like premiums and deductibles work each year. The clearest place to check current rules is Medicare.gov, since plan details and enrollment windows can shift from year to year.
Sources
Official Medicare pages and tools to verify dates and compare plans
- Medicare for current dates and plan comparisons.
- Medicare’s key dates publication for a yearly calendar overview.
- Call 1-800-MEDICARE or your local SHIP office for unbiased, one-on-one help.
Recommended
Request a No Obligation Phone Call








Get Connected