
If you qualify for Medicare, Medicare, not a Marketplace plan, is usually your primary coverage going forward. Enroll during your Initial Enrollment Period and report your Medicare start date to the Marketplace right away. Doing this avoids double premiums and keeps you from owing back tax credits for months when both plans overlap.
TL;DR:
- Enroll in Part B during your Initial Enrollment Period unless qualifying employer coverage applies; Marketplace insurance does not permit a safe delay.
- Report your Medicare start date to HealthCare.gov up to three months early and end Marketplace coverage the day before Medicare begins to prevent overlap.
- For 2026, Part B costs $202.90 monthly with a $283 deductible; Original Medicare has no annual out of pocket cap without supplemental coverage.
- A 63 day gap in creditable prescription coverage can trigger a Part D late enrollment penalty; Marketplace drug coverage is not always creditable.
- If you pay a Part A premium, have ESRD, or face retroactive Medicare coverage, compare costs and seek guidance because enrollment rules may not fit.
Table of Contents
- Why Marketplace plans and Medicare rarely work together
- Comparing the real costs: premiums, deductibles, and tax credits
- When to enroll and how to avoid long-term penalties
- Exceptions: when Marketplace coverage might still make sense
- Your transition checklist for the weeks around enrollment
- How a local Medicare agent fits into this transition
- A straight take on getting this right at 65
- Get help comparing your options and enrolling
- FAQ
- Sources
Why Marketplace plans and Medicare rarely work together
Marketplace plans come from the individual ACA market and are built for people without other coverage. Medicare is different: Original Medicare covers hospital care (Part A) and outpatient care (Part B), Medicare Advantage (Part C) bundles those benefits through a private insurer, and Part D covers prescription drugs separately.
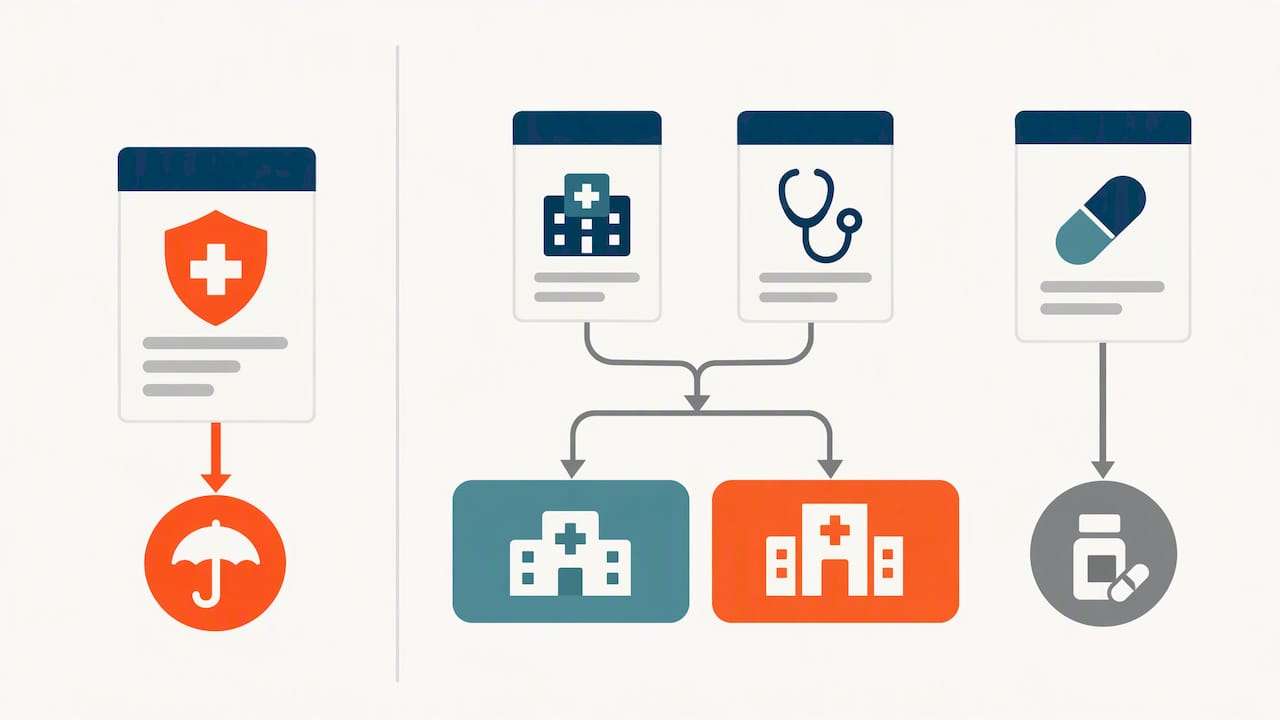
Once you have Medicare, the Marketplace explicitly stops being your intended coverage source. You cannot receive Marketplace financial help if you already have Medicare, and it is against the rules for anyone to knowingly sell you a Marketplace plan once you’re enrolled. The two systems were never built to coordinate benefits with each other.
A few practical consequences follow from this:
- Claims submitted to both plans typically duplicate each other instead of filling gaps.
- Marketplace subsidies and cost-sharing reductions end once you have premium-free Part A.
- Carrying both means paying two premiums for coverage that mostly overlaps.
That is the structural reason behind the simple rule: when Medicare eligibility starts, Marketplace coverage should generally end.
Comparing the real costs: premiums, deductibles, and tax credits
The cost comparison matters because it shapes whether you keep any Marketplace involvement at all. In 2026, the standard Part B monthly premium is $202.90, and the Part B deductible is $283. Most people get Part A with no premium, but some who do not qualify for premium-free Part A may pay a monthly premium that varies based on their work history, a figure worth weighing against any Marketplace plan you’re considering instead.
If you’re eligible for premium-free Part A, Marketplace subsidies stop and overlap can mean repaying advance premium tax credits for the months both plans were active, according to CMS guidance on Medicare and the Marketplace. That repayment risk is one of the most expensive mistakes people make during this transition.
A few other cost differences to weigh:
- Marketplace plans cap your yearly out-of-pocket spending; Original Medicare has no such cap on its own.
- Medigap or Medicare Advantage fills that gap differently: Medigap pays after Medicare, while Advantage plans build in their own out-of-pocket maximum.
- Marketplace drug coverage counts as an essential health benefit but isn’t guaranteed to be “creditable” compared with Part D, and a gap of 63 days or more without creditable drug coverage can trigger a Part D late-enrollment penalty.
Reviewing Medicare Advantage versus Medigap side by side helps clarify which approach to out-of-pocket risk fits your situation better.
When to enroll and how to avoid long-term penalties
Timing drives almost every costly mistake in this transition, so treat your enrollment window as the most important date on your calendar.
- Your Initial Enrollment Period runs for seven months: three months before you turn 65, your birthday month, and three months after.
- Enroll in Part B during this window unless you have qualifying employer coverage. Marketplace coverage does not count as a valid reason to delay, and missing your window can mean a 10% premium penalty for each 12-month period you wait.
- Report your Medicare start date to HealthCare.gov as early as three months before coverage begins so your Marketplace plan ends the day before Medicare starts, closing the gap cleanly.
- If you have questions about timing, call Social Security, 1-800-MEDICARE, or the Marketplace Call Center directly rather than guessing.
Our Part B penalty calculator gives you a quick way to see what a delay could cost before you decide to wait.
Exceptions: when Marketplace coverage might still make sense
A few situations call for more care than the general rule above, making a full cost comparison of Marketplace and private plans essential before deciding.
- If you don’t qualify for premium-free Part A, run a full cost comparison, premiums plus expected out-of-pocket spending, before deciding whether to buy Part A or stay on a Marketplace plan.
- End-stage renal disease (ESRD) carries its own enrollment rules and timing, so get individualized guidance rather than following the general timeline.
- Active employer group coverage can let you delay Part B safely with a Special Enrollment Period later; Marketplace coverage usually does not offer that same protection.
- If Medicare starts retroactively, you can request retroactive termination of Marketplace coverage, but CMS limits how far back that request can reach, so act quickly once you know your effective date.
Your transition checklist for the weeks around enrollment
A short, ordered process keeps this transition from turning into a paperwork headache.
- Confirm your exact Medicare start date with Social Security or Medicare.gov before you touch your Marketplace application.
- Report that start date to the Marketplace up to three months early, and set your Marketplace end date for the day before Medicare begins.
- Keep your Marketplace plan active until that end date. If you’re using premium tax credits, update your application promptly to avoid owing money back later.
- If Medicare ends up starting retroactively, file your request for retroactive Marketplace termination within the allowed window and keep copies of everything.
- When any part of this feels uncertain, call Social Security for enrollment timing, 1-800-MEDICARE for plan questions, or the Marketplace Call Center for reporting and terminations.
Pro Tip: Bring a printed copy of your Marketplace policy and any Medicare notices to every call or appointment. It saves time and avoids repeating your situation from scratch.
Our guide on how to enroll in Medicare walks through each of these steps in more detail.
How a local Medicare agent fits into this transition
Licensed agents can review your Part A and Part B cost obligations, compare Medicare Advantage against Medigap, and estimate your total annual cost picture, premiums plus likely out-of-pocket spending, side by side.
We provide specialized Medicare insurance consultations and a free Medicare roadmap. Our offerings include Medicare Advantage Plans, Medicare Supplements, Prescription Drug Plans, and supplemental Dental, Vision, and Hearing Plans. Our agents receive comprehensive training to provide consistent, long-term support rather than a one-time sales pitch. Our Medicare Advantage versus Medigap comparison and our Medicare versus Medicaid explainer cover the distinctions people ask about most.
- Bring your Marketplace plan details, Social Security notices, and current prescription list to any consultation.
- Reach out early if you’re dealing with ESRD, a retroactive enrollment fix, or a required Part A premium, these cases benefit most from one-on-one review.
A straight take on getting this right at 65
Cost comparisons matter, but they’re not where people get hurt. The damage almost always comes from missed deadlines: a forgotten Marketplace report, a skipped Part B enrollment, a penalty that compounds every year after. Write your dates down the moment you know them, and don’t treat a borderline case, ESRD, employer coverage, a retroactive start, as something to figure out alone. A five-minute call to Social Security or a licensed agent now is cheaper than a penalty you’ll carry for years.
— Zach
Get help comparing your options and enrolling
Figuring out your Medicare start date, your Part B timing, and whether to keep any Marketplace coverage is a lot to track alone. Personalized consultations, a free Medicare roadmap, side-by-side comparisons of Medicare Advantage and Medigap plans, as well as help with Part D and annual plan reviews, are offered to assist during enrollment and after.

To get started, visit our Medicare services page and book a consultation. Bring your Marketplace paperwork and any Social Security or Medicare notices you’ve received, it helps us give you a clear answer in one sitting instead of several follow-up calls.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
What are the downsides of using Marketplace health insurance?
Once you qualify for Medicare, Marketplace plans no longer come with financial help and can leave you paying full price while also risking overlap penalties. Marketplace plans also don’t coordinate with Medicare, so keeping both usually means duplicate premiums rather than better coverage.
Do doctors prefer Medigap or Medicare Advantage?
Provider preference varies by practice and location rather than following a fixed rule. Medigap generally offers broader provider access since it pairs with Original Medicare, while Medicare Advantage networks are narrower but often include extra benefits; comparing Medicare Advantage against Medigap for your own doctors is the more reliable approach.
Why do people say to stay away from Medicare Advantage plans?
Concerns usually center on network restrictions and the need for prior authorization for certain services, which can limit flexibility compared with Original Medicare plus Medigap. That said, Advantage plans often include lower monthly costs and added benefits, so the right fit depends on your health needs and budget.
What are the four things Medicare doesn’t cover?
Original Medicare generally doesn’t cover routine dental care, vision exams and glasses, hearing aids, or long-term custodial care. Many people fill these gaps through supplemental dental, vision, and hearing plans or by choosing a Medicare Advantage plan that bundles some of these benefits.
Sources
- Medicare & the Marketplace | Medicare
- Healthcare
- Medicare & Marketplace FAQ (CMS)
- When to sign up for Medicare | SSA
Recommended
Request a No Obligation Phone Call








Get Connected