
For most U.S. households that need income-replacement coverage, term life is the more cost-effective choice; whole life is for those who need guaranteed lifelong coverage with a cash-value component. The trade-off is straightforward: term costs less upfront but ends after a set period, while whole life costs more but never expires and builds savings you can borrow against.
TL;DR:
- The price gap for a $500,000 death benefit is typically between $30 and $60 per month for a 20-year term, versus several hundred dollars for whole life at the same coverage.
- Choosing a term length that matches your actual financial needs is critical; too short increases the risk of costly requalification, while too long leads to paying for unnecessary coverage.
- Conversion options in term policies provide flexibility to switch to permanent coverage without requalification, but deadlines vary and must be confirmed in advance.
- Whole life premiums range from three to ten times higher than term premiums, with cash value growth being slow initially and subject to dividends and surrender charges.
- The decision often hinges on your specific needs: term is best for temporary income replacement, while whole life suits lifelong dependents or estate planning goals.
Table of Contents
- Term vs. Whole Life: What Term Life Insurance Actually Covers
- Term vs. Whole Life: How Whole Life Insurance Builds Cash Value
- Term vs. Whole Life Comparison: Key Differences at a Glance
- What Does Term vs. Whole Life Insurance Actually Cost?
- Weighing the Pros and Cons of Term vs. Whole Life
- How to Decide Between Term and Whole Life Insurance
- Should You “Buy Term and Invest the Difference”?
- Hybrid Policies and Riders Worth Knowing About
- How to Compare Quotes and Vet an Insurance Company
- How Death Benefits Differ Between Term and Whole Life
- Illustrations of Whole Life Cash Value Under Different Conditions
- Common Myths About Term vs. Whole Life Insurance
- Why Term Length and Renewal Terms Matter So Much
- What Happens When You Surrender a Whole Life Policy
- Tax Treatment: Term vs. Whole Life Insurance
- A Straight Answer From Someone Who Talks to Clients About This Weekly
- Where to Verify These Numbers Yourself
- Get Personalized Help Choosing the Right Coverage
- Sources
Term vs. Whole Life: What Term Life Insurance Actually Covers
Term life insurance pays a death benefit only if you die within a specific window, usually 10, 20, or 30 years. Once that window closes, the coverage ends unless you renew it, often at a much higher rate, or convert it to a permanent policy. That structure is exactly why term is the cheaper half of the term vs whole life comparison: the insurer is only on the hook for a limited stretch of time, and most policyholders outlive their terms.
Pricing runs on three main levers: your age at purchase, your health class (nicotine use is the biggest swing factor), and how much coverage you’re buying. A healthy 35-year-old buying $500,000 of 20-year term will pay a fraction of what a 55-year-old smoker pays for the same face amount. Term life insurance typically locks in level premiums for the entire term, so your rate doesn’t creep up year to year the way some older-style policies did.
A few structural variations matter when you’re shopping:
- Level term keeps the death benefit and premium fixed for the whole term, the most common setup.
- Decreasing term shrinks the payout over time, often used to match a mortgage balance.
- Convertible term lets you switch to a permanent policy later without a new medical exam, which matters if your health changes.
- Renewable term allows you to extend coverage past the original term, usually at a steep rate increase based on your then-current age.
That conversion feature deserves attention because it’s the safety valve inside an otherwise rigid product. MoneyGeek notes that conversion riders let you preserve access to permanent coverage without requalifying medically, which is valuable insurance against the possibility that you develop a health condition mid-term and later decide you want lifelong protection.
Term vs. Whole Life: How Whole Life Insurance Builds Cash Value
Whole life insurance is permanent coverage. As long as you keep paying premiums, the policy stays in force for your entire life, and the death benefit is guaranteed rather than contingent on renewing a term. That permanence is the entire reason people pay more for it.
The mechanism that sets whole life apart is cash value. A portion of every premium payment gets set aside in an account that grows on a tax-deferred basis. You can borrow against that balance, withdraw from it, or in some cases use it to help cover premiums later in life. Forbes Advisor confirms that this cash value can be borrowed against, but any outstanding loan reduces the death benefit if it isn’t repaid.
Cash value doesn’t grow evenly. In the first decade or so, most of your premium goes toward the insurer’s costs, commissions, and building reserves for the guarantee, so the account balance grows slowly. Some mutual insurers also pay annual dividends on whole life policies, but those are non-guaranteed and can be reduced or eliminated depending on the company’s performance.
Statistic Callout: Whole-life premiums for the same death benefit can run roughly 3 to 10 times higher than term premiums, according to Fidelity, depending on your age and the specific policy.
A few mechanics to understand before signing anything:
- Cash value grows slowly in early years because premiums fund commissions and fees first.
- Loans against cash value accrue interest and reduce the death benefit if unpaid.
- Surrendering the policy early can trigger surrender charges that eat into what you get back.
- Overfunding a policy can turn it into a Modified Endowment Contract (MEC), changing how withdrawals are taxed.
Term vs. Whole Life Comparison: Key Differences at a Glance
The clearest way to see the split is side by side. Term is temporary, cheap, and simple. Whole life is permanent, expensive, and layered with financial mechanics most buyers never fully read through.
| Feature | Term Life | Whole Life |
|---|---|---|
| Coverage length | Fixed period (10 to 30 years) | Lifetime, as long as premiums are paid |
| Premiums | Level for the term, then rises sharply if renewed | Level for life, but much higher from day one |
| Cash value | None | Grows over time, tax-deferred |
| Complexity | Simple, straightforward | Complex, with loans, dividends, and surrender rules |
| Typical cost | Low | High, often 3 to 10 times term for equal coverage |
| Best fit | Income replacement during working years | Lifelong dependents, estate planning, final expenses |
That table hints at why the decision usually comes down to timeline. If you need coverage until your kids are grown and your mortgage is paid off, a fixed period of protection solves the problem. If you’re supporting a family member with lifelong needs, or you want a guaranteed payout to cover estate taxes or final expenses no matter when you die, permanent coverage matches that goal better.
A few real scenarios where the choice becomes obvious:
- A 32-year-old with two young kids and a 30-year mortgage almost always fits better with a 20 to 30-year term policy sized to replace lost income.
- A parent of an adult child with a lifelong disability may need whole life or a similar permanent policy because there’s no point at which the financial need ends.
- Someone focused on covering funeral costs and small debts in their 70s or 80s is often better served comparing final expense vs whole life coverage, which is usually a smaller, simplified version of permanent insurance.
What Does Term vs. Whole Life Insurance Actually Cost?
The price gap between these two products is the single biggest factor driving most people’s decisions, and it’s larger than most first-time buyers expect.
Representative numbers help make this concrete. Healthy adults in their 30s can often find $500,000 of 20-year term coverage for somewhere between $30 and $60 a month, according to MoneyGeek’s pricing analysis. Whole life for that same $500,000 death benefit, purchased at a similar age, frequently runs several hundred dollars a month once you account for the cash-value funding built into every payment.
Why is the gap so wide? A few reasons stack together:
- Whole life premiums fund a permanent guarantee that never expires, unlike term’s finite promise.
- A chunk of early whole-life premiums goes toward building the cash-value reserve.
- Commission structures on permanent policies tend to be front-loaded, which is part of why agents sometimes push them harder.
- Whole life pricing bakes in the insurer’s cost of guaranteeing your rate never rises, no matter how your health changes decades later.
The variables that move your specific quote are the same for both products: age, health class, nicotine use, term length (for term policies), and face amount. A 45-year-old buying coverage will pay noticeably more than a 25-year-old for identical protection, and that gap widens further if the older buyer also uses nicotine. None of these numbers are fixed across the industry. Carriers price risk differently, which is exactly why comparing multiple quotes matters more than trusting a single illustration.
Weighing the Pros and Cons of Term vs. Whole Life
Neither product wins outright. Each solves a different problem, and the honest pros-and-cons list looks like this.
Term life advantages:
- Lower cost means you can buy a larger death benefit for the same budget.
- Simple structure with no cash value mechanics to track or misunderstand.
- Convertible options exist if your needs shift later.
Term life drawbacks:
- Coverage ends when the term does, often right when renewal rates spike.
- No savings component; if you outlive the term, you get nothing back unless you bought a return-of-premium rider.
Whole life advantages:
- Coverage never expires as long as premiums are paid.
- Cash value functions as a forced savings vehicle you can borrow against.
- Premiums are locked for life, insulating you from future health-based rate hikes.
Whole life drawbacks:
- Premiums are dramatically higher for the same death benefit.
- Surrendering early usually means losing money to surrender charges.
- Agent commissions on whole life are often front-loaded, which can bias recommendations toward permanent products even when term would serve the buyer better.
If your need has a clear end date, income replacement, a mortgage, kids reaching adulthood, term almost always wins on value. If your need has no end date, a dependent who will never be financially independent, or a specific estate-planning goal, whole life’s guarantee earns its higher price.
How to Decide Between Term and Whole Life Insurance
Start with three questions before you look at a single quote.
- How long do you actually need coverage? If the answer has a number attached, “until my youngest turns 22,” “15 years until the mortgage is paid,” term is almost certainly the right shape.
- Can you comfortably afford whole-life premiums for decades without strain? If funding a permanent policy would force you to skip retirement contributions or other savings, that’s a signal you’re buying more permanence than your budget supports.
- Do you have a genuine estate or lifelong-dependency goal? Covering estate taxes, leaving a guaranteed inheritance, or supporting a dependent with lifelong needs are the scenarios where permanent coverage earns its cost.
Once you know your answer, run through this shopping checklist before buying anything:
- Confirm the face amount actually covers your income-replacement or debt-payoff math, not just a round number that sounded reasonable.
- If buying term, check the length against your actual timeline, not the cheapest option on the rate sheet.
- Ask specifically about the conversion rider and its deadline, since many convertible term policies only allow conversion up to a certain age or policy year.
- Consider a return-of-premium rider if getting money back matters to you, understanding it raises your premium meaningfully.
- Verify whether you’re working with a captive agent (tied to one carrier) or an independent agent who can compare multiple companies.
Pro Tip: If you’re within five years of a major life change, retirement, kids becoming financially independent, a mortgage payoff, buy term long enough to cover the gap rather than guessing short and needing to requalify medically later.
Should You “Buy Term and Invest the Difference”?
This is the most repeated rule of thumb in the term vs whole life comparison, and it has real logic behind it. The idea: buy the cheaper term policy, then invest whatever you would have spent on whole-life premiums instead.
MarketWatch notes that financial planners often favor this approach because expected long-term market returns tend to outpace whole-life cash-value growth over decades. On paper, the math frequently favors the investor who sticks with the plan.
That “sticks with the plan” clause is where the strategy breaks down for a lot of people:
- It requires real investment discipline. Money that isn’t automatically funneled into a policy is money that can get spent instead.
- Market risk is real. Unlike a whole life guarantee, invested money can lose value, especially in a bad stretch right when you need it.
- It gives up the guarantees whole life provides, no cash value to borrow against in an emergency, no lifelong death benefit.
The approach works best for disciplined savers with employer-sponsored retirement accounts already maxed appropriately and the temperament to leave invested money alone. It works poorly for anyone who has historically struggled to save consistently without a forced structure.
Hybrid Policies and Riders Worth Knowing About
Term and whole life aren’t the only two options on the shelf. A few middle-ground products solve specific problems neither pure version handles well.
- Universal life offers permanent coverage with flexible premiums, letting you adjust payments within limits as your finances change.
- Guaranteed universal life trades away most cash-value growth for a permanent death benefit at a lower cost than traditional whole life, popular for people who want lifelong coverage mainly for estate or final-expense purposes.
- Return-of-premium term refunds your premiums if you outlive the term, at a meaningfully higher monthly cost than standard term.
- Accelerated death benefit riders let you access part of the death benefit early if diagnosed with a terminal illness.
Investigate these when your needs sit between the two extremes, permanent coverage on a budget, or temporary coverage with a refund guarantee attached.
How to Compare Quotes and Vet an Insurance Company
Shopping for either policy type means comparing quotes from a few sources: directly from an insurer, through an independent agent who represents multiple carriers, or through a broker. Independent agents generally give you a wider view of pricing since they aren’t limited to one company’s rate sheet.
When quotes come in, ask pointed questions: What are the exact conversion rights and deadlines on this term policy? What’s the surrender charge schedule on this whole life policy, and how long until it phases out? Are dividends guaranteed or projected? What fees are baked into the illustration?
Before signing anything, verify the company itself. AARP points out that agent commissions on permanent policies are often front-loaded, so independent comparison shopping helps counter any bias toward the product that pays the agent more.
- Check insurer licensing and complaint history through the National Association of Insurance Commissioners (NAIC) or your state insurance department.
- Confirm whether your agent is captive (one carrier) or independent (multiple carriers).
- Get every quote in writing with the same face amount and term length across companies.
Pro Tip: A quote that looks unusually cheap compared to others often has a catch, either a shorter guarantee period or a rate that jumps after an initial teaser phase. Always ask what happens to the price after year one.
How Death Benefits Differ Between Term and Whole Life
Both products pay a death benefit, but the structure behind that payout works differently and carries different guarantees.
Term life’s death benefit is conditional on timing. If you die during the term, your beneficiaries get the full face amount, paid as a lump sum, generally free of federal income tax under long-standing tax rules. If you die one day after the term ends without renewing or converting, there’s no payout at all. That binary outcome is the core trade-off buyers accept for the lower price.
Whole life’s death benefit is unconditional as long as premiums stay current. There’s no expiration date to worry about, which is precisely why it costs more. Some whole life policies also let the death benefit grow over time through dividend accumulation, though that growth is never guaranteed and depends on the insurer’s performance.
One nuance worth knowing: if you’ve taken loans against a whole life policy’s cash value and haven’t repaid them, the outstanding balance plus accrued interest gets subtracted from the death benefit before your beneficiaries receive anything. A policy illustration showing a $500,000 death benefit can pay out considerably less if loans were outstanding at death. Term policies don’t have this complication since there’s no cash value to borrow against in the first place.
Illustrations of Whole Life Cash Value Under Different Conditions
Insurance illustrations show projected cash-value growth, and they come in two flavors: guaranteed and non-guaranteed. The guaranteed column reflects the minimum the insurer is contractually obligated to credit. The non-guaranteed column includes projected dividends, which assume favorable company performance that isn’t promised.
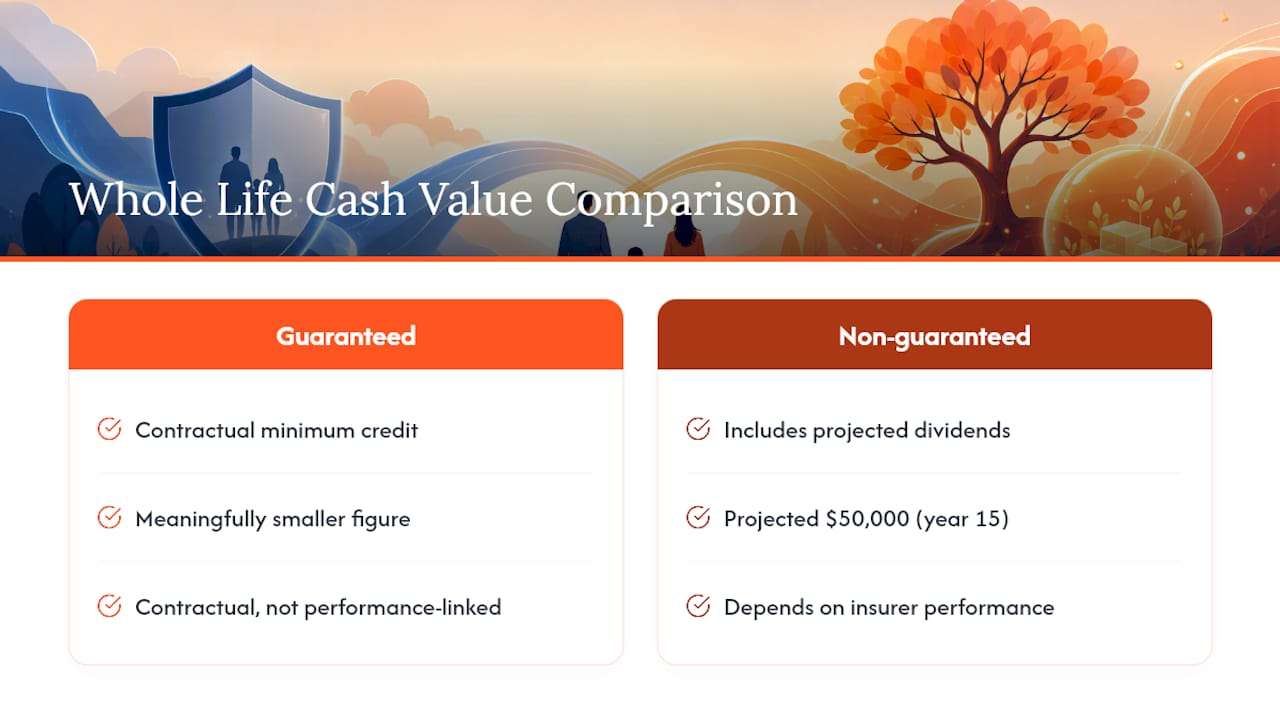
That gap between the two columns can be significant. A whole life illustration might project a cash value of $50,000 in year 15 under the non-guaranteed assumptions, while the guaranteed column for that same year might show a meaningfully smaller figure. Dividend performance depends on the insurer’s investment returns, mortality experience, and expenses, none of which are locked in when you buy the policy.
This matters because agents sometimes present the non-guaranteed projection as the expected outcome rather than a best-case scenario. Ask specifically for the guaranteed-column numbers and treat those as your baseline. If the policy still makes sense using only the guaranteed figures, you’re on solid ground. If it only looks attractive under optimistic dividend assumptions, you’re taking on more risk than the “guaranteed” branding suggests.
Term policies don’t need this kind of illustration because there’s nothing to project. Your death benefit and premium are fixed for the term, full stop. That simplicity is part of why term remains easier to shop and compare across companies.
Common Myths About Term vs. Whole Life Insurance
A few persistent myths distort this decision more than almost any other personal-finance topic.
Myth: Whole life is always a bad investment. Whole life isn’t designed as an investment vehicle in the way a brokerage account is. Its cash-value growth is modest by design because the priority is the guarantee, not returns. Judging it purely against stock-market performance misses what it’s actually built to do.
Myth: Term insurance is wasted money if you don’t die. Comparing it to renters insurance is more useful. You’re paying for protection during a specific risk window, not buying an investment. “Wasted” if nothing happens is the wrong lens entirely.
Myth: You need whole life for “real” lifelong security. For most people, the actual lifelong risk, dying with dependents who need income replacement, ends at a predictable point: retirement, an empty nest, a paid-off mortgage. Term matched to that timeline solves the real problem for a fraction of the cost.
Myth: Converting term to whole life is always available and free. Conversion riders have deadlines and specific terms. Some expire well before the term itself ends. Always confirm the exact conversion window in writing rather than assuming it exists indefinitely.
Why Term Length and Renewal Terms Matter So Much
The length you choose isn’t a minor detail. It’s arguably the single most consequential decision in a term policy, more important than shaving a few dollars off the monthly premium.
Pick too short a term, and you risk needing to requalify medically for new coverage at an older age, potentially with a health condition that didn’t exist when you first bought the policy. Pick too long, and you may pay for years of coverage you no longer need once your kids are financially independent or your mortgage is paid off.
Renewal terms are the trap many buyers don’t see coming. Most term policies include an annual renewable option after the level term ends, but that renewal rate is based on your age at the time of renewal and typically jumps dramatically, sometimes to a multiple of what you were paying during the level period. A policy that cost $40 a month during a 20-year level term might cost several hundred dollars a month if renewed annually afterward.
The fix is straightforward: size the term length to your actual need from the start, adding a modest cushion rather than guessing short. If you’re 35 and need coverage until your youngest child turns 25, a 20-year term gets you to 55, not quite far enough if you want a buffer. A 25 or 30-year term, even at a slightly higher monthly cost, avoids the renewal cliff entirely.
What Happens When You Surrender a Whole Life Policy
Canceling a whole life policy, called surrendering it, triggers a specific process with financial consequences that catch a lot of policyholders off guard.
When you surrender, the insurer pays out your policy’s cash surrender value: the accumulated cash value minus any outstanding loans and minus a surrender charge. That charge is highest in the early policy years and phases down over roughly 10 to 15 years, according to Forbes Advisor’s breakdown of how surrender schedules typically work. Surrender in year three of a policy, and you might forfeit a substantial chunk of your accumulated cash value to that charge.
There’s also a tax wrinkle. If your cash surrender value exceeds the total premiums you’ve paid into the policy, that gain is taxable as ordinary income. Most people don’t hit this threshold in early years, but long-term policyholders with substantial dividend accumulation sometimes do.
Beyond the financial mechanics, surrendering means losing the death benefit entirely. If your original reason for buying the policy, a dependent’s lifelong needs, an estate goal, still exists, surrendering solves a short-term cash need while creating a longer-term coverage gap. Before surrendering, ask the insurer about alternatives: a policy loan, a reduced paid-up option that lowers the death benefit but keeps some coverage in force, or a partial withdrawal that doesn’t terminate the policy entirely.
Tax Treatment: Term vs. Whole Life Insurance
Tax treatment is one area where these two products overlap more than people expect, but the details diverge once cash value enters the picture.
Death benefits from both term and whole life policies are generally received income tax free by beneficiaries, a long-standing feature of life insurance under federal tax law. That part of the equation is identical for both types.
Where they split is the cash value. Whole life’s cash-value growth accumulates tax-deferred, meaning you don’t owe taxes on the growth each year the way you might with a taxable brokerage account. Policy loans against cash value are typically not taxed as income, since they’re structured as loans rather than withdrawals, as long as the policy stays in force. Withdrawals up to your cost basis (the total premiums you’ve paid) are also generally tax free, but withdrawals beyond that basis are taxed as ordinary income.
One risk zone: if a policy is overfunded beyond IRS limits, it can be reclassified as a Modified Endowment Contract, or MEC. Once that happens, loans and withdrawals lose their favorable tax treatment and get taxed as income first, with a possible penalty if taken before age 59 and a half. This is a narrow scenario mostly relevant to people funding permanent policies aggressively for cash-value accumulation, but it’s worth confirming with your insurer if you’re putting more than the minimum into a whole life policy.
Term policies avoid all of this complexity simply because there’s no cash value to tax. Premiums aren’t deductible for either policy type when purchased for personal reasons, and that rule applies equally across the board.
A Straight Answer From Someone Who Talks to Clients About This Weekly
The biggest mistake I see isn’t picking the wrong product. It’s picking the right product for the wrong reason. People buy whole life because an agent framed it as “coverage that never wastes your money,” without ever laying out what the same premium buys in term coverage plus real savings. And people buy bargain-basement term without checking whether the conversion window even exists past year ten.
Here’s what the research keeps pointing back to: term matched to a real timeline beats a permanent policy bought on vague anxiety about “what if I need it later.” But whole life earns its cost when the need genuinely has no end date, a dependent who will always need support, or a specific estate goal that requires certainty. The mistake is treating this as an ideology instead of a math problem tied to your actual life.
If you’re weighing this alongside Medicare or retirement planning, the calculus shifts again, which is where a licensed conversation beats another spreadsheet.
— Zach
Where to Verify These Numbers Yourself
Don’t take pricing or rule claims at face value from any single source, including this one. The National Association of Insurance Commissioners lets you confirm a carrier’s licensing status and review its complaint record before you sign anything. For deeper cost breakdowns and calculators, AARP’s guide to term vs. whole life, Forbes Advisor’s comparison, and Fidelity’s learning center each walk through the mechanics in more technical detail. Your state insurance department’s website is also worth bookmarking for filing complaints or checking agent licenses directly.
Get Personalized Help Choosing the Right Coverage
Reading about term vs whole life gets you most of the way there, but the last stretch, matching a specific policy to your specific age, health, and family situation, benefits from a real conversation. This agency builds its practice around exactly that kind of personalized guidance, walking clients through options instead of pushing a single product.

While Safeguardbenefitservices is best known locally in Charlotte for Medicare Advantage plans and Medicare Supplement coverage for people nearing or past 65, the same principle applies across every insurance decision the agency helps with: understand your actual timeline and budget before committing to a product that could cost you thousands more than necessary over its lifetime. If you’re approaching Medicare eligibility and want to make sure your broader coverage picture, including how Medicare Advantage compares to Medigap, fits together with your life insurance decisions, a free consultation with a licensed agent can clarify your options without any pressure to buy on the spot. Reach out to the agency to get a personalized Medicare roadmap and ask your specific coverage questions before you make any final decisions.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Term vs. Whole Life Insurance and How to Choose — AARP
- Term Life vs. Whole Life Insurance — Forbes Advisor
- Term life vs. whole life insurance — Fidelity
- Benefits of term life insurance — MoneyGeek
- Benefits of term life insurance — MarketWatch
Recommended
Request a No Obligation Phone Call








Get Connected