
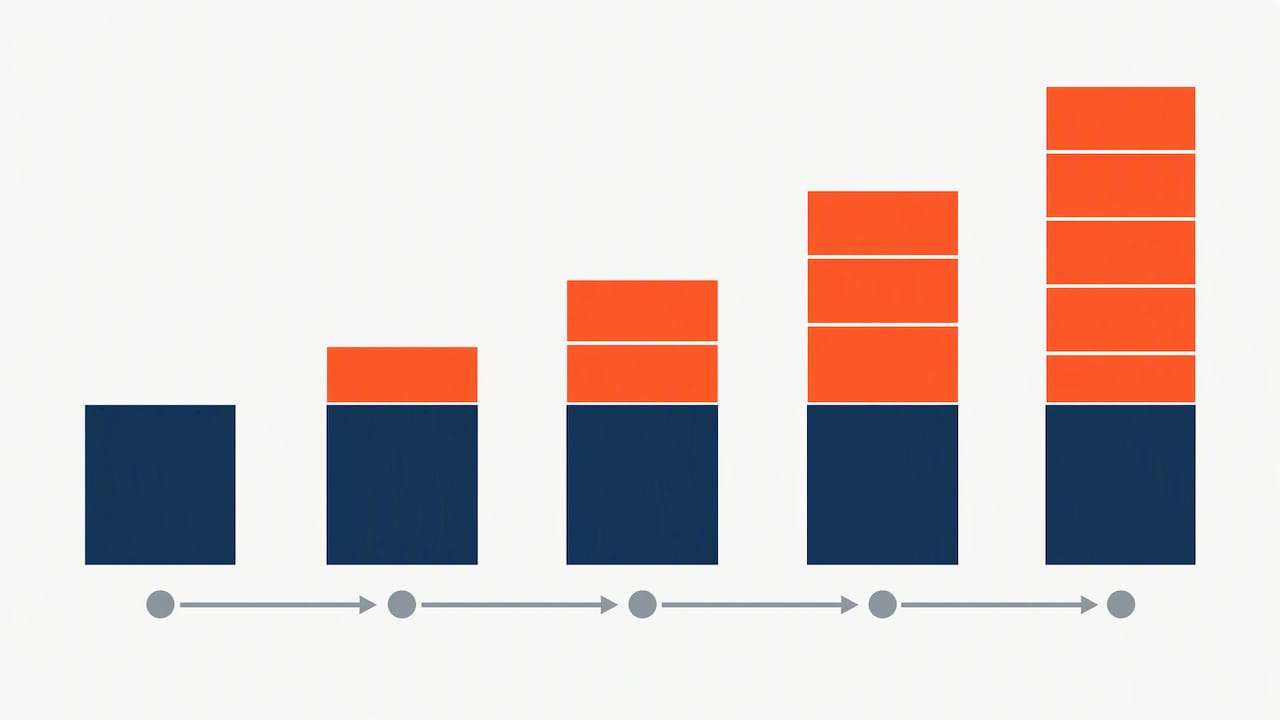
You can have VA care and Medicare Advantage at the same time, but they work in different places and bill differently. VA care happens at VA facilities, while a Medicare Advantage plan covers non-VA providers in its network and usually won’t pay for VA care. Skip Part B and you risk a lifelong penalty: a two-year delay pushes the 2026 premium to $243.50.
TL;DR:
- Medicare adds a lifetime Part B penalty of 10% for every full 12 months of delay; the 2026 standard premium is $202.90.
- VA pharmacy coverage generally counts as creditable for Part D, so veterans who keep it typically avoid the drug coverage late enrollment penalty.
- Medicare Advantage plans generally do not pay for VA facility care; confirm local specialists, hospitals, pharmacies, referrals, and prior authorization rules before enrolling.
- For specialty care unavailable locally, ask the VA to authorize community care; for emergencies outside VA, seek care first and check plan coverage afterward.
- Before choosing Medicare Advantage, compare annual costs, including Part B premiums, plan premiums, and expected cost sharing, with local network access and benefits.
Table of Contents
- How do VA, Original Medicare, and Medicare Advantage compare?
- How do VA and Medicare work together in real life?
- What should you evaluate in a Medicare Advantage plan?
- What do late enrollment penalties cost veterans?
- How do you decide between VA-only care and adding Medicare Advantage?
- What should you do next?
- What do I tell veterans about keeping Part B?
- How can we help you compare plans and avoid mistakes?
- FAQ
- Sources
How do VA, Original Medicare, and Medicare Advantage compare?
Think of the three options by where you get care, who pays, and how drugs are covered.
- VA health care: You get care at VA facilities and some VA-authorized community care. Costs for service-connected conditions may vary, and VA does not bill Medicare for care it provides.
- Original Medicare (Parts A and B): You can see any provider who accepts Medicare. You need a separate Part D plan for drugs, and many people add a Medigap plan to keep out-of-pocket costs predictable.
- Medicare Advantage (Part C): These are private plans with provider networks. Many bundle drug coverage and add dental, vision and hearing, but they usually do not pay for care at VA facilities.
The practical takeaway: VA and Medicare are not rivals. They are two doors to care, and you choose one each time you need a service.
How do VA and Medicare work together in real life?
VA’s own guidance says you can use VA benefits alongside Medicare and decide which to use at the time of care. In fact, VA encourages eligible veterans to sign up for Medicare so they have options if they need to care outside the VA, or if VA funding or access changes. VA does not bill Medicare or Medicaid for care it provides, though it may bill a Medicare supplemental insurer for some services.
Here is how it plays out:
- Routine or service-connected care at the VA: Use your VA benefits. Medicare is not billed, and a Medicare Advantage plan will not pay for it.
- Emergency outside the VA: Seek immediate emergency care. Check with Medicare or your Medicare Advantage plan about how care may be covered.
- Specialty care the local VA can’t provide: Ask the VA whether it can authorize community care. If it cannot, check with Medicare or your plan about coverage and network rules.
- Prescriptions: Compare the VA pharmacy benefits available to you with the pharmacies covered by a Medicare drug plan.
- Appointments: Bring your Medicare card to VA visits, since VA may need it to coordinate billing with a supplemental insurer.
What should you evaluate in a Medicare Advantage plan?
Medicare Advantage plans are Medicare-approved private plans that bundle Part A, Part B and usually Part D. According to Medicare’s guide to new coverage, they commonly use networks, may require referrals or prior authorization, and can add vision, hearing and dental benefits that Original Medicare does not include. Going out of network can raise your costs. We cover the dental, vision and hearing side in detail in our guide on whether Medicare Advantage plans cover those benefits.
Weigh these points:
- Networks: Check that your preferred specialists and local hospital are in the plan’s network.
- Extra benefits: Dental, vision and hearing can matter if the VA isn’t close by.
- Pharmacy rules: Look at which pharmacies and drugs the plan covers.
- Payment policy: Researchers have documented rising dual enrollment and concerns about duplicative federal spending. A VA research brief notes that proposed legislation would let VA bill Medicare Advantage insurers for care given to dual enrollees.
As of 2025, over 1 in 3 veterans are enrolled in Medicare Advantage. Many veterans are already using both systems, so you are not an outlier. Just remember that these plans do not pay for care at VA facilities.
CMS has said it expects Medicare Advantage and Part D options to remain stable in 2026, so plan choices should stay broad.
What do late enrollment penalties cost veterans?
Using the VA does not excuse you from Medicare Part B. Medicare charges a 10% penalty on the standard Part B premium for each full 12-month period you were eligible but didn’t enroll. In 2026 the standard premium is $202.90.
Drug coverage works differently. VA health care counts as creditable coverage for Part D, so veterans who keep VA pharmacy benefits typically avoid the Part D penalty. The VA’s 2026 benefits overview also cautions against canceling Part B without understanding the penalty and re-enrollment rules.
Know your windows for joining or switching, per Medicare’s plan enrollment rules:
- Initial Enrollment Period: Your first chance when you become eligible.
- General Enrollment Period: January 1 to March 31.
- Open Enrollment: October 15 to December 7, for joining or changing a plan.
- Medicare Advantage Open Enrollment Period: January 1 to March 31, with limits on what you can change.
- Special Enrollment Periods: Available after certain qualifying events.
Pro Tip: Estimate your exposure before you decide. Learn more about Medicare enrollment penalties here.
How do you decide between VA-only care and adding Medicare Advantage?
Work through these questions in order:
- Do you need non-VA specialists nearby? If the closest VA is a long drive, a plan with a strong local network may matter.
- Do you want dental, vision and hearing included? Many plans add these benefits. Check which services your VA coverage and any plan include.
- Do you need a local pharmacy? Compare that with VA mail order.
- Which providers are in network, and what needs prior authorization? Confirm before you enroll, not after.
- What will you pay in a year? Add your Part B premium, any plan premium and expected cost-sharing.
Before you decide, call your local SHIP counselor, your VA benefits office or a Medicare agent and ask: Is my VA drug coverage creditable? Will this plan help cover my Part B premium? Does it include my specialists and local hospital?
Pro Tip: Keep Medicare in place as a federal backup. VA funding and authorization rules can change, and Medicare gives you coverage options that don’t depend on them.
If you want a deeper look at how plan types differ, our explainer on Medicare Advantage versus Medigap covers the tradeoffs. Dental needs are a common reason veterans add outside coverage, and a dental practice’s overview of insurance alternatives is a useful read.
What should you do next?
Move from deciding to acting with this list:
- Check your Part A and Part B enrollment options if you’re unsure, so you can understand any potential penalties.
- Confirm your VA drug coverage is creditable for Part D before relying on it.
- Bring your Medicare card to your next VA appointment.
- Enroll through Medicare.gov or get free counseling from your local SHIP, and note your effective date.
- Keep your records: enrollment dates, proof of creditable drug coverage and notes on any VA community care authorizations.
For veterans in our area, we also outline local options in Medicare insurance help for veterans in Charlotte.
What do I tell veterans about keeping Part B?
In most cases, keep Part B. The lifetime penalty can be costly. Check whether you have qualifying employer coverage before deciding whether to keep Part B, and VA itself recommends keeping Medicare for flexibility. Consider Medicare Advantage only when the local network and extra benefits match how you actually use care. Our agents go through a comprehensive training program, and we offer a free Medicare roadmap that lays out your options and eligibility before you commit to anything.
— Zach
How can we help you compare plans and avoid mistakes?

Comparing VA coverage with Medicare Advantage is easier with someone who does it every day. We help you avoid penalties and pick a plan that fits how you use care:
- A personalized consultation on Medicare Advantage versus Medigap
- Help confirming whether your VA drug coverage is creditable
- Enrollment assistance and annual plan reviews
Request your free Medicare roadmap or a consultation at Safeguard Benefit Services, and we’ll check your penalty exposure and compare local networks with you.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
FAQ
Are VA benefits better than Medicare?
Neither is better across the board, because they cover different places. VA care is low cost at VA facilities, while Medicare opens doors to non-VA providers. VA encourages eligible veterans to enroll in Medicare for that flexibility.
Why do people say not to get a Medicare Advantage plan?
The main concern is that these plans use networks and usually don’t pay for care at VA facilities. Researchers have also flagged duplicative federal spending when veterans use both systems. For many veterans, the right fit depends on local providers and extra benefits.
Which Medicare plan is best for veterans?
It depends on how you use care. Veterans who want broad provider access often pair Original Medicare with a drug plan and Medigap, while those who value bundled dental, vision and hearing may prefer Medicare Advantage.
Do I have to pay for Medicare if I use the VA?
Yes, if you keep Part B you pay its premium, because VA does not pay Medicare premiums and Medicare does not pay for care at VA facilities. Dropping Part B can trigger a lifetime penalty if you re-enroll later.
Sources
- VA Health Care And Other Insurance | Veterans Affairs
- Avoid late enrollment penalties | Medicare
- Brown
Recommended
Request a No Obligation Phone Call








Get Connected