
Missing a Medicare window can affect when coverage starts, what plans you can choose, and whether late-enrollment penalties apply. This guide to Charlotte Medicare enrollment deadlines 2026 2027 gives retirees, people approaching 65, and caregivers a practical calendar for Initial Enrollment, General Enrollment, Medicare Advantage Open Enrollment, Annual Election Period, and Special Enrollment Periods.
What are the Charlotte Medicare enrollment deadlines 2026 2027 retirees should put on the calendar?
Medicare enrollment is not one single deadline. It is a set of windows, each with different rules depending on whether you are new to Medicare, changing Medicare Advantage plans, adding prescription drug coverage, or correcting a missed Part B enrollment.
For residents in Charlotte and nearby communities such as Matthews, Huntersville, Mint Hill, Pineville, and Concord, the national Medicare dates are the same as they are across the United States. The local challenge is making sure your doctors, hospitals, pharmacies, and prescriptions fit the plan you select before the deadline arrives.
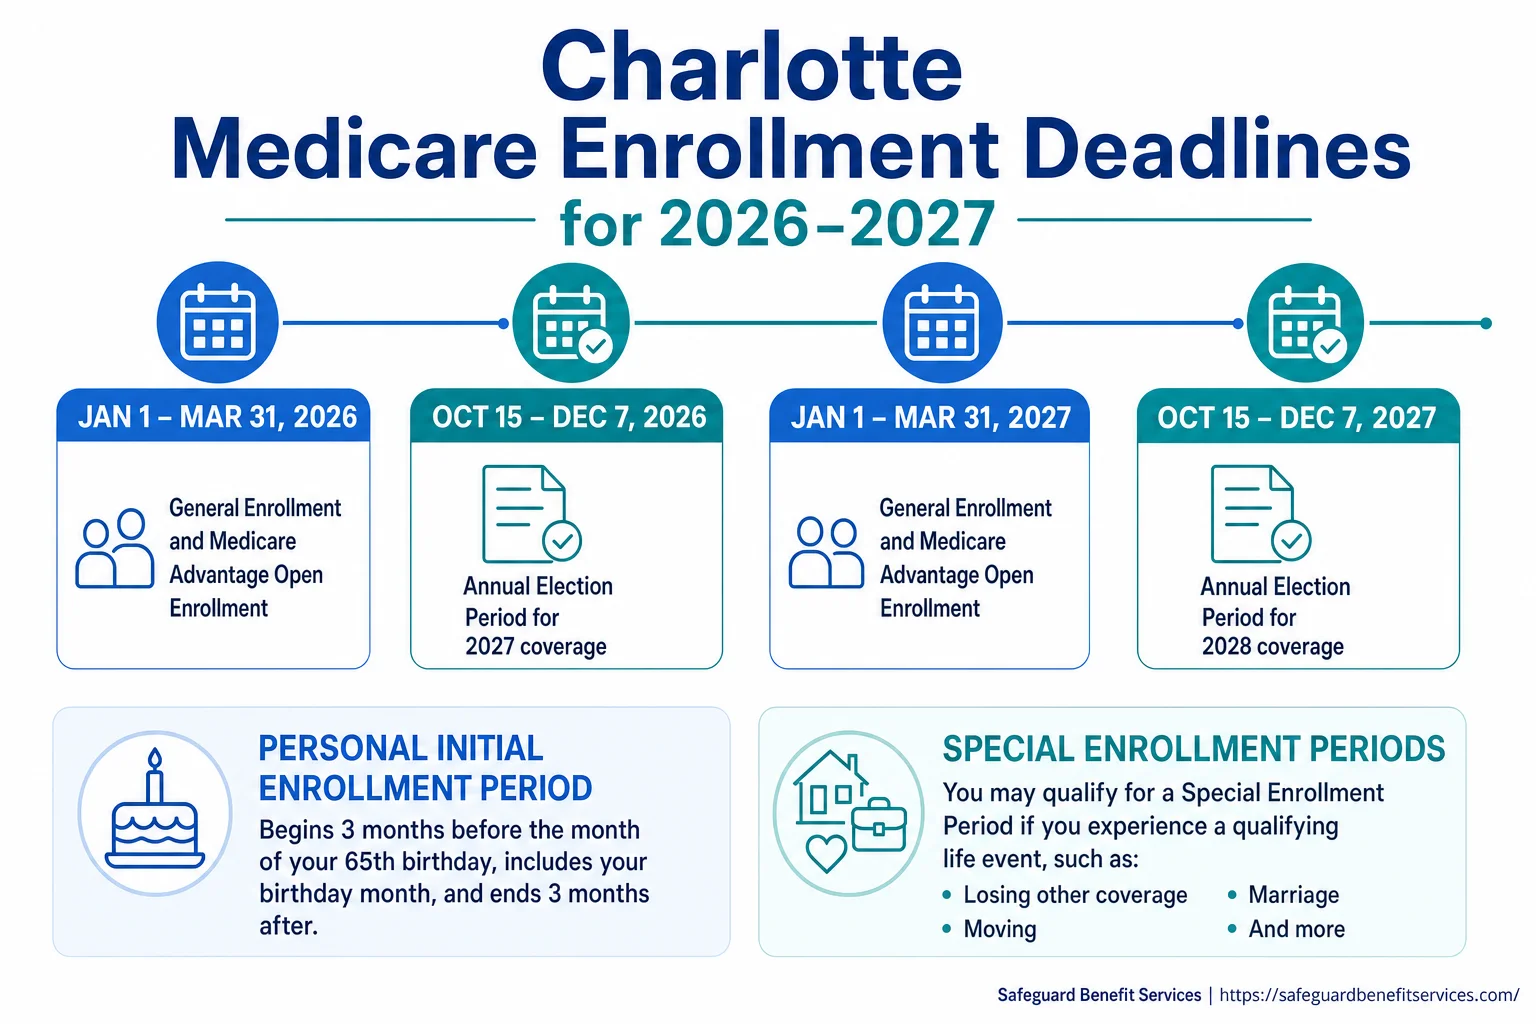
- Initial Enrollment Period: Your personal seven-month window around your 65th birthday.
- Annual Election Period: October 15 to December 7 each year for Medicare Advantage and Part D changes.
- Medicare Advantage Open Enrollment Period: January 1 to March 31 each year for people already in a Medicare Advantage plan.
- General Enrollment Period: January 1 to March 31 each year for certain people who missed Medicare Part A and/or Part B enrollment.
- Special Enrollment Periods: Available after qualifying life events, such as losing employer coverage or moving out of a plan’s service area.
According to Medicare.gov, the official U.S. government Medicare website, plan enrollment requests for the Annual Election Period must be received by December 7, and coverage generally begins January 1 of the following year.
When is your Initial Enrollment Period if you turn 65 in 2026 or 2027?
Your Initial Enrollment Period is usually the first Medicare deadline that matters. It lasts seven months: the three months before the month you turn 65, your birthday month, and the three months after your birthday month.
For example, if you turn 65 in June 2026, your Initial Enrollment Period runs from March 1 through September 30, 2026. If you turn 65 in February 2027 and your birthday is not on February 1, it runs from November 1, 2026 through May 31, 2027; if your birthday is February 1, 2027, it runs from October 1, 2026 through April 30, 2027.
The Social Security Administration handles enrollment in Original Medicare Part A and Part B for most people. Medicare.gov explains that if you sign up before the month you turn 65, coverage generally starts the first day of your birthday month; if your birthday is on the first day of the month, coverage can start the first day of the prior month.
This window is also when many people first compare whether to stay with Original Medicare, add a standalone Part D prescription drug plan, consider Medicare Supplement Insurance, or enroll in a Medicare Advantage plan. In practice, licensed Medicare agents often start reviewing options with clients about three to six months before the 65th birthday month, especially if employer coverage or Health Savings Account contributions are involved.
How do Charlotte Medicare enrollment deadlines 2026 2027 affect Annual Election Period choices?
The Annual Election Period, often called Medicare Open Enrollment, runs from October 15 through December 7 every year. The 2026 Annual Election Period runs from October 15 to December 7, 2026, and changes made during this window generally take effect January 1, 2027.
During this period, Medicare beneficiaries may be able to:
- Switch from Original Medicare to a Medicare Advantage plan.
- Switch from one Medicare Advantage plan to another Medicare Advantage plan.
- Leave a Medicare Advantage plan and return to Original Medicare.
- Join, switch, or drop a standalone Medicare Part D prescription drug plan.
The 2027 Annual Election Period runs from October 15 to December 7, 2027, for coverage that generally begins January 1, 2028. If you are comparing 2027 plans in Charlotte, this is the time to review your Annual Notice of Change, prescription formulary, provider network, pharmacy network, premiums, copays, and maximum out-of-pocket limit.
Medicare.gov and the Centers for Medicare & Medicaid Services note that Medicare Advantage and Part D plans can change costs, covered drugs, pharmacy contracts, provider networks, and benefits each year. That is why a plan that worked well in 2026 may not be the best fit for 2027.
Can you use Medicare Advantage Open Enrollment in early 2027?
The Medicare Advantage Open Enrollment Period runs from January 1 through March 31 each year. This window is only for people who are already enrolled in a Medicare Advantage plan on January 1.
From January 1 to March 31, 2027, a Medicare Advantage enrollee can generally switch to a different Medicare Advantage plan or leave Medicare Advantage and return to Original Medicare. If returning to Original Medicare, the person may also be able to join a standalone Part D prescription drug plan.
This period does not allow everyone to make every type of change. For example, someone with Original Medicare and a standalone Part D plan cannot use Medicare Advantage Open Enrollment simply to change Part D plans; that change usually belongs in the October 15 to December 7 Annual Election Period unless a Special Enrollment Period applies.
A practical Charlotte example is a retiree who joined a Medicare Advantage HMO for 2027 and then discovers in January that a preferred specialist is not in network. If the enrollee is eligible to use Medicare Advantage Open Enrollment, switching to a different Medicare Advantage plan or returning to Original Medicare may be possible before March 31.
When does the General Enrollment Period help if you missed Medicare Part B?
The General Enrollment Period runs from January 1 through March 31 each year. It is mainly for people who did not enroll in Medicare Part A and/or Part B when first eligible and who do not qualify for a Special Enrollment Period.
For 2027, the General Enrollment Period runs from January 1 to March 31, 2027. According to Medicare.gov, coverage generally starts the first day of the month after you sign up during the General Enrollment Period.
This can be important for people who delayed Medicare because they thought retiree coverage, COBRA, an individual health plan, or marketplace coverage counted the same as active employer group health coverage. In many cases, it does not protect you from Medicare late-enrollment consequences in the same way current employment-based coverage can.
Part B late-enrollment penalties may apply if you go without Part B and do not have qualifying coverage. Medicare.gov states that the Part B late-enrollment penalty can increase your premium by 10% for each full 12-month period you could have had Part B but did not sign up, and in most cases you pay the penalty for as long as you have Part B.
Which Special Enrollment Period triggers matter for Charlotte retirees and caregivers?
Special Enrollment Periods allow Medicare changes outside the standard calendar when a qualifying event occurs. The rules depend on the event, the type of coverage, and how soon action is taken.
Common Special Enrollment Period triggers include:
- Losing employer or union coverage based on current employment.
- Moving to a new address outside a Medicare Advantage or Part D plan’s service area.
- Moving into, living in, or moving out of a skilled nursing facility or certain long-term care institutions.
- Gaining, losing, or having changes to Medicaid eligibility.
- Gaining or losing eligibility for Extra Help with Medicare prescription drug costs.
- Losing creditable prescription drug coverage.
- A Medicare plan ending its contract or changing service areas.
For workers leaving a job in the Charlotte area, one of the most important rules involves Medicare Part B. Medicare.gov explains that if you are covered by a group health plan based on current employment, you may be able to sign up for Part B during employment or within an eight-month Special Enrollment Period after employment or the group health coverage ends, whichever happens first.
Prescription drug coverage has separate timing concerns. Medicare.gov explains that people who go without creditable prescription drug coverage for 63 days or more after becoming eligible may face a Part D late-enrollment penalty if they later enroll in Medicare drug coverage.
Caregivers should be especially cautious when a parent moves from another county or state to be closer to family. A move from outside North Carolina into Mecklenburg County can change plan availability, provider networks, and pharmacy access, even when the Medicare card itself stays the same.
How should caregivers organize documents before a Medicare deadline?
Caregivers often step in when a parent receives multiple plan notices, medical bills, or prescription changes. A simple document checklist can prevent rushed decisions near the December 7 deadline or during a Special Enrollment Period.
Before comparing plans, gather:
- Medicare card showing Part A and Part B effective dates.
- Current Medicare Advantage, Part D, or Medicare Supplement card.
- Annual Notice of Change from the current plan, if applicable.
- List of doctors, specialists, hospitals, and preferred pharmacies.
- Complete prescription list with dosage, frequency, and preferred pharmacy.
- Information about employer, retiree, union, VA, TRICARE, Medicaid, or marketplace coverage.
- Power of attorney or authorization documents if the caregiver will speak on the beneficiary’s behalf.
For Medicare Advantage comparisons, provider network verification is not optional. HMO and PPO plans work differently, and a preferred doctor being “nearby” does not necessarily mean the doctor is in network for a specific plan year.
For Part D comparisons, the prescription formulary matters just as much as the premium. A low-premium plan may cost more overall if a medication is placed on a higher tier, requires prior authorization, or is not covered at a preferred local pharmacy.
Where can you get reliable Medicare enrollment information in North Carolina?
Official sources are the best place to confirm rules and deadlines. Medicare.gov provides federal enrollment rules, plan comparison tools, and official publications such as the Medicare & You handbook.
The Social Security Administration handles many Medicare Part A and Part B enrollments, while the Centers for Medicare & Medicaid Services oversees Medicare program rules and plan standards. In North Carolina, the North Carolina Department of Insurance Seniors’ Health Insurance Information Program, known as SHIIP, offers Medicare counseling and educational resources.
Independent local guidance can also help when the question is not just “What is the deadline?” but “Which plan fits my doctors, prescriptions, budget, and travel habits?” Safeguard Benefit Services works with North Carolina Medicare consumers as an independent insurance and employee benefits agency, helping clients compare plan options without assuming one carrier or plan type is right for everyone.
How can you avoid last-minute mistakes before the 2026 and 2027 Medicare deadlines?
The safest approach is to review Medicare coverage before the busiest enrollment weeks. In a typical agency workflow, advisors verify Medicare effective dates first, then review prescriptions, pharmacies, doctors, plan networks, and total estimated annual costs.
Use these timing guidelines for the Charlotte Medicare enrollment deadlines 2026 2027:
- Start Initial Enrollment planning at least three months before your 65th birthday month.
- Review Annual Notice of Change documents as soon as they arrive in the fall.
- Compare Medicare Advantage and Part D options before Thanksgiving, not on December 7.
- Confirm doctor and hospital network status for the exact plan year you are selecting.
- Check every prescription against the plan’s formulary and pharmacy pricing.
- Ask about Special Enrollment Period eligibility before assuming you must wait until fall.
For retirees and caregivers in Charlotte, Medicare decisions often involve more than the national calendar. Local hospital systems, specialist access, preferred pharmacies, and county-level plan availability can all influence which option is practical for day-to-day care.
If you are unsure which Medicare deadline applies to your situation, Safeguard Benefit Services can help you review your enrollment window, compare Medicare Advantage and prescription drug options, and understand how HMO, PPO, Part D, and Special Needs Plan choices may affect your care in North Carolina. Visit Safeguard Benefit Services at / to request local, consultative guidance before your next Medicare deadline.
This article is for informational purposes only and does not constitute financial advice. Consult a qualified professional for your specific situation.








Get Connected