
Missing a Medicare enrollment deadline at 65 does not just mean a paperwork headache. It can mean a permanent penalty added to your monthly premium for the rest of your life. For North Carolina residents approaching 65, the window to act is both specific and unforgiving. This complete Medicare enrollment checklist walks you through every step, from the moment your enrollment window opens to the day your coverage begins. If you live in the Charlotte area and want someone to walk through this with you directly, Safeguard Benefit Services offers free, no-pressure consultations with licensed advisors who specialize in exactly this transition.
Table of Contents
- Quick Takeaways
- When Your Medicare Enrollment Window Opens
- The Four Parts of Medicare, Explained Simply
- Your Step-by-Step Medicare Enrollment Checklist
- Medicare Advantage vs. Medicare Supplement in North Carolina
- Late Enrollment Penalties: What North Carolina Residents Must Know
- Working Past 65: What Changes for Your Enrollment
- North Carolina Resources That Can Help
- Frequently Asked Questions
- References
Quick Takeaways
Key Insight | Explanation |
|---|---|
Your enrollment window is 7 months total | It opens 3 months before your 65th birthday month, includes your birthday month, and extends 3 months after. Missing it triggers lifelong penalties. |
Part B is not automatic for everyone | If you are not already collecting Social Security benefits, you must actively enroll in Part B. Many North Carolinians miss this and face a gap in coverage. |
Part D has its own separate penalty | Going 63 or more days without creditable drug coverage after your Initial Enrollment Period ends triggers a permanent Part D late enrollment penalty. |
Medigap open enrollment is a one-time event | The 6-month window after you enroll in Part B is your best opportunity to buy any Medicare Supplement plan without medical underwriting. It does not repeat. |
North Carolina has 30+ plan options | Working with an independent agency like Safeguard Benefit Services gives you access to plans from multiple carriers, not just one company’s options. |
Employer coverage may let you delay without penalty | If you or a spouse have active employer group coverage, you may qualify for a Special Enrollment Period that lets you delay Medicare without triggering penalties. |
Annual Enrollment Period runs October 15 to December 7 | Each fall, North Carolina Medicare beneficiaries can switch, drop, or add Medicare Advantage and Part D plans for the following calendar year. |
When Your Medicare Enrollment Window Opens
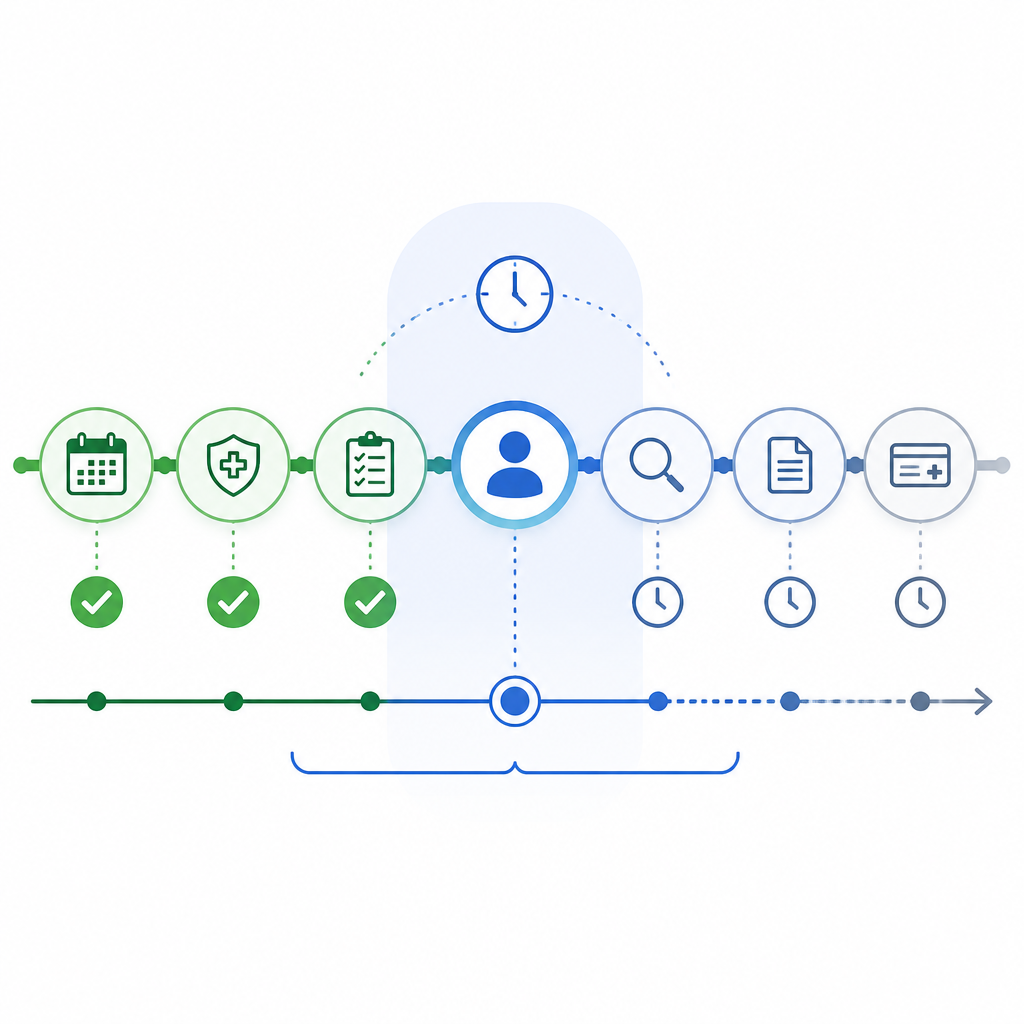
Your Initial Enrollment Period (IEP) is a 7-month window tied to your 65th birthday. It begins 3 months before the month you turn 65, includes your actual birthday month, and extends 3 more months after that birthday month. This is the single most important timeline in Medicare, and it applies to every North Carolina resident turning 65 regardless of where in the state they live.
Here is the part most people get wrong: when you enroll within that window matters as much as whether you enroll. If you wait until the final 3 months of your IEP, your Part B coverage will be delayed by one to three months from when you expected it to start. Enrolling during the first 3 months or your actual birthday month gives you the cleanest coverage start date.
If you are already collecting Social Security benefits at least four months before you turn 65, you will typically be enrolled in Medicare Parts A and B automatically, and your red, white, and blue Medicare card will arrive in the mail. But if you have not yet claimed Social Security, you must actively sign yourself up. That distinction trips up a significant number of soon-to-be-65 North Carolinians every year.
The Four Parts of Medicare, Explained Simply
Before you can complete a Medicare enrollment checklist, you need to know what you are enrolling in. Medicare has four distinct parts, each covering something different, and decisions about one often affect the others.
Part A: Hospital Insurance
Part A covers inpatient hospital stays, skilled nursing facility care, hospice, and some home health services. Most people qualify for premium-free Part A if they or their spouse paid Medicare taxes through work for at least 10 years (40 quarters). For those who qualify, enrolling in Part A at 65 is almost always the right call, even if you are delaying other parts.
Part B: Medical Insurance
Part B covers doctor visits, outpatient care, preventive services, and medically necessary services. Unlike Part A, Part B comes with a monthly premium. The standard base premium in 2026 is $185.00 per month, though higher-income beneficiaries may pay more through IRMAA surcharges. Part B is where most of the enrollment penalty risk lives for people who delay without a valid reason.
Part C: Medicare Advantage
Medicare Advantage plans are offered by private insurance companies approved by Medicare. They bundle Parts A and B coverage and usually include Part D drug coverage as well. Many plans also include extra benefits like dental, vision, and hearing. In North Carolina, including the Charlotte metro area, there is a competitive market of Medicare Advantage plans to choose from each year.
Part D: Prescription Drug Coverage
Part D is standalone prescription drug coverage, used alongside Original Medicare (Parts A and B) and a Medicare Supplement plan. Choosing not to enroll in Part D when you first become eligible, without having other creditable drug coverage, triggers its own permanent penalty. Do not skip this decision thinking you will deal with it later.
Your Step-by-Step Medicare Enrollment Checklist
Use this checklist as your working document in the months leading up to your 65th birthday. These steps are sequenced intentionally. Skipping ahead or doing them out of order causes real problems.
Six to Nine Months Before You Turn 65
Review your current health insurance situation. If you have employer group coverage, find out whether it is considered creditable for Medicare purposes. Contact your HR department and ask directly. This answer determines whether you need to enroll in Medicare right at 65 or whether you have flexibility. Do not assume either way.
Start collecting your documents. You will need your Social Security card, proof of citizenship or legal residency, employment history details (specifically W-2s or self-employment tax returns), and information about any current health coverage. Having these ready avoids a last-minute scramble.
Pro tip: If you were born on the first day of a month, Social Security treats your birthday as falling in the prior month for Medicare purposes. This means your enrollment period and coverage start date shift by a full month. Confirm your specific timeline with a licensed Medicare advisor to avoid surprises.
Three Months Before Your 65th Birthday Month
This is when your Initial Enrollment Period officially opens. You can now apply for Medicare through the Social Security Administration’s website at ssa.gov or by visiting a local Social Security office. For Charlotte-area residents, there are several SSA offices serving Mecklenburg County and surrounding counties.
If you are not taking Social Security retirement benefits yet, you will need to proactively enroll. The SSA application for Medicare Part A and Part B is separate from applying for retirement benefits. You can enroll in Medicare without triggering your Social Security retirement payments.
During Your Birthday Month
Confirm your enrollment status. If you applied, check that your application has been processed and request your Medicare card if it has not arrived. If you are being automatically enrolled, your card should appear in the mail roughly three months before your birthday month begins.
Begin seriously comparing plan options. This is when you should be speaking with an independent Medicare insurance agency, not just browsing a single carrier’s website. Safeguard Benefit Services works with 30+ insurance companies, which means the recommendation you receive is based on what fits your situation, not what one carrier happens to offer.
Within Six Months of Your Part B Start Date
This is your Medigap Open Enrollment Period and it is the most important window for Medicare Supplement shoppers. During this 6-month window, insurance companies in North Carolina cannot deny you a Medigap policy, charge you more because of health conditions, or make you wait for coverage to begin based on a pre-existing condition. Once this window closes, you lose those guaranteed-issue rights in most circumstances.
Pro tip: Many people assume they can always buy a Medicare Supplement plan later if they start with Medicare Advantage. In North Carolina, switching back to a Medigap plan after your open enrollment period has passed typically requires you to pass medical underwriting. If your health has changed, you may be denied coverage or charged significantly higher premiums. Make the Medigap decision carefully and early.
Medicare Advantage vs. Medicare Supplement in North Carolina
This is the most consequential decision most people turning 65 in North Carolina will make about their healthcare. Getting it wrong does not mean the end of the world, but correcting it later can be difficult or expensive. Here is a direct comparison of the two main approaches.
Feature | Medicare Advantage (Part C) | Medicare Supplement (Medigap) |
|---|---|---|
Monthly premium | Often $0 to low monthly premium; some plans available for no additional premium beyond Part B | Monthly premium varies by plan and carrier; Plan G in North Carolina averages around $155/month for a 65-year-old, though rates vary |
Provider network | Typically requires using in-network providers; HMO or PPO structures apply | Accepted by any provider nationwide who accepts Original Medicare |
Out-of-pocket maximum | Plans set an annual out-of-pocket maximum, capping your exposure | Depends on the plan; Plan G covers most out-of-pocket costs except the Part B deductible |
Extra benefits | Often includes dental, vision, hearing, and sometimes fitness benefits | No extra benefits beyond coverage of Medicare cost-sharing gaps |
Drug coverage | Usually bundled into the Advantage plan | Requires separate Part D plan enrollment |
Plan stability | Plans can change networks, benefits, and premiums annually | Benefits are federally standardized; plan type stays consistent year to year |
Best for | People who want low upfront costs and do not travel frequently for care | People who want predictable costs and freedom to see any Medicare-accepting doctor |
There is no universally correct answer here. The right choice depends on your health, your finances, how often you travel, and which doctors you want to keep seeing. What matters is making the decision with complete information, not defaulting to whatever a single carrier’s 800 number suggests.
The decision between Medicare Advantage and Medicare Supplement is not about which one is better. It is about which one fits your specific life, health needs, and financial situation right now and five years from now.
Late Enrollment Penalties: What North Carolina Residents Must Know
Penalties for late Medicare enrollment are not temporary surcharges. They are permanent additions to your monthly premium for as long as you have Medicare. Understanding them is not optional if you want to protect your retirement budget.
Part B Late Enrollment Penalty
For each 12-month period you go without Part B coverage after becoming eligible (and without a qualifying exception), your Part B premium increases by 10%. Those penalties stack. Someone who delays 3 years without qualifying employer coverage pays 30% more than the standard Part B premium, permanently. With the 2026 base Part B premium at $202.90 per month, that is a real financial hit that compounds over time.
Part D Late Enrollment Penalty
The Part D penalty is calculated differently but is equally permanent. If you go 63 or more consecutive days without creditable prescription drug coverage after your Initial Enrollment Period ends, Medicare calculates a penalty equal to 1% of the national base beneficiary premium for each month you were without coverage. That amount is added to your Part D premium permanently.
Part A Penalty (Less Common)
Most people get Part A premium-free, so this rarely applies. But if you must pay a premium for Part A and you delay enrollment, your premium can increase by 10% for twice the number of years you delayed. This affects a smaller population but is still worth understanding if your work history does not qualify you for premium-free Part A.
Working Past 65: What Changes for Your Enrollment
Working past 65 with active employer group health coverage is one of the legitimate reasons to delay Medicare enrollment without incurring penalties. But the rules here are specific and easily misunderstood, and a mistake can still result in a penalty even when you thought you were covered.
The key is the size of your employer. If your employer has 20 or more employees, your group health plan is considered primary coverage and Medicare is secondary. In that situation, you can delay Part B enrollment without triggering the late enrollment penalty. You will receive a Special Enrollment Period (SEP) when your employment or group coverage ends, giving you 8 months to enroll in Part B without penalty.
However, if your employer has fewer than 20 employees, Medicare is considered primary even while you are still working. In that case, delaying Medicare enrollment could leave you with real coverage gaps and penalty exposure. Many people in this situation do not find out until it is too late.
Coverage through a spouse’s employer follows similar rules. The employer size and whether the coverage is considered active group coverage both matter. COBRA coverage and retiree health plans do not count as qualifying employer coverage for purposes of delaying Medicare without penalty. Do not assume they do.
North Carolina Resources That Can Help
North Carolina has a state program called SHIIP, the Seniors’ Health Insurance Information Program, which is a division of the NC Department of Insurance. SHIIP counselors provide free, unbiased assistance to Medicare beneficiaries and those approaching Medicare eligibility. They can help you understand your options, compare plans, and navigate enrollment questions. The statewide SHIIP line is 1-855-408-1212.
That said, SHIIP counselors are generalists working across all of North Carolina’s diverse coverage landscape. They will help you understand Medicare broadly. For a more personalized comparison of specific plan options in the Charlotte metro area, from an advisor who works with those plans daily and knows the local carrier landscape, an independent Medicare insurance agency is a better fit for many people.
Safeguard Benefit Services is based in Charlotte and serves clients throughout North Carolina. Their licensed representatives work with 30+ carriers and offer free consultations with no obligation to purchase anything. If you are turning 65 and feel overwhelmed by the options, that is exactly the kind of situation they handle every day. You can reach them through their contact page or explore your options at their Medicare Advantage overview and Medicare Supplement information page.
Frequently Asked Questions
When should I start researching Medicare if I turn 65 in North Carolina?
Start at least 6 to 9 months before your 65th birthday. That gives you time to review your current coverage, gather the documents you need, understand your options, and enroll without rushing. The actual enrollment window opens 3 months before your birthday month, but preparation should start well before that.
Do I have to take Medicare when I turn 65 in North Carolina?
You are not legally required to take Medicare at 65, but delaying without a qualifying exception, such as active employer group coverage, will result in permanent late enrollment penalties for Part B and potentially Part D. Most people who are no longer working or who have retiree health coverage should enroll in Medicare during their Initial Enrollment Period.
What is the difference between Medicare Advantage and Medicare Supplement in North Carolina?
Medicare Advantage replaces Original Medicare with a private plan that often includes drug coverage and extra benefits like dental and vision, usually with lower premiums but network restrictions. Medicare Supplement (Medigap) works alongside Original Medicare to cover cost-sharing gaps, typically at higher monthly premiums but with freedom to see any Medicare-accepting provider nationwide. North Carolina residents approaching 65 should compare both based on their specific health needs, travel habits, and budget.
Can I be denied a Medicare Supplement plan in North Carolina?
During your Medigap Open Enrollment Period, which is the 6-month window starting when you are both 65 and enrolled in Part B, North Carolina insurers cannot deny you a Medigap policy based on health conditions. Outside of that window, most insurers can use medical underwriting to deny coverage or charge higher premiums. This is why timing your Medigap decision during that open enrollment period is so important.
What happens if I miss my Medicare Initial Enrollment Period?
If you miss your IEP without a qualifying exception, you will generally have to wait for the General Enrollment Period, which runs January 1 through March 31 each year, with coverage starting July 1. More importantly, you will face a permanent late enrollment penalty on your Part B premium and potentially your Part D premium. There is no way to remove these penalties once they are assessed, which is why acting during your IEP is so important.
Is there help available in Charlotte, NC for Medicare enrollment?
Yes. North Carolina’s SHIIP program provides free statewide counseling through the NC Department of Insurance. For Charlotte-area residents who want personalized plan comparisons and hands-on guidance from licensed advisors who work with 30+ carriers, Safeguard Benefit Services offers free consultations and year-round support from their Charlotte office. Many people find that working with an independent agency gives them access to more options and more tailored recommendations than any single source can offer.
Have you recently gone through the Medicare enrollment process in North Carolina? Share your experience or your biggest question in the comments below, your insight could help someone else navigating the same steps.
References
Overview of Medicare plan types and enrollment periods available to North Carolina residents
How Medicare late enrollment penalties work for Parts A, B, and D and how to avoid them
CMS official guidance on Part D creditable coverage and the late enrollment penalty
North Carolina Medicare plan options, Medigap enrollment data, and premium comparisons
North Carolina Department of Insurance SHIIP program information for Medicare beneficiaries








Get Connected