
Missing your Medicare Initial Enrollment Period is one of the most expensive mistakes a person turning 65 can make, and it happens more often than most people expect. The window is only seven months long, the penalties for missing it are permanent, and the rules around coverage start dates are counterintuitive enough to trip up even well-prepared retirees. If you are approaching 65 in North Carolina and wondering when to enroll in Medicare, this is the guide you need to read before you do anything else. The decisions you make in this window will follow you for the rest of your life.
Table of Contents
- What Is the Medicare Initial Enrollment Period?
- When Does Your IEP Start and End?
- Coverage Start Dates: The Timing Trap Most People Miss
- What You Can Enroll In During Your IEP
- The Real Cost of Missing Your Medicare Enrollment Window
- What Happens If You Miss Your IEP?
- IEP vs. Other Enrollment Periods: A Direct Comparison
- Frequently Asked Questions
- References
What Is the Medicare Initial Enrollment Period?
The Medicare Initial Enrollment Period is the first and most important opportunity you have to sign up for Medicare. It is a seven-month window built around your 65th birthday, and it is the one time you can enroll without facing any late enrollment penalties, regardless of your health status, income, or current coverage situation.
This is not the same as the Annual Enrollment Period that runs each fall, and it is not the General Enrollment Period that runs January through March. Your IEP is unique to you and tied entirely to your date of birth. No one else has the same IEP dates as you.
For the millions of Americans who are not automatically enrolled in Medicare, the IEP is the enrollment window they need to act on. If you are collecting Social Security benefits at least four months before you turn 65, you will be enrolled in Parts A and B automatically, and you will receive your Medicare card in the mail about three months before your birthday. But even automatic enrollees still need to make active decisions about Part D and Medicare Advantage during this same period.
| Key Insight | Explanation |
|---|---|
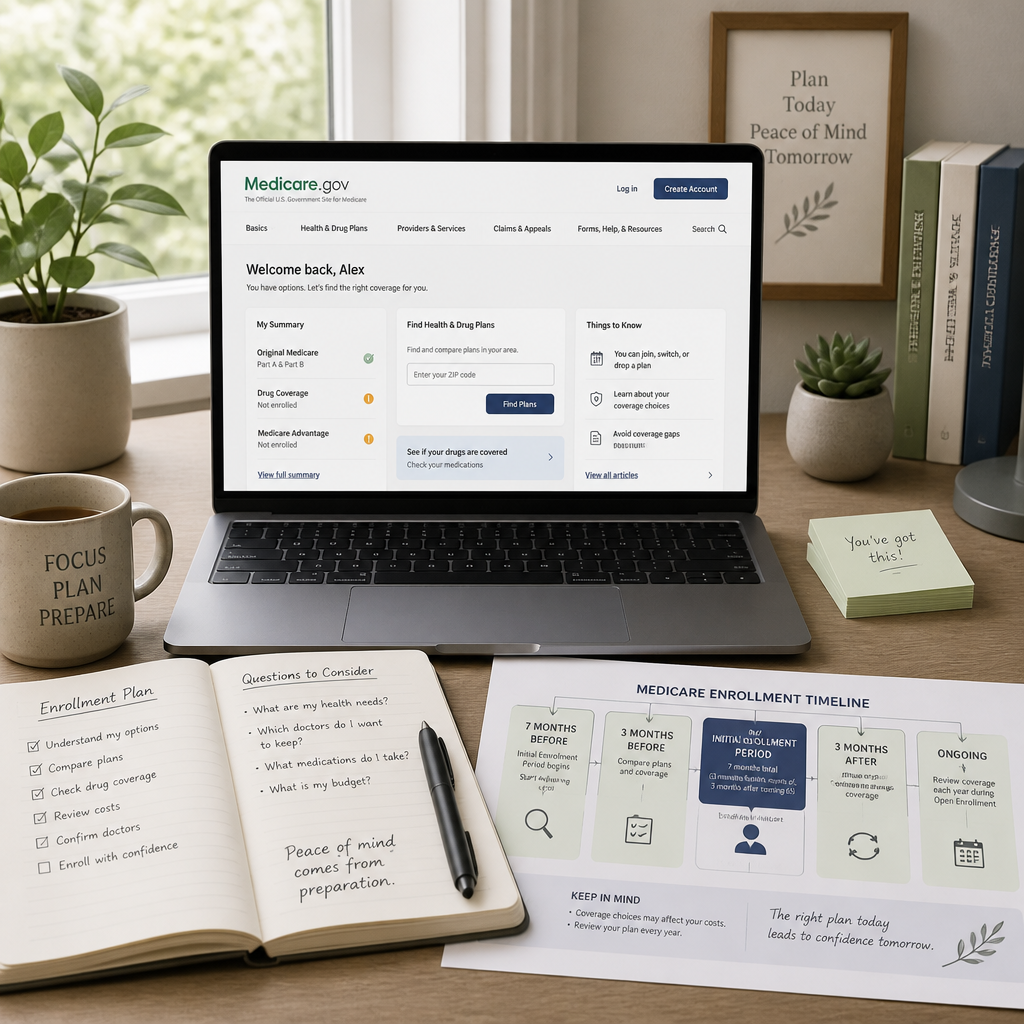
| The IEP is 7 months long | It covers 3 months before your birthday month, your birthday month itself, and 3 months after. |
| Enroll in the first 3 months for the best coverage start date | Signing up in the 3 months before your birthday month means coverage starts on the first day of your birthday month, with no gap. |
| Part B penalties are permanent | Missing your IEP without qualifying for a Special Enrollment Period adds 10% to your Part B premium for every 12-month period you went without coverage, and that surcharge lasts for life. |
| Part D penalties are also permanent | Going without creditable prescription drug coverage after your IEP adds roughly 1% of the national base beneficiary premium per uncovered month, forever. |
| Auto-enrollment does not cover everything | Even if you are automatically enrolled in Parts A and B, you still must actively choose a Part D plan or Medicare Advantage plan. |
| Birthdays on the 1st of the month shift the IEP earlier | If your birthday falls on the first of any month, Medicare treats you as if you were born the prior month, moving your entire IEP window back by one month. |
| Employer coverage may allow you to delay, but only under specific rules | If you or your spouse are covered by an active employer group health plan, you may qualify for a Special Enrollment Period. Retiree coverage does not qualify. |
When Does Your IEP Start and End?
Your IEP begins exactly three months before the month you turn 65, includes the month of your birthday, and ends three months after. That gives you a total of seven months to act. For example, if your birthday is in August, your IEP runs from May 1 through November 30.
There is one exception worth knowing. If your birthday falls on the first day of a month, Medicare treats it as if your birthday occurred in the prior month. That means your IEP starts four months before your actual birth month instead of three. If you were born on June 1, your IEP would begin in February, not March.
This window is fixed. It does not flex based on your plans, your employment situation, or whether you feel ready. The clock starts running on a specific date whether you are paying attention or not. That is why people approaching 65 in Charlotte and across North Carolina need to start planning at least six months before their birthday month, not the week before.
Pro tip: Mark the first day of the three-month pre-birthday window on your calendar and treat it as your personal enrollment deadline, not the end of the IEP. Enrolling early in the window gives you the best possible coverage start date and leaves time to compare plans without rushing.
Coverage Start Dates: The Timing Trap Most People Miss
Here is where most people get caught off guard. The IEP is seven months long, but enrolling at different points within that window produces different coverage start dates. This is not a minor administrative detail. A delayed coverage start date can mean weeks or months without Medicare coverage after your previous insurance has ended.
Enrolling in the First Three Months
If you enroll during the three months before your birthday month, your coverage starts on the first day of your birthday month. This is the ideal scenario. You have continuous coverage from the moment you are eligible, and you had enough time to compare plans carefully.
Enrolling in Your Birthday Month or Later
If you wait until your birthday month or any of the three months after, your coverage starts on the first day of the month after you apply. The later you enroll within the IEP, the longer you wait for coverage to begin. In practice, someone who waits until the last month of their IEP could go nearly four months without active Medicare coverage after turning 65. That gap can be expensive if any significant health event occurs during that time.
The lesson here is straightforward. Earlier in the IEP is always better. There is no strategic benefit to waiting until the final months of the window, and there is a real cost to doing so.
Pro tip: If you are leaving employer coverage at the same time you turn 65, coordinate the end date of your current plan with your Medicare coverage start date. A gap of even a few days can leave you exposed. A licensed Medicare advisor at Safeguard Benefit Services can help you map this out before your current coverage ends.
What You Can Enroll In During Your IEP
Your IEP is not just for signing up for Part A and Part B. It is also the window for enrolling in all the supplemental coverage decisions that determine what your Medicare will actually cost you day to day.
Medicare Part A and Part B
Part A covers hospital stays, skilled nursing facility care, and some home health services. Most people do not pay a premium for Part A if they have enough work credits. Part B covers outpatient medical services, doctor visits, preventive care, and durable medical equipment. The standard monthly Part B premium in 2025 is $185.00. Both are the foundation of Original Medicare, and both must be in place before you can add any supplemental coverage.
Medicare Advantage (Part C) and Prescription Drug Plans (Part D)
Once enrolled in Parts A and B, you can choose a Medicare Advantage plan instead of Original Medicare, or you can keep Original Medicare and add a standalone Part D Prescription Drug Plan. The IEP is your first chance to do this with access to the widest selection of plans and no risk of medical underwriting for Medicare Supplement plans.
At Safeguard Benefit Services, the team works with more than 30 carriers to compare Medicare Advantage, Medicare Supplement, and Part D options side by side. That breadth of access matters because the right plan for your specific prescriptions, doctors, and budget is rarely obvious from a single carrier’s offerings.
Medicare Supplement (Medigap) Plans
Your Medigap Open Enrollment Period, the six-month window during which insurers cannot use medical underwriting to deny you or charge you more, starts the month you are both 65 and enrolled in Part B. This overlaps with your IEP. Choosing a Medigap plan during this window locks in access you may not be able to get later if your health changes. Missing it does not mean you can never get a Medigap plan, but it may mean you face medical review and potentially higher premiums or denials.
You can read more about Medicare eligibility requirements to confirm your specific situation before your enrollment window opens.
The Real Cost of Missing Your Medicare Enrollment Window
The financial consequences of missing your IEP are not theoretical. They are calculable, and they compound over time because they are added permanently to your monthly premium.
Part B Late Enrollment Penalty
For every 12-month period you could have had Part B but did not enroll, Medicare adds a 10% surcharge to your monthly Part B premium. This penalty is permanent. It does not expire after a few years. If you went 26 months without Part B coverage, you would pay a 20% penalty on top of the standard premium for as long as you have Part B, which is likely the rest of your life. As standard Part B premiums rise each year, so does the dollar amount of that penalty.
Part D Late Enrollment Penalty
The Part D penalty works differently but is equally permanent. Medicare calculates it by multiplying 1% of the national base beneficiary premium by the number of months you went without creditable prescription drug coverage. That figure is then rounded to the nearest $0.10 and added to your Part D premium each month, forever.
The single most costly Medicare mistake is not missing the enrollment deadline itself. It is assuming that you will figure it out later, when “later” turns out to mean a permanent premium penalty that follows you for decades.
None of these penalties apply if you have qualifying creditable coverage elsewhere during the period in question. But employer retiree coverage, marketplace plans, and COBRA do not all qualify the same way, and getting that determination wrong is a common and expensive error.
What Happens If You Miss Your IEP?
If you miss your IEP and do not qualify for a Special Enrollment Period, you are left with limited options, none of them as good as enrolling on time.
The General Enrollment Period
The General Enrollment Period (GEP) runs from January 1 through March 31 each year. You can sign up for Part A or Part B during this window, but your coverage does not start until July 1 of that year. That means if you enroll in January, you still wait until July for active coverage. And you will owe the late enrollment penalty on top of everything else.
Special Enrollment Periods
A Special Enrollment Period (SEP) lets you sign up outside the IEP without penalty if you meet specific qualifying conditions. The most common qualifying condition is being covered by an employer group health plan through your own or your spouse’s active employment. The key word is active. Retiree health coverage, COBRA, and marketplace plans do not qualify for an SEP. Once that employer coverage ends, you typically have an eight-month window to enroll in Part B without penalty.
Many people in North Carolina are surprised to learn that their retiree health plan does not protect them from penalties the way an active employer plan does. Getting clarity on this before age 65 is one of the most valuable things a licensed Medicare advisor can do for you. The month-by-month Medicare checklist for Charlotte seniors covers exactly this kind of planning detail.
IEP vs. Other Enrollment Periods: A Direct Comparison
Understanding how the IEP differs from the other Medicare enrollment periods prevents costly confusion. The table below compares the three most relevant enrollment windows for someone turning 65.
| Enrollment Period | When It Occurs | Key Characteristics |
|---|---|---|
| Initial Enrollment Period (IEP) | 3 months before your 65th birthday month through 3 months after (7 months total) | No penalty for enrolling. First opportunity to sign up for all Medicare parts. Medigap Open Enrollment runs concurrently. Coverage start date depends on when in the IEP you enroll. |
| General Enrollment Period (GEP) | January 1 through March 31 each year | Available if you missed your IEP and do not qualify for an SEP. Late enrollment penalties apply. Coverage does not start until July 1, regardless of when in the GEP you sign up. |
| Special Enrollment Period (SEP) | Triggered by a qualifying life event, such as losing employer group health coverage | No late enrollment penalty if you qualify. Most common qualifier is active employer group health coverage. Must enroll within 8 months of losing that coverage. Does not apply to retiree plans or COBRA. |
The IEP is clearly the most favorable enrollment window. The GEP costs you time and money. The SEP is useful but only applies under specific circumstances. If you have any doubt about which category applies to you, get a clear answer before your IEP closes, not after.
Frequently Asked Questions
What is the Medicare Initial Enrollment Period?
The Medicare Initial Enrollment Period is a seven-month window centered around your 65th birthday during which you can first sign up for Medicare Parts A, B, C, and D. It begins three months before your birthday month, includes your birthday month, and ends three months after. Enrolling during this period means no late enrollment penalties and the best possible coverage start dates.
When should I enroll in Medicare to avoid a coverage gap?
Enroll during the three months before your birthday month. Signing up in this first portion of your IEP means your coverage starts on the first day of your birthday month, with no gap between your prior insurance and your Medicare. Waiting until your birthday month or later pushes your coverage start date to the following month or later.
Do I need to sign up for Medicare if I already have health insurance through my employer?
It depends on the size of your employer. If you or your spouse work for a company with 20 or more employees and are covered by that employer’s active group health plan, you may delay Part B enrollment without penalty and use a Special Enrollment Period later. However, if you work for a small employer with fewer than 20 employees, Medicare becomes the primary payer at 65 and you should enroll during your IEP. Always confirm the specifics of your situation with a licensed advisor before deciding to delay.
What happens if I miss my Medicare Initial Enrollment Period?
If you miss your IEP and do not qualify for a Special Enrollment Period, you will need to wait for the General Enrollment Period, which runs from January 1 through March 31. Your coverage will not start until July 1 of that year. You will also owe a permanent late enrollment penalty added to your monthly premium for as long as you have Medicare. The longer you wait, the larger that penalty becomes.
Is the Medicare Initial Enrollment Period the same as the Annual Enrollment Period?
No. The Annual Enrollment Period, which runs from October 15 through December 7 each year, is for existing Medicare beneficiaries who want to switch plans. The Initial Enrollment Period is for people who are new to Medicare, specifically those turning 65. Your IEP happens once and is tied to your birth date. Missing it and hoping to “use the fall enrollment period instead” is a common misunderstanding that leads directly to penalties.
Can I enroll in a Medicare Supplement plan during my IEP?
Yes, and this is one of the most important reasons to enroll early in your IEP. Your six-month Medigap Open Enrollment Period starts the month you are both 65 and enrolled in Part B. During this window, insurance companies cannot deny you a Medicare Supplement plan or charge you more due to pre-existing conditions. Once this window closes, you may still be able to apply for a Medigap plan, but the insurer can use medical underwriting, which may result in higher premiums or denial of coverage.
Have questions about your own enrollment window or want to share what helped you navigate Medicare for the first time? Drop a comment or send us a message. We read every one.
References
- Official Medicare.gov guide explaining when Medicare coverage starts based on your enrollment timing
- Social Security Administration overview of when to sign up for Medicare and Special Enrollment Period rules
- Medicare.gov resource on understanding and avoiding late enrollment penalties for Parts A, B, and D
- MedicareFAQ detailed breakdown of IEP dates, coverage start timing, and what each part covers
- eMedicare guide to Medicare enrollment periods, deadlines, and the consequences of missing them








Get Connected