
Most people turning 65 assume Medicare covers everything. Then they get their first medical bill and realize it does not. Medicare Advantage vs. Medicare Supplement is the decision that will determine how much you pay out of pocket for the rest of your life, and it is one of the most consequential choices you will make as you approach retirement. Both plan types fill the gaps in Original Medicare, but they do it in completely different ways, with completely different trade-offs. Getting this wrong can cost you thousands of dollars and limit your access to doctors you trust. This guide explains exactly how each option works, who each one is right for, and what North Carolina residents specifically need to know before they sign up.
Table of Contents
- Quick Takeaways
- How Each Plan Actually Works
- The Real Cost Comparison
- Provider Access and Network Restrictions
- Medigap vs. Medicare Advantage: The Side-by-Side Breakdown
- Who Should Choose Medicare Advantage
- Who Should Choose Medicare Supplement
- North Carolina Enrollment Rules You Cannot Ignore
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Medicare Advantage replaces Original Medicare | It bundles Parts A and B, often with Part D drug coverage, into one private plan. You use that plan’s network, not Original Medicare directly. |
| Medicare Supplement works alongside Original Medicare | You keep Original Medicare and add a Medigap policy that picks up costs Medicare does not cover, such as copayments, coinsurance, and deductibles. |
| Lower premium does not mean lower total cost | Medicare Advantage plans often advertise $0 premiums, but out-of-pocket costs can reach $8,550 or more per year depending on the plan and services used. |
| Medigap enrollment timing is everything in North Carolina | Your six-month Open Enrollment Period starts when you turn 65 and enroll in Part B. After it closes, insurers can deny you or charge more based on your health history. |
| Medigap gives you nationwide provider freedom | Any doctor or hospital that accepts Medicare must accept your Medigap coverage. Medicare Advantage restricts you to a network that may not include your preferred providers. |
| You cannot have both plans at once | Medicare Advantage and Medicare Supplement do not work together. Choosing one means you are not using the other. |
| Switching from Medicare Advantage to Medigap later is difficult | Outside of your initial enrollment window, most states allow insurers to deny Medigap coverage based on health conditions. Timing your first choice correctly matters enormously. |
How Each Plan Actually Works
Understanding the structural difference between these two plan types is the foundation of every good Medicare decision. They are not two versions of the same thing. They are two entirely different approaches to covering what Original Medicare does not pay.
Medicare Advantage (Part C): The All-in-One Replacement
Medicare Advantage is offered by private insurance companies that contract with Medicare. When you enroll, you are essentially handing your Medicare benefits over to that private insurer. The plan must cover everything Original Medicare covers, and most plans bundle in prescription drug coverage and sometimes extra benefits like dental, vision, and hearing. What you give up in exchange is flexibility: you are now bound to the plan’s network, its rules around prior authorization, and its cost-sharing structure, which changes every year.
The appeal is real. Many plans carry a $0 monthly premium beyond the Part B premium you continue to pay regardless. For someone healthy who rarely sees a doctor, that lower upfront cost is attractive. But the annual out-of-pocket maximum, which by law must cap your liability, can reach into the thousands. The out-of-pocket maximum for Medicare Advantage plans can range widely, and hitting that ceiling while managing a serious illness is a very different experience than paying a predictable Medigap premium every month.
Medicare Supplement (Medigap): The Cost-Predictability Option
Medicare Supplement insurance, also called Medigap, does not replace Original Medicare. It sits alongside it. You see any doctor or visit any hospital that accepts Medicare anywhere in the country, Medicare pays its share, and your Medigap policy covers most or all of the remainder, depending on the plan letter you choose. Plans are standardized by the federal government, meaning Plan G from one insurer covers the same services as Plan G from any other insurer. The only real difference between insurers for the same plan letter is the monthly premium.
The trade-off is a higher monthly premium compared to many Medicare Advantage plans. But for anyone who uses their health coverage regularly, the math often works in Medigap’s favor because there are no surprise bills and no network walls to navigate.
The most expensive Medicare plan is not necessarily the one with the highest premium. It is the one that leaves you with the largest bill when you actually need care.
The Real Cost Comparison
The word “free” gets thrown around a lot in Medicare Advantage marketing. It is misleading. You always pay the Part B premium, which is $202.90 per month in 2026, regardless of which plan type you choose. Beyond that, the cost structures diverge sharply.
What Medicare Advantage Actually Costs in Practice
Many Medicare Advantage plans carry a $0 monthly premium in addition to Part B. That sounds like a great deal. But every time you use the plan, you pay copays. Office visits, specialist visits, hospital stays, and outpatient procedures all carry their own cost-sharing requirements. The annual out-of-pocket maximum for Medicare Advantage plans can reach $8,550 or higher in 2025, meaning that is how much you could owe in a single year before the plan covers 100 percent of your costs for the rest of that year.
For someone who has a major health event like a surgery, cancer diagnosis, or extended hospital stay, hitting that ceiling is a real possibility. And those out-of-pocket limits can change from year to year as insurers adjust their plans during the annual enrollment period.
What Medigap Actually Costs in Practice
Medigap premiums vary significantly by plan letter, your age at enrollment, the insurer, and your location. High-deductible Medigap plans can carry premiums as low as roughly $40 to $50 per month, while comprehensive plans like Plan G tend to have higher monthly premiums. In exchange for that predictability, your out-of-pocket exposure for covered Medicare services is dramatically reduced, and with the most comprehensive plan letters, often eliminated entirely once you meet the small Part B deductible of $283 in 2026.
A common mistake people make is comparing only the monthly premiums side by side. The more honest comparison includes total annual cost assuming a moderate or heavy use of health services. For people who see doctors regularly, manage chronic conditions, or simply want to sleep without worrying about what a hospitalization will cost them, Medigap’s total annual cost frequently comes out lower once you run the real numbers.
Pro tip: Before assuming Medicare Advantage costs less, estimate your likely annual healthcare usage. Add up the plan’s copays for your specialist visits, your regular lab work, and at least one potential urgent care visit. Compare that total to a Medigap premium. The result often surprises people.
Provider Access and Network Restrictions
This is where the difference between these two plan types becomes most personal. Who you can see, and where, changes your entire experience of Medicare.
Medicare Advantage Network Rules
Medicare Advantage plans use provider networks: HMOs, PPOs, and other structures that define which doctors and hospitals are “in network.” If your preferred cardiologist, oncologist, or primary care physician is not in the plan’s network, you either pay out-of-network rates (which can be substantially higher) or you find a new doctor. Plans can also change their networks each year, which means a provider who was in-network when you enrolled may not be in-network the following January.
Travel is another significant limitation. Medicare Advantage plans generally cover emergency care nationally, but non-emergency care outside your plan’s service area may not be covered or may come with steep out-of-pocket costs. If you spend winters in Florida or visit family in another state regularly, this restriction deserves serious attention before you enroll.
Medigap Provider Freedom
With a Medigap policy, the network question does not exist. Any doctor or hospital that accepts Medicare, anywhere in the United States, accepts your Medigap coverage. You do not need referrals to see a specialist. You do not call an insurer to get prior authorization for a procedure. You see the provider you want, Medicare pays its share, and Medigap covers the rest according to your plan letter. For people who travel frequently, have specialists they are attached to, or simply value not being told where they can receive care, this freedom is not a minor perk. It is a fundamental quality-of-life difference.
Medigap vs. Medicare Advantage: The Side-by-Side Breakdown
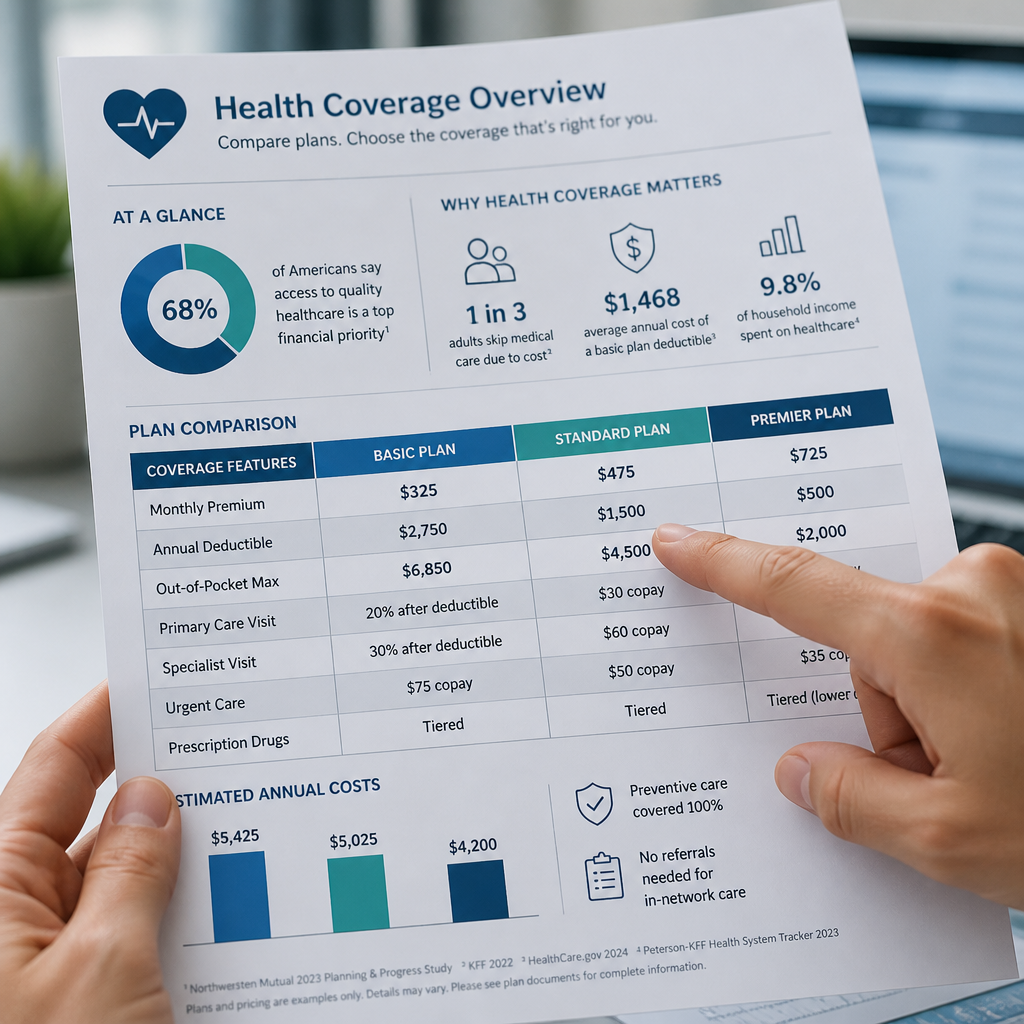
Here is a direct comparison of the three most important decision factors for someone approaching Medicare eligibility in North Carolina.
| Feature | Medicare Advantage (Part C) | Medicare Supplement (Medigap) |
|---|---|---|
| Monthly premium | Often $0 beyond Part B premium, but varies by plan | Higher monthly premium; varies by plan letter, age, and insurer |
| Out-of-pocket exposure | Annual cap required by law; can reach $8,550+ in 2025 | Dramatically reduced or eliminated depending on plan letter |
| Provider network | Restricted to plan’s in-network providers in most cases | Any doctor or hospital that accepts Medicare, nationwide |
| Prescription drug coverage | Usually included (Part D bundled in) | Not included; requires a separate Part D plan |
| Extra benefits | May include dental, vision, hearing, fitness | No extra benefits; coverage is medical cost-sharing only |
| Referrals required | Often yes, especially with HMO-type plans | No referrals needed |
| Plan stability | Network, costs, and benefits can change each year | Standardized plan letters; benefits do not change year to year |
| Prior authorization | Common for procedures, specialist visits, and medications | Not required; Medicare’s coverage rules apply directly |
Pro tip: If you are comparing two specific Medicare Advantage plans in North Carolina, look at the plan’s star rating from CMS and review the Evidence of Coverage document carefully before enrolling. The marketing materials will never tell you what the plan does not cover.
Who Should Choose Medicare Advantage
Medicare Advantage is a genuinely good fit for certain people. It is not the right answer for everyone, but dismissing it entirely would be as wrong as blindly enrolling in it because of a catchy commercial.
Medicare Advantage tends to work best for people who are generally healthy and do not use significant medical services, who are comfortable with a provider network and do not have established relationships with specific specialists, who want extra benefits like dental or vision bundled into their coverage, who live in one area year-round and will not need coverage outside their plan’s service area regularly, and who prioritize keeping their monthly premium costs low while accepting the risk of higher out-of-pocket costs if a major health event occurs.
It is worth noting that people with certain serious chronic conditions, including some specific severe diagnoses, may not qualify for standard Medicare Advantage plans and may need to look at specialized options. A licensed agent who works with multiple carriers can help identify what is actually available to you based on your health situation and zip code.
Who Should Choose Medicare Supplement
Medicare Supplement is the stronger choice for the majority of people who can afford the premiums and who enroll at the right time. The case for Medigap is straightforward: cost predictability, unrestricted provider access, and plan stability are difficult to argue against when you consider that healthcare needs tend to increase, not decrease, with age.
Medigap makes the most sense for people who have ongoing health conditions or see multiple doctors regularly, who want the freedom to see any Medicare-accepting provider without referrals or network approvals, who travel frequently or split their time between states, who want their coverage to remain stable from year to year without annual re-evaluation, and who understand that a higher monthly premium now can protect them from unpredictable and potentially devastating out-of-pocket costs later.
The most common mistake seen among new Medicare enrollees is choosing Medicare Advantage because of the low premium, managing fine for a few years, then developing a serious health condition and realizing they cannot switch to Medigap without medical underwriting. By that point, they may be denied coverage or quoted premiums so high that Medigap becomes unaffordable. Choosing Medigap while you are healthy and eligible for guaranteed issue is one of the most protective financial decisions a 65-year-old can make.
North Carolina Enrollment Rules You Cannot Ignore
North Carolina residents have specific protections and windows that determine how smoothly your Medicare enrollment goes. Understanding these rules is not optional if you want to avoid paying more or being denied coverage.
The Medigap Open Enrollment Window
Your Medigap Open Enrollment Period begins on the first day of the month in which you are 65 or older and enrolled in Medicare Part B. It lasts six months. During this window, insurers cannot deny you coverage, exclude pre-existing conditions, or charge you higher premiums based on your health history. This guaranteed-issue protection is the most valuable window in Medicare, and it closes exactly once. Once it ends, insurers in North Carolina are legally permitted to use medical underwriting to assess your risk before offering you a Medigap policy, which can result in denial or significantly higher rates.
North Carolina’s Under-65 Disability Protections
North Carolina state law provides an additional protection that not all states offer. Under North Carolina General Statute 58-54-45, disabled individuals under 65 who qualify for Medicare have guaranteed-issue rights to purchase a Medigap plan. This is a meaningful protection for people who come to Medicare before 65 due to disability, and it is more generous than federal law alone requires.
When Guaranteed Issue Rights Apply Outside Open Enrollment
Certain life events can trigger guaranteed-issue rights outside of your initial enrollment window. Leaving employer-sponsored coverage is one example. These windows are narrow and time-sensitive, typically lasting only 63 days from the qualifying event. If you miss them, you are back to medical underwriting territory. Working with an agency like Safeguard Benefit Services means having someone in your corner who tracks these windows and helps you act before they close.
The broader point is this: the best Medicare Supplement plan is often the one you enroll in during your guaranteed-issue window, not the one you try to get five years later after a health change. Timing is the single biggest controllable variable in this decision.
Frequently Asked Questions
Can I have both Medicare Advantage and Medicare Supplement at the same time?
No. These two plan types do not work together and cannot be combined. Medicare Supplement is designed to work alongside Original Medicare. Medicare Advantage replaces Original Medicare. If you are enrolled in Medicare Advantage, a Medigap policy provides no usable benefit. You must choose one approach or the other.
What happens if I choose Medicare Advantage and later want to switch to Medigap?
Switching from Medicare Advantage to Medigap after your initial enrollment window is possible, but it comes with significant risk. In most states, including North Carolina outside of specific guaranteed-issue situations, Medigap insurers can require medical underwriting after your Open Enrollment Period ends. This means you could be denied coverage or charged higher premiums based on existing health conditions. The time to get a Medigap policy with no questions asked is during your initial six-month Open Enrollment window at 65.
Does Medicare Supplement cover prescription drugs?
No. Medigap policies do not include prescription drug coverage. If you choose a Medicare Supplement plan, you will need to purchase a separate Medicare Part D prescription drug plan to cover your medications. When comparing the total cost of Medigap versus Medicare Advantage, make sure to include the cost of a standalone Part D plan in your Medigap total.
Is Medicare Advantage or Medigap better for someone with chronic health conditions?
For most people managing ongoing health conditions, Medicare Supplement is the stronger choice. Chronic conditions typically mean frequent doctor visits, specialist consultations, and sometimes hospitalizations. With Medigap, most of those costs are covered at a predictable monthly rate with no network restrictions. Medicare Advantage, by contrast, involves copays for each visit, network limitations, and prior authorization requirements that can delay care. The financial predictability of Medigap is especially valuable when healthcare usage is high and consistent.
Are the best Medicare Supplement plans in North Carolina the same as in other states?
The plan letters are federally standardized, meaning Plan G in North Carolina covers the same services as Plan G in any other state. What varies is the monthly premium, which is set by each insurer and differs by your age, location within the state, and the insurer’s own pricing. North Carolina also has its own state law protections for disabled Medicare beneficiaries under 65, which is more protective than federal rules alone. Working with a licensed agent who knows the North Carolina market specifically helps you compare actual premium quotes across carriers rather than relying on generic national estimates.
What does a free consultation with a Medicare agency actually include?
A legitimate free consultation from an agency like Safeguard Benefit Services means sitting down with a licensed sales representative who reviews your health situation, prescription drug list, preferred doctors, and budget, then walks you through the plans available in your area from multiple carriers. They should explain your enrollment windows, help you avoid penalties from missed deadlines, and give you a real cost comparison across options. You are not obligated to buy anything, and a good agency earns your trust through education, not sales pressure.
If you are currently weighing Medicare Advantage vs. Medicare Supplement for the first time, we would love to hear what questions are holding you back from making a decision. Drop your question or experience in the comments below.
References
- National Council on Aging: Original Medicare vs. Medicare Advantage differences, costs, and coverage explained
- Medicare.org: Hidden out-of-pocket costs and network restrictions in Medicare Advantage plans
- SelectQuote: Medicare Supplement plan enrollment windows and guaranteed issue rights in North Carolina
- eHealth Insurance: How Medicare Advantage and Medicare Supplement plans differ in coverage and cost-sharing
- GoHealth: Medicare Supplement vs. Medicare Advantage premium and enrollment trade-off analysis








Get Connected