

You are approaching Medicare eligibility, and someone has already told you to “just pick a plan.” That advice is not enough. Choosing between Medicare Advantage PPO plans and the alternatives is one of the most consequential healthcare decisions you will make, and the options available to Charlotte-area seniors are more varied than most people realize. In Mecklenburg County alone, there are 29 PPO plans available for 2026, yet most people enroll in whatever sounds familiar without understanding what they are actually buying. This guide explains exactly what a Medicare Advantage PPO is, how it compares to other plan types, and whether it fits a Charlotte senior’s real-life healthcare situation.
Table of Contents
- Quick Takeaways
- What Is a Medicare Advantage PPO Plan?
- How PPO Plans Work in Charlotte, NC
- PPO vs. HMO vs. Original Medicare: A Direct Comparison
- Who Benefits Most from a Medicare PPO in Charlotte
- What Medicare Advantage PPO Plans Actually Cost
- Common Mistakes Charlotte Seniors Make with PPO Enrollment
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| PPOs do not require referrals | You can schedule directly with specialists without going through a primary care gatekeeper first, saving time and steps. |
| Out-of-network care is covered, but costs more | A PPO pays for services outside its network, unlike most HMOs. You pay higher cost-sharing for that flexibility. |
| 29 PPO plans are available in Charlotte for 2026 | Mecklenburg County has significant PPO competition, meaning real choices exist, but comparison shopping is essential. |
| Many Charlotte PPO plans carry a $0 premium | Of the 29 PPO plans in Mecklenburg, 22 have a $0 monthly premium, with an average premium of roughly $19.62. |
| PPOs include an annual out-of-pocket maximum | Original Medicare has no out-of-pocket cap. PPO plans set a ceiling on your annual spending, limiting catastrophic exposure. |
| PPOs are a strong fit for frequent travelers | If you split time between North Carolina and another state, a PPO’s out-of-network coverage provides protection HMOs do not. |
| You cannot stack a PPO with a standalone Part D plan | Most PPO plans already bundle prescription drug coverage. Enrolling in a separate PDP alongside a PPO is not permitted. |
What Is a Medicare Advantage PPO Plan?
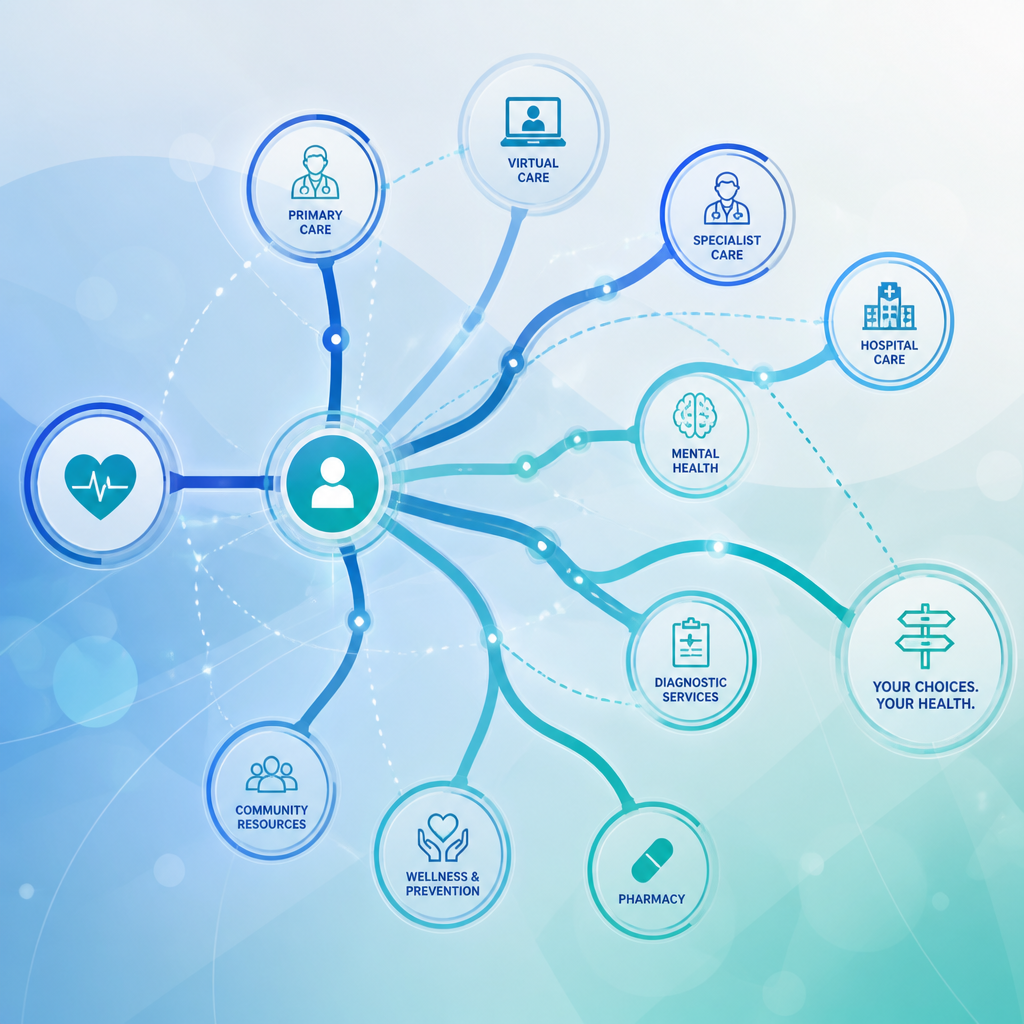
A Medicare Advantage PPO plan is a type of Medicare Part C coverage offered by a private insurer that bundles your Part A (hospital), Part B (medical), and usually Part D (prescription drug) benefits into one plan. PPO stands for Preferred Provider Organization. The defining feature is a two-tier provider network: in-network providers cost you less, and out-of-network providers cost you more, but you are still covered either way.
This is the detail that sets PPOs apart from HMO plans. With an HMO, leaving the network means paying the full bill yourself in most cases. With a PPO, the plan still picks up a portion of the tab even when you go outside its network. That distinction matters enormously when you need a specialist who does not participate with your plan, or when you need care while traveling outside the Charlotte area.
PPOs also require no referrals to see specialists. You can call a cardiologist, orthopedic surgeon, or dermatologist directly and make an appointment without first getting approval from a primary care physician. For seniors managing multiple conditions across several providers, this eliminates a frustrating and often time-consuming bottleneck.
The core value of a PPO is freedom with a financial structure attached to it. You are not trapped in a network, but you are incentivized to use one. That balance suits people who want real choice without abandoning cost protection entirely.
How PPO Plans Work in Charlotte, NC
Charlotte sits in Mecklenburg County, and plan availability is determined at the county level. For 2026, Mecklenburg County has 29 Medicare Advantage PPO plans available, covering over 18,000 beneficiaries. That is a meaningful number of plans, which means the differences between them, in network size, drug formularies, supplemental benefits, and cost-sharing structures, are real and worth examining carefully.
The top-enrolled PPO plan in Mecklenburg by enrollment count is the Aetna Medicare Signature PPO, with over 7,300 enrollees. Other carriers offering PPO options in the Charlotte market include Humana, UnitedHealthcare, Anthem Blue Cross and Blue Shield, and Wellcare, among others. The fact that multiple large carriers compete here generally works in a consumer’s favor, driving better benefits and keeping premiums competitive.
In-Network vs. Out-of-Network in Practice
When you use an in-network provider under your Charlotte PPO plan, you pay the plan’s negotiated cost-sharing rates: fixed copays or lower coinsurance. When you see an out-of-network provider, you typically pay a higher coinsurance percentage, and in some cases you may need to pay upfront and file for reimbursement. This is a real operational difference. If you regularly see a specialist at Atrium Health or Novant Health, confirm whether that provider is in-network before you enroll.
The Mecklenburg County plan data shows an average PPO premium of roughly $19.62 per month, with 22 of the 29 plans priced at $0 per month. A $0 premium does not mean $0 cost. You still pay your Medicare Part B premium, and you still face copays, coinsurance, and potentially a deductible depending on the specific plan.
Pro tip: Before enrolling in any Charlotte PPO plan, run your current doctors and your preferred hospital system through that plan’s provider directory. A plan with a $0 premium that puts your primary care doctor out-of-network will cost you significantly more than a plan with a modest premium that keeps all your providers in-network.
PPO vs. HMO vs. Original Medicare: A Direct Comparison
The right plan type for a Charlotte senior depends on how you actually use healthcare, not on which plan sounds most appealing in a brochure. Here is a side-by-side look at how the three primary options stack up on the factors that matter most in day-to-day use.
| Feature | Medicare Advantage PPO | Medicare Advantage HMO | Original Medicare (Parts A & B) |
|---|---|---|---|
| Out-of-network coverage | Yes, at higher cost-sharing | Emergency only in most cases | Yes, any Medicare-accepting provider nationwide |
| Referrals required for specialists | No | Usually yes | No |
| Primary care physician required | No | Yes, typically | No |
| Annual out-of-pocket maximum | Yes | Yes | No cap |
| Extra benefits (dental, vision, hearing) | Often included | Often included | Not included |
| Prescription drug coverage | Usually bundled | Usually bundled | Requires separate Part D plan |
| Monthly premium | Often $0, avg. ~$19.62 in Mecklenburg | Often $0 to low | Part B premium only (no cap on total costs) |
| Coverage while traveling out of state | Yes, out-of-network rates apply | Emergency only in most cases | Yes, nationwide |
Original Medicare’s biggest liability is the absence of an out-of-pocket maximum. If you have a serious illness or hospitalization, your 20% coinsurance under Part B has no ceiling. A Medicare Supplement (Medigap) plan can plug that gap, but those carry their own monthly premiums. A PPO plan bundles cost protection into a single product.
Pro tip: If you are comparing a PPO to a Medicare Supplement plan, compare total annual spending at different health usage levels, not just monthly premiums. Supplements often cost more per month but cap your total exposure in high-usage years. A Safeguard Benefit Services advisor can model this comparison for your specific situation at no charge.
Who Benefits Most from a Medicare PPO in Charlotte
PPO plans are not the right answer for every Charlotte senior. They are the right answer for a specific profile. If you match most of these criteria, a PPO is likely worth strong consideration.
You See Multiple Specialists Regularly
If you manage conditions that require regular visits to cardiologists, rheumatologists, endocrinologists, or other specialists, the referral-free structure of a PPO removes a real administrative burden. An HMO requires a referral from your primary care physician for each specialist visit. Over the course of a year with multiple chronic conditions, that adds up to time and friction you do not need.
You Travel or Spend Time in Multiple States
Many Charlotte-area seniors spend part of the year at a second home in Florida, South Carolina, or elsewhere. HMOs generally cover only emergency care outside their service area. A PPO’s out-of-network coverage means you can access care in another state, though you will pay the out-of-network cost-sharing rates. For someone who is genuinely mobile, this protection is not optional. It is essential.
You Want Flexibility Without Abandoning Cost Protection
A PPO is not as flexible as Original Medicare, which allows you to see any provider in the country who accepts Medicare without network tiers. But a PPO adds what Original Medicare lacks: an annual out-of-pocket maximum, usually bundled drug coverage, and extra benefits such as dental, vision, and hearing. If you want flexibility plus a financial safety net, a PPO hits a middle ground that neither pure Original Medicare nor a strict HMO offers.
What Medicare Advantage PPO Plans Actually Cost
The $0 premium headline is real for many Charlotte PPO plans, but it tells only part of the story. Your actual annual cost depends on how much care you use and where you get it. Here are the cost components you need to understand before you enroll.
Premiums
As of 2026 plan data for Mecklenburg County, the average PPO premium is roughly $19.62 per month, with 22 of the 29 available PPO plans priced at $0. You also continue to pay the Medicare Part B premium regardless of which plan you choose. The Part B premium is set annually by the federal government and applies to all Medicare beneficiaries.
Cost-Sharing: Copays and Coinsurance
Each plan sets its own copay amounts for primary care visits, specialist visits, urgent care, and hospital stays. Out-of-network services carry higher coinsurance rates than in-network services. This is where PPO costs can diverge significantly from plan to plan. Two plans with the same $0 premium can have very different cost-sharing structures for specialist visits or inpatient stays.
Out-of-Pocket Maximum
Every Medicare Advantage PPO plan, by federal requirement, must include an annual out-of-pocket maximum. Once your cost-sharing hits that ceiling for the year, the plan covers 100% of covered benefits for the rest of the year. This cap is one of the most important protections a PPO provides, and it is something Original Medicare does not offer at all. Note that most PPO plans set a separate, higher out-of-pocket maximum for out-of-network services, so the two tiers matter.
Pro tip: Do not evaluate a PPO plan by its out-of-pocket maximum alone. Check whether the cap applies to in-network services only, or to combined in-network and out-of-network spending. The answer changes your real exposure significantly if you end up needing out-of-network care.
Common Mistakes Charlotte Seniors Make with PPO Enrollment
After years of helping Charlotte-area residents navigate Medicare, the same mistakes show up repeatedly. Avoiding them is not complicated, but it requires asking the right questions before you sign.
Assuming All Providers Accept the Plan
The Charlotte healthcare market includes large systems like Atrium Health and Novant Health, along with independent practices and specialists. Not every provider in every system participates with every PPO plan. A provider can accept Medicare and still be out-of-network for your specific PPO. Verify your doctors individually against the plan’s provider directory before you enroll, not after.
Ignoring the Drug Formulary
Most Medicare Advantage PPO plans bundle prescription drug coverage. The specific drugs covered, and the tier-based cost-sharing for each drug, vary from plan to plan. If you take brand-name medications for chronic conditions, the difference in annual drug costs between two plans with identical premiums can run into hundreds or thousands of dollars. Check your current medications against each plan’s formulary before you decide.
Enrolling Outside Your Enrollment Window
Your Initial Enrollment Period (IEP) opens three months before you turn 65 and closes three months after. Missing it without a qualifying Special Enrollment Period can result in late enrollment penalties for Part B and Part D that follow you permanently. The Annual Enrollment Period runs October 15 through December 7 each year for plan changes. Enrolling late or switching outside these windows has real financial consequences that most people do not discover until they see them on a bill.
Treating the Decision as Permanent
A Medicare Advantage PPO plan is not a permanent commitment. You can switch plans during the Annual Enrollment Period. You also have a Medicare Advantage Open Enrollment Period from January 1 through March 31 each year, during which you can switch to another Medicare Advantage plan or return to Original Medicare. The decision you make at 65 can be revisited, but only at the right times and with full awareness of what changes when you switch.
Frequently Asked Questions
What is the difference between a Medicare Advantage PPO and an HMO in Charlotte?
A Medicare Advantage PPO allows you to see both in-network and out-of-network providers without a referral, though out-of-network care costs more. A Medicare Advantage HMO generally restricts you to in-network providers, requires you to designate a primary care physician, and typically requires referrals to see specialists. In the Charlotte market, both plan types are widely available, with 26 HMO plans and 29 PPO plans offered in Mecklenburg County for 2026.
Can I see any doctor I want with a Medicare Advantage PPO plan?
You can see any provider who accepts Medicare, but your cost-sharing will be higher if that provider is out-of-network for your specific plan. Unlike an HMO, a PPO will still cover a portion of out-of-network costs rather than leaving you with the full bill. You do not need a referral to book directly with a specialist under a PPO plan.
Are Medicare Advantage PPO plans available in all parts of Charlotte and Mecklenburg County?
Yes. Medicare Advantage plans, including PPOs, are available throughout Mecklenburg County, covering Charlotte and surrounding communities including Cornelius, Davidson, Huntersville, Matthews, and Pineville. The same plan options that appear in Charlotte proper are generally available county-wide, since plan availability is determined at the county level rather than the zip code level for most carriers.
Do Medicare PPO plans in Charlotte cover prescription drugs?
Most Medicare Advantage PPO plans in Charlotte include Part D prescription drug coverage as part of the plan. However, a minority of PPO plans are offered without drug coverage. If you enroll in a PPO plan without drug coverage and do not have other creditable drug coverage, you may face a Part D late enrollment penalty if you try to add coverage later. Always confirm whether your chosen plan includes drug coverage and check that your current medications are on the plan’s formulary.
How do I enroll in a Medicare Advantage PPO plan in Charlotte, NC?
You can enroll during your Initial Enrollment Period around your 65th birthday, or during the Annual Enrollment Period (October 15 through December 7) for coverage starting January 1. Certain qualifying life events, such as losing employer coverage or moving, may trigger a Special Enrollment Period. Working with a licensed Medicare insurance advisor in Charlotte, like the team at Safeguard Benefit Services, costs you nothing and ensures you compare the actual plan benefits, networks, and formularies across 30 or more carriers before you commit.
Is a Medicare Advantage PPO better than a Medicare Supplement plan for Charlotte seniors?
Neither is universally better. A Medicare Supplement plan pairs with Original Medicare and gives you broad nationwide access with predictable cost-sharing, but it carries a monthly premium and requires a separate Part D plan. A Medicare Advantage PPO usually has lower or no monthly premiums and bundles extra benefits, but restricts your network to some degree and requires you to manage cost-sharing within the plan’s structure. The right choice depends on your health needs, how often you travel, your budget, and whether your doctors participate in available PPO networks. A free side-by-side comparison from a licensed advisor is the most practical way to answer this question for your specific situation.
If you are weighing Medicare Advantage PPO options in Charlotte or anywhere in Mecklenburg County, share your biggest question or concern in the comments below. The more specific you are, the more useful the conversation becomes for everyone navigating the same decision.
We would love your feedback and any insights you would share with others. What perspective would you add?
References
- Medicare Advantage PPO plan availability and types in Charlotte, Mecklenburg County
- PPO plan enrollment counts, premiums, and carrier data for Mecklenburg County NC 2026
- Medicare Advantage PPO vs HMO plan comparison: features, costs, and enrollment rules
- How Medicare Advantage PPO plans work: flexibility, specialist access, and out-of-pocket limits
- Medicare Advantage HMO vs PPO: 2024-2025 costs and coverage differences








Get Connected