
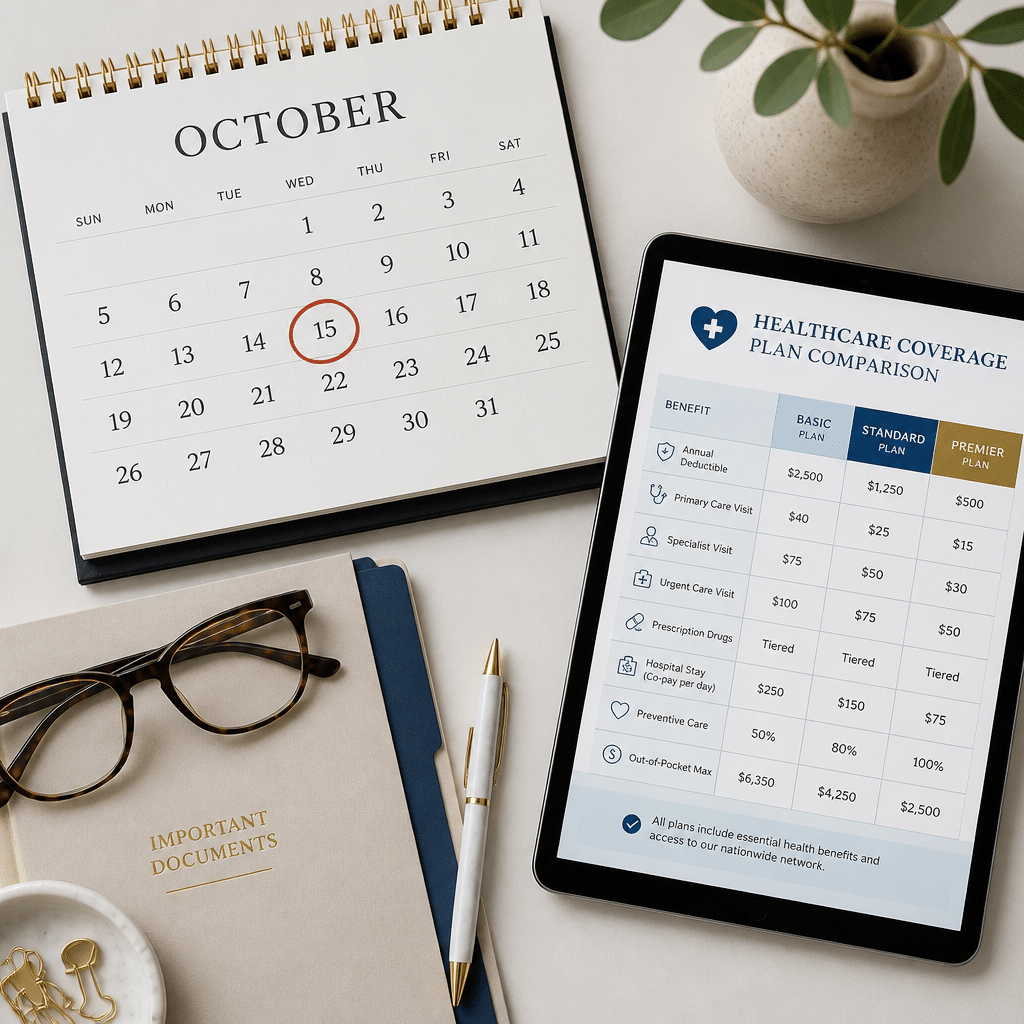
Every fall, a 54-day window opens that gives Medicare beneficiaries across North Carolina the chance to completely overhaul their health coverage, pay less next year, or keep everything exactly as it is. That window is the Medicare Annual Enrollment Period, and if you are approaching 65 or already on Medicare, missing it, or sleepwalking through it, can cost you real money. The problem is that most beneficiaries either do nothing because they assume nothing has changed, or they get overwhelmed and make a rushed decision. Neither approach serves you well. This guide walks you through exactly what happens during AEP, what you can and cannot change, and how to make a decision you will not regret in January.
Table of Contents
- What Is the Medicare Annual Enrollment Period?
- Quick Takeaways
- The AEP Timeline: What Happens and When
- What You Can and Cannot Change During AEP
- AEP vs. Medicare Advantage Open Enrollment Period
- What NC Seniors Need to Know Before AEP
- Common Mistakes to Avoid During AEP
- Frequently Asked Questions
- References
What Is the Medicare Annual Enrollment Period?
The Medicare Annual Enrollment Period (AEP) is the yearly window that runs from October 15 through December 7 every year. Any coverage changes you make during this period take effect on January 1 of the following year. It applies to Medicare Advantage (Part C) plans and Medicare Part D prescription drug plans.
AEP is not a new enrollment period for people just turning 65. Those individuals use their Initial Enrollment Period (IEP), which is a separate seven-month window around their 65th birthday. AEP is specifically for people who are already on Medicare and want to review or change what they have.
There is no requirement to do anything during AEP. If your current plan still fits your needs and will continue to be offered next year, you can let it auto-renew without lifting a finger. But given how frequently plan details change from year to year, reviewing your coverage each fall is not optional for anyone who cares about their out-of-pocket costs.
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| AEP runs October 15 to December 7 every year | Any changes you make during this window take effect January 1. Missing the deadline means waiting a full year unless you qualify for a Special Enrollment Period. |
| Your plan sends an ANOC by September 30 | The Annual Notice of Change letter outlines every change to your plan for the coming year, including premiums, deductibles, network providers, and drug formulary. Read it before AEP opens. |
| AEP does not give you open access to Medigap plans | Medicare Supplement (Medigap) plans operate under separate rules. In most states, including North Carolina, switching Medigap plans outside of your initial enrollment window requires passing medical underwriting. |
| You can switch plans as many times as you want during AEP | The last change you submit before December 7 is the one that takes effect. You are not locked into a decision the moment you make it. |
| North Carolina has 175 Medicare Advantage plans available | The sheer volume of options makes independent, side-by-side comparison essential. Working with a licensed agent who represents multiple carriers saves you time and prevents costly oversights. |
| Dropping Part D without creditable coverage triggers a penalty | If you cancel a standalone Part D plan during AEP and go without creditable drug coverage, you will face a late enrollment penalty if you re-enroll later. That penalty is permanent and follows you for life. |
| Less than 30% of Medicare beneficiaries do a thorough review each year | Most people auto-renew without comparing options. This is the single most common reason beneficiaries end up overpaying for coverage that no longer fits their needs. |
The gap between knowing AEP exists and actually using it effectively is where most NC seniors lose ground. Walking through a structured review, not just a glance at your premium notice, is what separates a smart enrollment decision from an accidental one.
The AEP Timeline: What Happens and When
AEP does not start on October 15. That is when you can begin making official changes. The preparation starts in late September, and understanding the full timeline helps you use the period strategically instead of reactively.
September 30: Your ANOC Arrives
By September 30, your Medicare Advantage or Part D plan is required to send you an Annual Notice of Change (ANOC). This document spells out every modification to your plan for the upcoming year. That includes premium changes, shifts in your drug formulary (including which tier specific medications have moved to), network changes, and adjustments to supplemental benefits like dental, vision, or hearing allowances.
In practice, a lot of people file this letter away without reading it. That is a mistake. A plan that worked well in 2024 may have restructured its drug tiers, dropped a specialist you rely on, or reduced a benefit you count on. The ANOC is your signal to shop or stay, not an administrative formality.
October 1: New Plan Details Published
Starting October 1, insurance carriers release their official plan details for the coming year. This is when you can begin comparing plans on Medicare.gov using the Plan Finder tool. You cannot make official changes yet, but you can do your research and have a list ready before October 15.
October 15 to December 7: The Enrollment Window
This is the active period. You can enroll in a new plan, switch plans, or drop coverage. The last change you submit before December 7 takes effect. If you change your mind three times, the third decision is the one that counts.
All elections made during AEP become effective on January 1 of the following year. Nothing changes mid-December or over the holidays. January 1 is the hard line.
Pro tip: Do not wait until the last week of November. Call a licensed Medicare agent in October, when agents have time to walk through options with you carefully rather than rushing through a crowded December calendar.
What You Can and Cannot Change During AEP
AEP covers Medicare Advantage and Part D plans. It does not give you universal access to every type of Medicare coverage. Knowing the boundaries prevents costly surprises.
What AEP Allows You to Do
During the Medicare Annual Enrollment Period, you can switch from Original Medicare to a Medicare Advantage plan, switch from one Medicare Advantage plan to a different one, switch back from Medicare Advantage to Original Medicare, enroll in a new standalone Part D prescription drug plan, switch to a different Part D plan, or drop your Part D plan entirely. You can also switch between different Medicare Advantage plan types, such as moving from an HMO to a PPO.
There is no limit on how many changes you can make before the December 7 deadline. If you enroll in Plan A on October 20 and then find Plan B works better for your medications on November 10, the Plan B enrollment supersedes Plan A.
What AEP Does Not Cover
This is where many people run into trouble. AEP does not give you a special window to change your Medicare Supplement (Medigap) plan. If you want to switch Medigap plans, the same underwriting rules that apply year-round still apply during AEP. In North Carolina, unless you are within your Medigap Open Enrollment Period (the six months following your enrollment in Medicare Part B) or qualify for a guaranteed issue right, an insurance company can review your medical history and potentially decline your application or charge a higher rate.
AEP also does not affect your Medicare Part A or Part B enrollment. Those follow separate enrollment rules.
Reviewing your Medicare coverage every fall is not about finding a better plan for its own sake. It is about making sure the plan you have now still does what you need it to do, because the plan itself may have changed significantly since you enrolled.
Pro tip: If you are on a Medicare Advantage plan and your primary care physician or a specialist you see regularly is no longer in the plan’s network for next year, that is a legitimate reason to switch during AEP. Verify your providers every single fall, not just when you get a complaint.
AEP vs. Medicare Advantage Open Enrollment Period
There is consistent confusion between the fall Annual Enrollment Period and the Medicare Advantage Open Enrollment Period (MA OEP), which runs January 1 through March 31. They are not the same thing, and the difference matters.
| Feature | AEP (Oct 15 – Dec 7) | MA OEP (Jan 1 – Mar 31) |
|---|---|---|
| Who can use it | All Medicare beneficiaries | Only people already enrolled in a Medicare Advantage plan as of January 1 |
| Switch from Original Medicare to MA | Yes | No |
| Switch between MA plans | Yes, unlimited changes | Yes, but only one change allowed |
| Return from MA to Original Medicare | Yes | Yes |
| Enroll in standalone Part D (without dropping MA) | Yes | Only if returning to Original Medicare |
| Number of changes permitted | Unlimited before Dec 7 | One change only |
| When changes take effect | January 1 | First day of the following month |
The MA OEP exists as a safety valve, a chance to correct a bad AEP decision in the first quarter. But it is more limited than AEP in both scope and the number of moves you are allowed to make. Using it is better than doing nothing if you made an error in the fall, but it is not a substitute for doing the work during October and November.
What NC Seniors Need to Know Before AEP
Medicare plan options in North Carolina are more varied than in many other states. That is both an advantage and a challenge: more competition can mean better pricing and benefits, but it also means more complexity in comparing options side by side.
Scale of Options in NC
North Carolina has a large Medicare population, and the plan market reflects that. The state has over two million Medicare enrollees, and the plan options span Medicare Advantage, standalone Part D, and Medigap. All North Carolina residents with Medicare have access to buy a Medicare Advantage plan with a $0 premium, though zero-premium plans are not the right fit for everyone depending on their provider needs and drug costs.
NC SHIIP: Free, Unbiased Counseling
North Carolina has a strong free counseling resource called the Seniors’ Health Insurance Information Program (SHIIP), administered through the NC Department of Insurance. SHIIP counselors are available in all 100 counties. They do not sell plans and do not endorse specific companies. They are trained to help Medicare beneficiaries understand their options without pressure.
SHIIP can be reached by phone at 1-855-408-1212 during business hours. However, SHIIP counselors are not licensed to sell plans, which means they can help you understand your options but cannot complete an enrollment for you. For actual enrollment, you need to work with a licensed Medicare insurance agent or contact a plan directly.
Working With a Licensed Medicare Agency in Charlotte
For NC seniors who want both education and hands-on enrollment support, working with a licensed Medicare agency like Safeguard Benefit Services in Charlotte offers advantages that a state counseling service cannot. An agency that represents 30 or more carriers can compare Medicare Supplements, Medicare Advantage plans, and Part D options side by side, using your specific doctors, medications, and financial situation as the filter. That is a fundamentally different experience from reviewing a government comparison tool on your own.
The right time to reach out is before October 15, not after. Agents are available to review your ANOC with you, explain what changed in your current plan, and identify whether switching makes sense for your situation. That pre-AEP consultation costs you nothing and can save you hundreds of dollars over the course of a year.
Common Mistakes to Avoid During AEP
After working through hundreds of Medicare enrollment situations, the same errors come up repeatedly. Here is what to avoid.
Assuming Your Plan Did Not Change
Plans change every year. Premiums go up. Drug formularies get restructured. Supplemental benefits get reduced or eliminated. Some of the benefits that initially drew enrollees to a Medicare Advantage plan may be reduced or eliminated between years, making it essential for beneficiaries to check carefully before simply renewing. Do not assume last year’s plan is this year’s plan without reading your ANOC.
Focusing Only on the Premium
A lower monthly premium is not automatically a better deal. A plan that charges $0 per month may have a much higher out-of-pocket maximum, higher copays for specialist visits, or a drug formulary that puts your most expensive medications on Tier 4 or 5. Always calculate total cost of ownership, not just the premium line.
Dropping Part D Without a Replacement
If you drop a standalone Part D plan during AEP and go without creditable prescription drug coverage, you will face a late enrollment penalty when you re-enroll. That penalty is calculated as a percentage of the national base beneficiary premium for every month you were without coverage, and it is permanent. It does not go away after a set number of years. This is one of the most consequential mistakes a beneficiary can make during AEP.
Missing the December 7 Deadline
If you miss AEP, your current plan auto-renews and you generally cannot make changes until the next AEP unless you qualify for a Special Enrollment Period. SEPs are granted for specific qualifying life events such as moving out of your plan’s service area, losing eligibility for other coverage, or qualifying for Medicaid. Do not plan on a SEP bailing you out if you simply ran out of time during AEP.
Not Verifying Your Doctors and Drugs
A Medicare Advantage plan that does not include your primary care physician, cardiologist, or other specialists in its network forces you to either pay out-of-network rates or change providers. Before confirming any Medicare Advantage plan, verify every provider you see, not just your primary doctor, is included for the upcoming plan year.
Frequently Asked Questions
What is the Medicare Annual Enrollment Period?
The Medicare Annual Enrollment Period (AEP) is a yearly window from October 15 through December 7 during which Medicare beneficiaries can review and change their Medicare Advantage and Part D prescription drug plan coverage. Any changes made during AEP take effect on January 1 of the following year. It is not an enrollment period for people new to Medicare, who use a separate Initial Enrollment Period around their 65th birthday.
Can I change my Medicare Supplement (Medigap) plan during AEP?
AEP does not provide any special access to change Medigap plans. The same rules that apply throughout the year still apply during AEP. In most states, including North Carolina, switching Medigap plans outside of your initial open enrollment window requires passing medical underwriting. That means an insurer can review your health history and may decline your application or charge a higher premium based on pre-existing conditions. If you want to switch Medigap plans, talk to a licensed agent about your options and timing before AEP, not during it.
What happens if I miss the December 7 AEP deadline?
If you miss the December 7 deadline, your current Medicare plan auto-renews for another year and you generally cannot change coverage until the next AEP. However, if you qualify for a Special Enrollment Period due to a qualifying life event, such as moving, losing coverage, or gaining Medicaid eligibility, you may be able to make changes outside of AEP. Otherwise, the Medicare Advantage Open Enrollment Period (January 1 to March 31) gives existing Medicare Advantage enrollees one additional opportunity to switch plans or return to Original Medicare.
How many times can I change my plan during AEP?
There is no limit on the number of plan changes you can make between October 15 and December 7. If you enroll in one plan and then find a better option the following week, you can submit a new enrollment and the most recent one takes effect. The final decision you make before the December 7 deadline is the plan that becomes active on January 1. This flexibility is one reason it pays to start comparing early in October rather than rushing in late November.
Does AEP apply to Medicare beneficiaries in North Carolina the same way it does everywhere else?
Yes, the AEP dates, rules, and allowed changes are federally standardized and apply equally to Medicare beneficiaries in North Carolina and every other state. What differs in North Carolina is the specific plan availability, premiums, and network options. NC has over two million Medicare enrollees and a competitive plan market, which means comparing options here requires reviewing the specific plans available in your county, not just national averages. A licensed NC Medicare agent can run a county-specific comparison for you at no cost.
Is it ever smart to keep my current plan and not change anything during AEP?
Absolutely, but that decision should be active, not passive. Reading your Annual Notice of Change, verifying that your doctors and drugs are still covered at the same tier and cost, and confirming that no better-value plan has entered your area for the coming year is how you conclude that staying put is the right call. The mistake is not reviewing your plan at all and just letting it auto-renew by default. If after a genuine comparison you confirm your current plan still wins, keeping it is a perfectly sound decision.
Have you reviewed your Medicare coverage during AEP before, and did you end up making a change or staying with your current plan? Share your experience in the comments below.
References
- WellCare overview of the Medicare Annual Enrollment Period and what changes take effect January 1
- North Carolina Health News: what NC Medicare enrollees should expect and the importance of annual plan review
- Medical News Today breakdown of Medicare plan options and enrollment figures in North Carolina
- NC Department of Insurance SHIIP program: free Medicare guidance available in all 100 NC counties
- Center for Medicare Advocacy guide to AEP elections, effective dates, and the Medicare Advantage Open Enrollment Period








Get Connected