
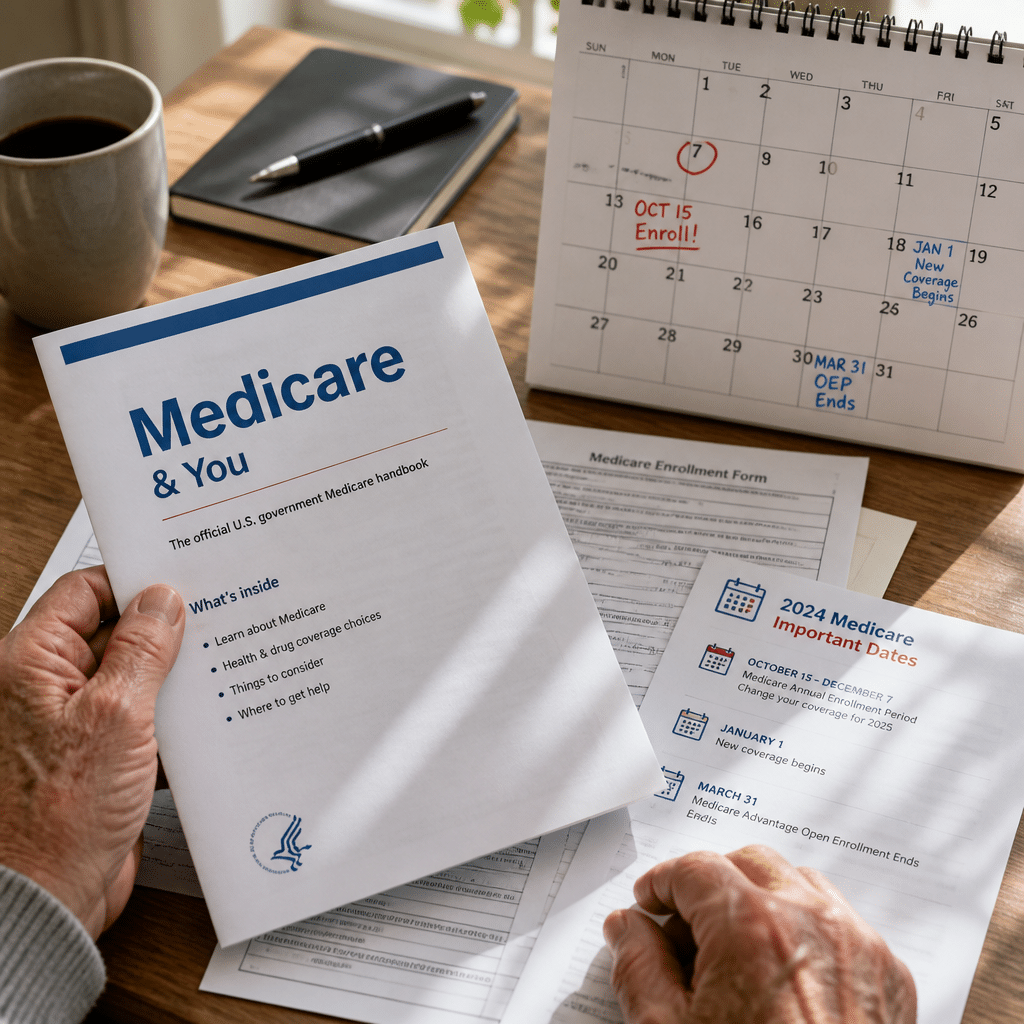
Most people turning 65 in Charlotte assume Medicare is simple: you sign up, pick a plan, and you’re covered. That assumption costs thousands of dollars every year. The reality is that Medicare has strict enrollment windows, permanent financial penalties for missing deadlines, and plan structures that can quietly lock you out of your preferred doctor or hospital. These are not edge cases. These are Medicare mistakes seniors make every single day, and they are almost always avoidable with the right guidance before the decision is made, not after.
Table of Contents
- Quick Takeaways
- Mistake 1: Missing the Initial Enrollment Period
- Mistake 2: Ignoring Part D Prescription Drug Coverage
- Mistake 3: Choosing a Plan Without Checking Provider Networks
- Mistake 4: Not Understanding Medigap Open Enrollment
- Mistake 5: Overlooking Income-Based Premium Surcharges
- Comparison: Your Main Coverage Paths
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| The Initial Enrollment Period is only 7 months | It opens 3 months before your 65th birthday month and closes 3 months after. Missing it means permanent Part B penalties added to your premium for life. |
| Skipping Part D creates a permanent penalty | Even if you take no prescriptions today, going without creditable drug coverage for more than 63 days triggers a penalty that compounds every year you delay. |
| Charlotte’s two major health systems do not always share networks | Atrium Health and Novant Health can be on different Medicare Advantage plans. Choosing the wrong plan means losing access to one system entirely. |
| Medigap Open Enrollment is a one-time window | You have 6 months from the date your Part B starts to enroll in a Medicare Supplement plan with no medical underwriting. After that window, health history can disqualify you. |
| IRMAA is based on income from two years ago | A large one-time event like selling a home or taking an IRA distribution can trigger higher Medicare premiums two years later, even if your income has since dropped. |
| Medicare Advantage and Medigap work very differently | Low-premium Advantage plans carry copays and network limits. Medigap has higher monthly premiums but near-zero cost at the point of care. |
| Working past 65 does not automatically protect you from penalties | If your employer has fewer than 20 employees, Medicare is primary and you must enroll in Part B on time or face a penalty regardless of your employer coverage. |
Mistake 1: Missing the Initial Enrollment Period
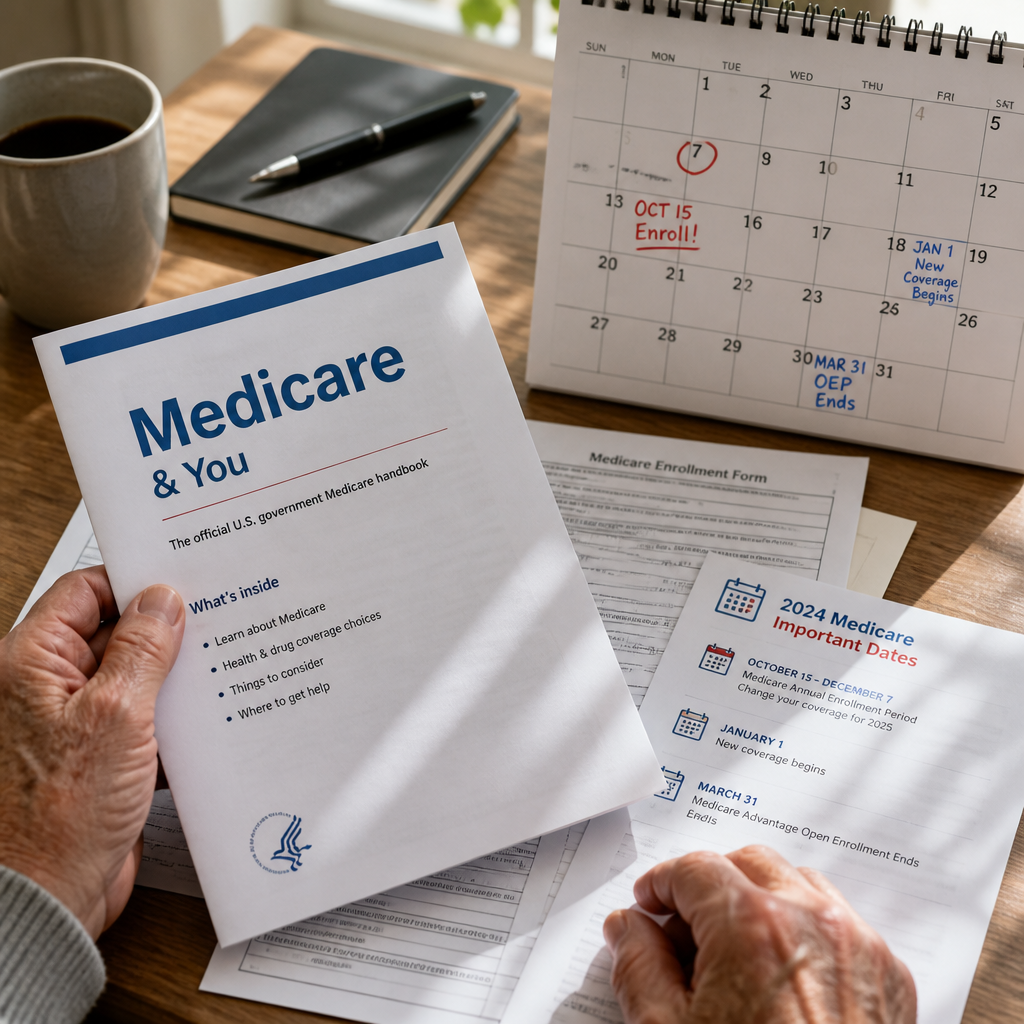
The Initial Enrollment Period (IEP) is a 7-month window that starts 3 months before your 65th birthday month, includes your birthday month, and ends 3 months after. Miss it, and you will wait for the General Enrollment Period, which runs from January 1 through March 31 each year, with coverage not starting until July 1. That is a coverage gap measured in months, not days.
Worse than the gap is the penalty. For every 12-month period you were eligible for Part B but did not enroll, your Part B premium increases by 10 percent permanently. That surcharge stays with you for life. The base Part B premium in 2026 is $185 per month. A two-year delay adds $37 per month to every future bill, every month, for the rest of your life.
The Working-Past-65 Trap
Many people in Charlotte assume that staying on their employer’s health plan past age 65 protects them from any Medicare penalty. That is only true if the employer has 20 or more employees. If your company has fewer than 20 employees, Medicare becomes your primary insurance the moment you turn 65, and your employer plan becomes secondary. Continuing to rely on that employer plan without enrolling in Part B is a serious Medicare enrollment error that catches people completely off guard when a major claim arrives.
If you do have qualifying employer coverage through a larger company, you will have an 8-month Special Enrollment Period after your employment or coverage ends. Do not confuse that with a COBRA period. COBRA does not count as creditable coverage for purposes of avoiding the Part B late enrollment penalty.
Pro tip: Mark your calendar 4 months before your 65th birthday and start the enrollment process then. That gives you time to sort out Social Security coordination, employer coverage questions, and plan selection without rushing toward a deadline.
Mistake 2: Ignoring Part D Prescription Drug Coverage
A large number of Charlotte seniors skip Medicare Part D at enrollment because they are not currently taking any regular prescriptions. This decision almost always costs more in the long run. The Part D late enrollment penalty is 1 percent of the national base beneficiary premium for every month you went without creditable drug coverage. As of 2025, that base premium is $36.78 per month, and the penalty compounds with every passing month.
If you go 24 months without coverage, you are paying a 24 percent penalty added to your plan premium, every month, for as long as you have Part D. And because the base beneficiary premium changes each year, so does the dollar amount of your penalty. It does not stay fixed at the figure calculated when you finally enrolled.
What Counts as Creditable Coverage
Creditable prescription drug coverage includes a qualifying employer plan, VA drug benefits, or a Medicare Advantage plan that includes Part D. If you are leaving employer coverage and it included drug benefits, confirm in writing that it was creditable before you assume you have no penalty exposure. Plans are required to notify you annually whether their coverage is creditable, but those notices are easy to overlook.
The safest approach to Part D: if you are eligible and not enrolled in a plan with creditable drug coverage, enroll in a Part D plan during your Initial Enrollment Period even if your current medication costs are low. A $12-per-month Part D plan now is almost always cheaper than years of compounding penalties plus uncovered drug costs later.
Mistake 3: Choosing a Plan Without Checking Provider Networks
This is the mistake that blindsides more Charlotte-area seniors than any other. Charlotte is served by two major health systems: Atrium Health (including Carolinas Medical Center) and Novant Health (including Novant Health Presbyterian Medical Center). These two systems do not always participate in the same Medicare Advantage networks. An HMO plan built around one system may exclude the other entirely.
The practical consequence is real: you enroll in a Medicare Advantage plan in October during the Annual Enrollment Period, your plan starts January 1, and in February you go to see a specialist at the system your plan does not cover. You are now either paying full out-of-network rates or scrambling for a different specialist mid-treatment.
HMO vs. PPO in Charlotte’s Market
Within Medicare Advantage, a PPO gives you the flexibility to see out-of-network providers at a higher cost share. An HMO typically requires you to stay in-network entirely or pay the full bill yourself. If you regularly use both Atrium and Novant providers, a Medicare Supplement (Medigap) plan paired with Original Medicare is often the cleaner solution. With Medigap, there is no network at all. Any provider who accepts Medicare accepts your coverage, whether that is Carolinas Medical Center, Novant Health Presbyterian, or a specialist you travel to see.
The mistake is enrolling in whichever plan has the lowest premium without first mapping your current doctors, specialists, and preferred facilities to that plan’s network directory. Network directories change annually. A doctor who was in-network in 2024 may not be in-network in 2025.
Pro tip: Before enrolling in any Medicare Advantage plan, call both the plan and your doctor’s billing office directly to confirm participation. Plan directories are not always updated in real time, and a confirmation from two sources protects you from surprises at the point of care.
Mistake 4: Not Understanding Medigap Open Enrollment
The Medigap Open Enrollment Period is one of the most underestimated windows in all of Medicare. It lasts exactly 6 months, beginning the month you turn 65 and are enrolled in Medicare Part B. During this window, any insurance company selling Medicare Supplement plans in North Carolina must offer you any plan they sell, at the same rate as anyone your age, regardless of your health history. They cannot deny you coverage or charge you more because of a pre-existing condition.
Once that 6-month window closes, you lose those guaranteed issue rights in most situations. Insurance companies in North Carolina can then use medical underwriting, meaning your health history becomes a factor in whether they will cover you at all, and at what price. A prior cancer diagnosis, a recent heart procedure, or even controlled diabetes can result in a denial or a significantly higher premium.
Why Seniors Wait Too Long
The most common reason people miss this window is that they enroll in a Medicare Advantage plan during their IEP because the monthly premium is low or zero, and they plan to switch to a Medigap plan later when their health needs increase. That plan is fundamentally flawed. By the time health needs increase, the Medigap Open Enrollment window is long closed, and the very health conditions driving the switch may be the conditions that get the Medigap application denied.
North Carolina does have limited guaranteed issue rights in specific situations, such as when a Medicare Advantage plan leaves your service area. But those are narrow exceptions, not a reliable safety net. The open enrollment window at 65 is the right time to make the Medigap decision if Medigap is the right fit for your situation.
Mistake 5: Overlooking Income-Based Premium Surcharges
IRMAA (Income-Related Monthly Adjustment Amount) is a surcharge added to Part B and Part D premiums for higher-income beneficiaries. Most Charlotte seniors approaching Medicare have never heard of it until they receive their first Social Security statement showing a premium far above the standard amount. The reason it catches people off guard is that it is calculated using your income from two years prior.
Your 2026 Medicare premiums are based on your 2024 Modified Adjusted Gross Income. If 2024 was the year you sold a second property, converted a large IRA to a Roth, or took a significant one-time distribution, your 2026 premiums could be substantially higher than the base rate, even if your current income has returned to a normal level.
IRMAA and Life Events
There is a process to appeal an IRMAA determination if your income has since dropped due to a qualifying life event such as retirement, divorce, or the death of a spouse. The appeal is handled through the Social Security Administration and requires documentation of the income change. It is worth pursuing because even one IRMAA tier can add hundreds of dollars per month to your premiums.
The broader point is this: if you are planning a large financial transaction in the two years before you turn 65 (or in any year once you are on Medicare), the Medicare premium impact should be part of that conversation with your financial advisor. Managing income timing is one of the few tools available to reduce or avoid IRMAA legally.
Comparison: Your Main Coverage Paths
Most Charlotte seniors will choose between three main coverage structures. Understanding what each one actually means in daily life is the foundation of making a good Medicare decision.
| Coverage Path | How It Works in Practice | Best Suited For |
|---|---|---|
| Medicare Advantage (Part C) | Private plan replaces Original Medicare. Network-based (HMO or PPO). Often includes Part D and extra benefits. Lower monthly premium but copays and cost-sharing apply at point of care. | Seniors with predictable, low health care use who want one card, low premiums, and are comfortable with one provider network (Atrium or Novant, not both). |
| Original Medicare + Medigap + Part D | Federal Parts A and B handle most costs. Medigap fills the gaps (deductibles, coinsurance). Separate Part D plan covers prescriptions. No networks: any Medicare-accepting provider is covered. | Seniors who want predictable costs, access to both Atrium and Novant, freedom to see specialists without referrals, and no surprises when using care. |
| Original Medicare Only | Parts A and B with no supplement. Covers 80% of approved costs after deductibles. Leaves 20% coinsurance with no cap on your exposure. No drug coverage. | Almost no one. This structure leaves significant financial exposure. It is rarely the right choice as a long-term plan and is included here only because many people end up here by default due to Medicare enrollment errors. |
Frequently Asked Questions
What happens if I miss my Medicare Initial Enrollment Period?
If you miss your IEP without qualifying employer coverage, you will wait for the General Enrollment Period (January 1 through March 31), with coverage starting July 1 of that year. You will also pay a Part B late enrollment penalty of 10 percent for every 12-month period you were eligible but not enrolled. This penalty is permanent and added to your premium for as long as you have Medicare.
Do I need Part D if I am not taking any prescriptions right now?
Yes, in most cases you should still enroll in a Part D plan. Going without creditable drug coverage for more than 63 days triggers a late enrollment penalty that compounds for every month of the gap. A low-cost Part D plan now is nearly always less expensive than the penalty plus uncovered drug costs later when health needs change.
Can I see doctors at both Atrium Health and Novant Health in Charlotte on a Medicare Advantage plan?
It depends entirely on the specific plan. Some Medicare Advantage PPO plans in the Charlotte area include both systems, but HMO plans often do not. You must verify each plan’s current network directory before enrolling. The safest path to access both systems without network restrictions is Original Medicare paired with a Medigap supplement, since Medigap has no provider network at all.
When is the best time to enroll in a Medicare Supplement (Medigap) plan?
The best and most protected time is during your Medigap Open Enrollment Period, which begins the month you turn 65 and are enrolled in Part B and lasts for 6 months. During this window, no insurer in North Carolina can deny you coverage or charge you more based on your health history. After this window closes, medical underwriting applies and enrollment is not guaranteed.
What is IRMAA and how can I avoid it?
IRMAA is an income-related surcharge added to your Part B and Part D premiums if your Modified Adjusted Gross Income from two years ago exceeds certain thresholds. You can appeal it through the Social Security Administration if your income has since dropped due to a qualifying life event such as retirement or the loss of a spouse. The best way to manage IRMAA proactively is to consider the Medicare premium impact before making large one-time income events in the years just before and during Medicare enrollment.
Is it a problem to rely on COBRA instead of enrolling in Medicare Part B at 65?
Yes. COBRA is not considered creditable coverage for avoiding the Medicare Part B late enrollment penalty. If you rely on COBRA instead of enrolling in Part B during your Initial Enrollment Period, you risk a permanent Part B penalty when you do finally enroll. Your 8-month Special Enrollment Period for Part B begins when your active employer coverage ends, not when COBRA ends.
How can Safeguard Benefit Services help me avoid these mistakes?
Safeguard Benefit Services offers free consultations with licensed Medicare specialists based in Charlotte, North Carolina. They compare plans from more than 30 carriers, help you map your current doctors and prescriptions to available plans, and walk you through every enrollment window and deadline before it becomes a problem. Their guidance is personalized, not scripted, and they provide support year-round, not just at enrollment time.
Have you or someone you know run into one of these Medicare mistakes? Share your experience in the comments below so others in the Charlotte area can learn from it before their own enrollment deadline arrives.
References
- North Carolina Department of Insurance guide to Medicare enrollment periods and Initial Enrollment Period rules
- NC Health News report on Medicare Advantage enrollment trends and complaints in North Carolina
- Official Medicare.gov guidance on how to avoid late enrollment penalties for Parts A, B, and D
- National Council on Aging overview of the most common Medicare enrollment mistakes and how to avoid them
- All About Seniors resource on common Medicare enrollment errors including network and plan selection mistakes








Get Connected