
If you’re searching “what is Medicare Charlotte,” you’re likely approaching age 65 and want clear answers. Medicare is federal health insurance, but your local doctors, hospitals, and plan choices in Charlotte matter, too. Below we answer the most common questions in plain English so you can move forward with confidence.
What is Medicare in Charlotte, and who qualifies at 65?
Medicare is the federal health insurance program for people 65 or older, certain people under 65 with disabilities, and people of any age with End‑Stage Renal Disease (ESRD); people with ALS can also qualify for Medicare earlier than 65. You choose between Original Medicare (Parts A & B) or a private Medicare Advantage plan (Part C) to receive your benefits. Enrollment for Parts A and B typically happens through Social Security.
In Charlotte, Medicare works the same as anywhere in the U.S., but your provider networks and local plan availability can differ. That’s why comparing options by ZIP code and checking your specific doctors and hospitals is essential.
What does Medicare cover in Charlotte—Parts A, B, C, and D explained?
Part A (Hospital Insurance) helps pay for inpatient hospital stays, skilled nursing facility care, hospice, and some home health care. Most people pay no premium for Part A if they worked and paid Medicare taxes long enough.
Part B (Medical Insurance) covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. You pay a monthly premium for Part B, and most services have cost sharing.
Part C (Medicare Advantage) is an alternative way to receive Parts A and B through private plans; many include Part D drug coverage and extras like dental, vision, or hearing. Plans must follow Medicare rules and cover nearly all medically necessary services Original Medicare covers.
Part D (Prescription Drug Coverage) helps pay for outpatient prescriptions. You can get it through a standalone Part D plan (with Original Medicare) or bundled in a Medicare Advantage plan.
How do Medigap (Medicare Supplement) policies work for Charlotte retirees?
With Original Medicare, you can buy a Medigap policy to help pay deductibles, copays, and coinsurance. Your one-time, six-month Medigap Open Enrollment Period starts the first month you’re 65 or older and enrolled in Part B. During this window, insurers generally can’t use medical underwriting.
After that six-month window, your options may be limited or cost more. North Carolina’s Department of Insurance and SHIIP offer unbiased guidance on Medigap and can help you understand plan options statewide.
Which is better in Charlotte: Original Medicare with Medigap, or a Medicare Advantage HMO/PPO?
The “better” choice depends on your doctors, medications, and budget. Medicare Advantage HMOs usually require in-network care and referrals; PPOs allow some out-of-network use at higher cost. Original Medicare with Medigap typically has broader provider access, but you’ll buy drug coverage separately with Part D.
For Charlotte-area residents, compare how plans work with your preferred hospitals and specialists before enrolling. The Medicare.gov Plan Finder lets you enter your ZIP code, doctors, and drugs to estimate total annual costs across plans.
How do enrollment windows and penalties actually work?
Your Initial Enrollment Period (IEP) is seven months—three months before, the month of, and three months after your 65th birthday. If you miss it (and don’t qualify for a Special Enrollment Period), you may wait for the General Enrollment Period (Jan 1–Mar 31), with coverage starting the month after you sign up.
If you have qualifying employer group coverage at 65, you can delay Part B and use a Special Enrollment Period (SEP) later without a late penalty. Always confirm eligibility before delaying.
Late penalties can be permanent. Part B: 10% added to your premium for each full 12-month period you could’ve enrolled but didn’t. Part D: 1% per month without creditable drug coverage, based on the national base beneficiary premium ($38.99 in 2026).
What about prescriptions—do I need Part D in Charlotte if I don’t take meds?
If you skip drug coverage and lack creditable coverage, you could owe a Part D penalty later. Even if you take few or no medications, consider a low-premium plan to protect yourself from future costs and penalties.
Need help with high drug bills? Medicare’s new Prescription Payment Plan lets you spread Part D out-of-pocket costs across the year, and Extra Help lowers costs for eligible beneficiaries. Both are worth reviewing if you have expensive therapies.
Are there Special Needs Plans (SNPs) or Extra Help programs available in Charlotte?
Yes. Special Needs Plans (SNPs) serve people with both Medicare and Medicaid (D‑SNP), certain chronic conditions (C‑SNP), or those in institutions (I‑SNP). SNPs tailor benefits, provider choices, and care coordination to your situation. Availability varies by county and year.
Cost assistance includes Extra Help for Part D and Medicare Savings Programs that can pay some or all of your Part B premium if you qualify. In North Carolina, the Department of Insurance and SHIIP can help you apply.
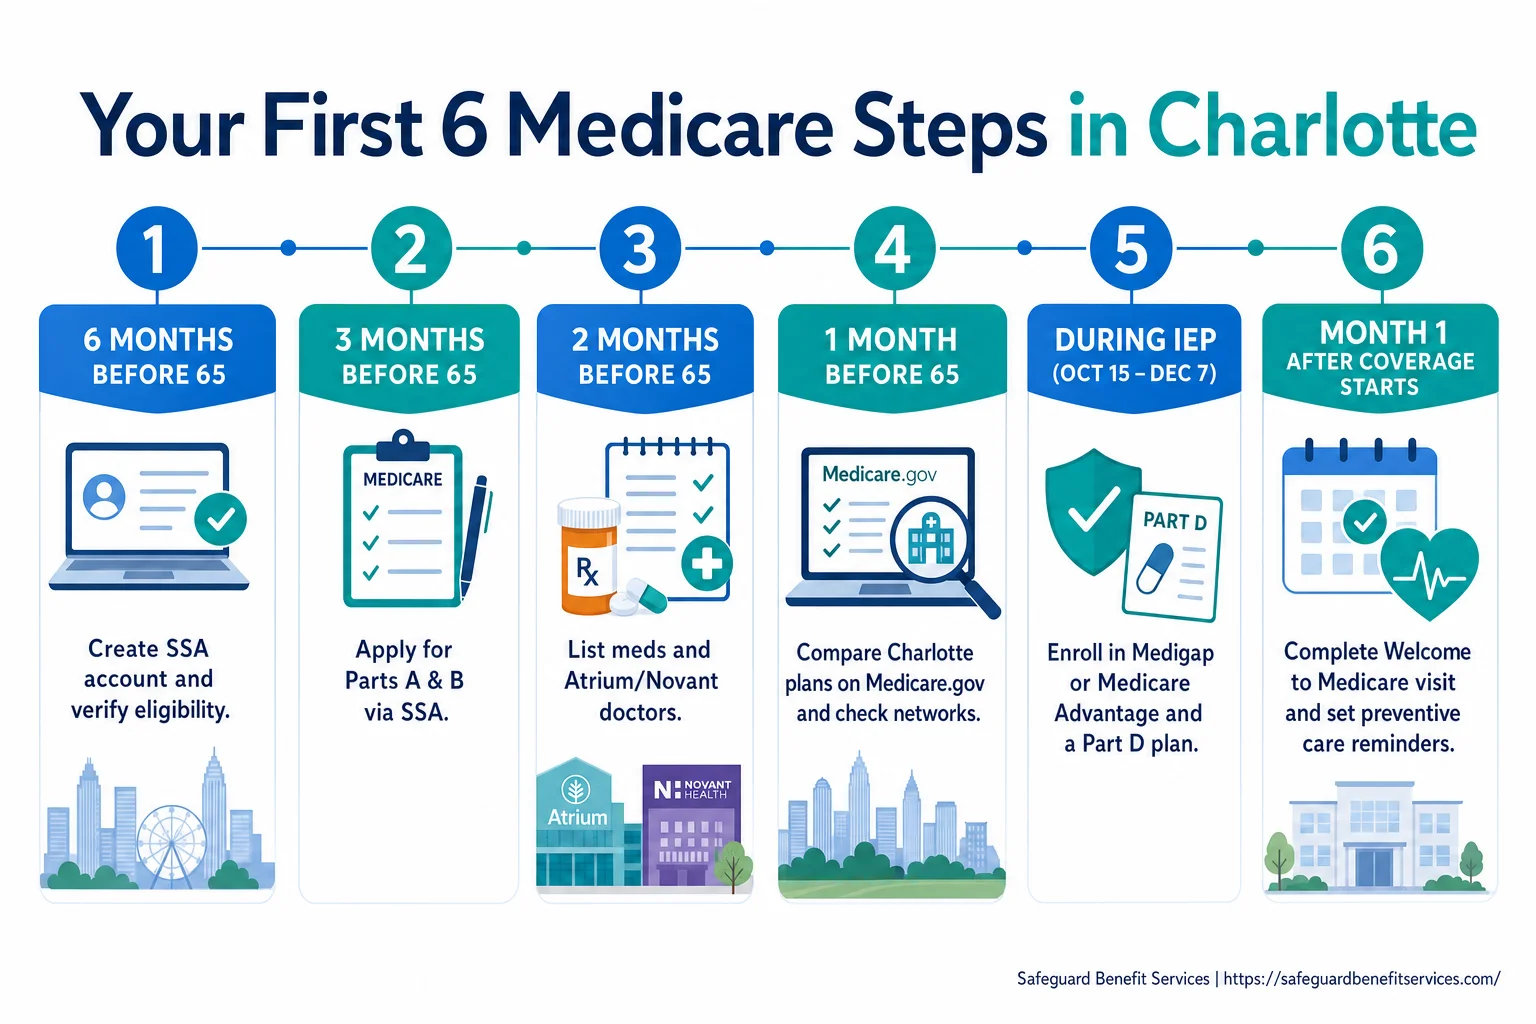
What first steps should I take 6 months before turning 65 in Charlotte?
- Create or sign in to your Social Security account and confirm your Medicare eligibility timeline.
- List your current prescriptions and preferred doctors/hospitals (for many Charlotte residents, this means Atrium Health or Novant Health).
- Decide between Original Medicare + Medigap + Part D versus Medicare Advantage, then compare ZIP-code-specific plans on Medicare.gov.
- Apply for Parts A and B at Social Security, then enroll in Medigap or Medicare Advantage and, if needed, a Part D plan.
- Schedule your one-time “Welcome to Medicare” preventive visit during your first 12 months with Part B.
How do I check if my Atrium Health or Novant Health doctors are in network?
Hospitals recommend you verify plan networks with the insurer before enrolling. Atrium Health and Novant Health both provide guidance and list participating plans; always confirm your specific provider’s participation for the upcoming plan year.
Because many Medicare Advantage plans are built around distinct networks, checking your primary care doctor, specialists, and preferred hospital in Charlotte—plus nearby communities like Matthews, Pineville, Huntersville, and Gastonia—should be part of your short list before you apply.
Where can I compare plans and get free, unbiased help in North Carolina?
Use the official Medicare Plan Finder to compare Medicare Advantage, Part D, and Medigap options by ZIP code, doctors, drugs, and pharmacies. The tool estimates your yearly costs and shows quality metrics to help you weigh trade-offs.
For one-on-one counseling, North Carolina’s SHIIP offers free, unbiased help on Medicare, Medigap, Advantage, and drug plans. SHIIP is administered by the North Carolina Department of Insurance and serves Charlotte and surrounding counties.
How do plan quality ratings factor into my Charlotte decision?
Medicare publishes annual Star Ratings for Medicare Advantage and Part D plans to measure quality and member experience. For the 2026 plan year, CMS reported that about 64% of enrollees are in contracts with four or more stars. Consider ratings along with provider networks, drugs, and total costs.
Quick answers to “what is Medicare Charlotte” questions we hear most
Is Original Medicare accepted at major Charlotte systems? Original Medicare is widely accepted; confirm any specialist’s participation and whether you’ll add Medigap and Part D for fuller protection.
Can I keep my doctors on Medicare Advantage? Often yes—if they’re in network. HMOs typically require in-network care and referrals; PPOs offer more flexibility but can cost more out of network. Always check networks before you enroll.
Do I really need Part D if I use few medications? Most people should enroll to avoid the 1% per-month late penalty and to protect against future costs. Even low-premium plans can be valuable safeguards.
First steps if you’re turning 65 soon in Charlotte
- Mark your Initial Enrollment Period dates and set reminders to avoid penalties.
- List your medications and preferred pharmacies; use Plan Finder to estimate total annual cost across plans.
- Call your doctors’ offices to confirm Medicare and, if considering Medicare Advantage, the exact HMO/PPO networks they accept for the coming plan year.
- If your income is limited, ask SHIIP about Extra Help and Medicare Savings Programs.
- Schedule your “Welcome to Medicare” preventive visit once Part B starts.
Need local, no-pressure guidance to compare your Charlotte options?
Choosing between Original Medicare with Medigap versus a Medicare Advantage HMO/PPO can feel overwhelming—especially when you’re trying to keep your Charlotte doctors and control prescription costs. Safeguard Benefit Services is an independent North Carolina Medicare agency that follows CMS and state Department of Insurance guidelines; we’ll compare plans side by side, check Atrium/Novant networks, and walk you through enrollment step by step. Contact us at safeguardbenefitservices.com for a friendly, no-obligation consult.
This article is for informational purposes only and does not constitute financial advice. Consult a qualified professional for your specific situation.
Sources
- medicare.gov — How Does Medicare Work
- medicare.gov — Plan Compare
- medicare.gov — Original Medicare
- medicare.gov — Part B
- medicare.gov — Your Health Plan Options
- medicare.gov — Part D
- medicare.gov — Basics
- medicare.gov — Ready To Buy
- medicare.gov — Compare
- medicare.gov — When Does Medicare Coverage Start
- cms.gov — Original Part A B
- medicare.gov — Avoid Penalties
- medicare.gov — Costs
- medicare.gov — Prescription Payment Plan
- medicare.gov — SNP
- medicare.gov — Drug Costs
- ssa.gov — Sign Up
- atriumhealth.org — Medicare
- ncdoi.gov — Medicare And Seniors Health Insurance Information Program Shiip
- cms.gov — 2026 Star Ratings Fact Sheet
- medicare.gov — Welcome To Medicare Preventive Visit








Get Connected